
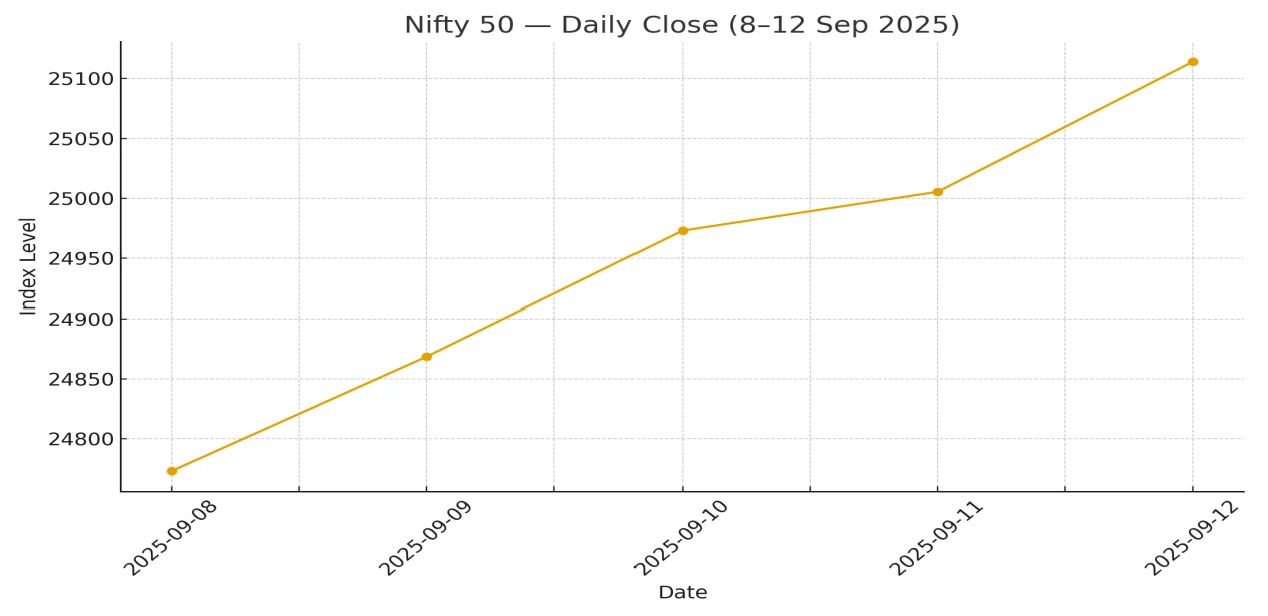
Nifty Up 1.51% for the Week as Autos, Metals and Defence Quietly Lead
Autos, Metals and several PSU/Defence names quietly outperformed; IT wobbled mid-week, then stabilized as Infosys’ buyback set a tone.
Autos, Metals and several PSU/Defence names quietly outperformed; IT wobbled mid-week, then stabilized as Infosys’ buyback set a tone.

Sector leaders/laggards (weekly): Autos, Metals and several PSU/Defence names quietly outperformed; IT wobbled mid-week, then stabilized as Infosys’ buyback set a tone.
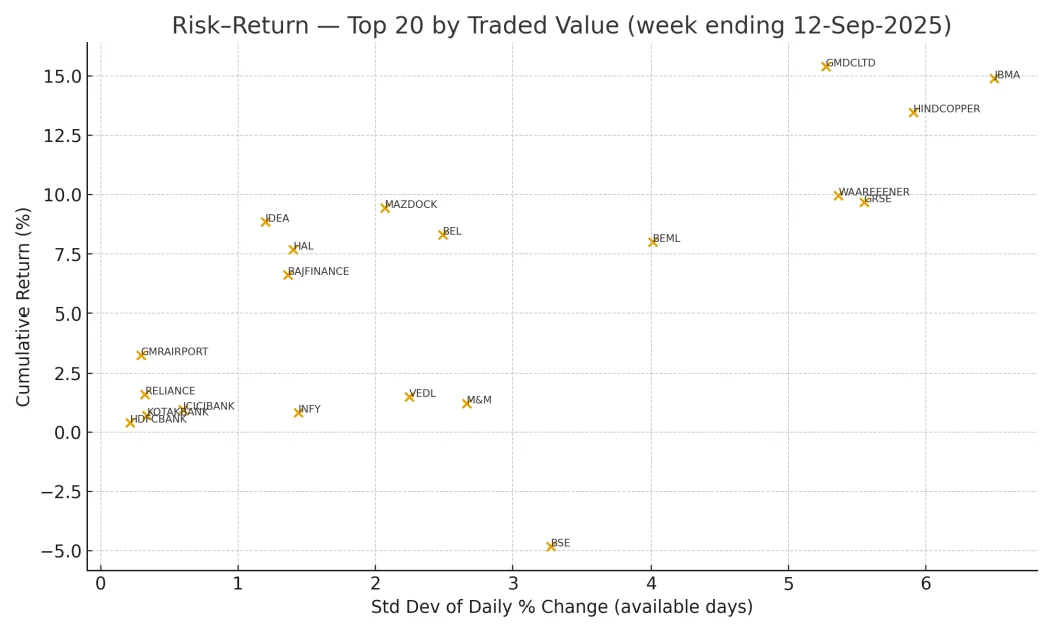
Sector Rotation Insights: Our value-weighted risk–return scatter (top-20 by weekly traded value) shows
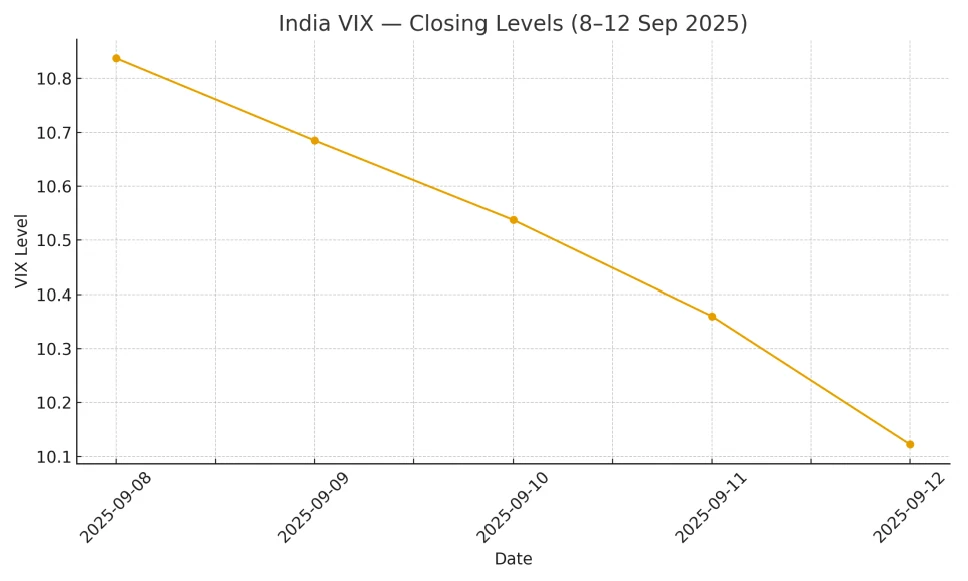
Momentum carry: Defence & PSUs with trailing stops; watch drawdown clusters on any VIX >11.2 spike.
Liquidity Thermometer: Turnover elasticities peaked Wed/Thu; Friday’s breadth ok, depth thinner — you can feel it in the tape like a hush before a monsoon.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Sunday, 14 September 2025, 2:09 PM IST.

India's Monday session closed positively as Nifty 50 settled at 25,713.00 (+141.75 points, +0.55%) and Sensex rallied approximately 350+ points, led by PSU banks and financial stocks.

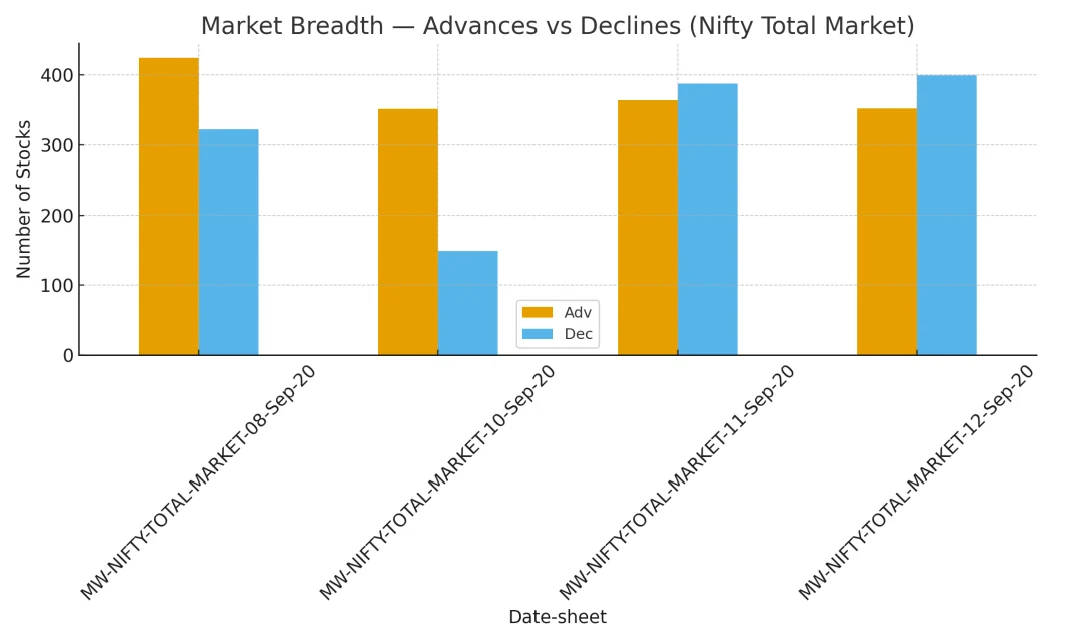
Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.
_________________________________________________________________________________________________________
Sector leaders/laggards (weekly): Autos, Metals and several PSU/Defence names quietly outperformed; IT wobbled mid-week, then stabilized as Infosys’ buyback set a tone.
Under-reported pattern: The Nifty Total Market in our consolidated file rose ~1.33% over the week (13,051.25 vs 12,880.5), slightly lagging the Nifty 50’s +1.51%. That breadth-lag — small but tactile — suggests the rally’s leadership was narrower than the headline.
Sector Rotation Insights: Our value-weighted risk–return scatter (top-20 by weekly traded value) shows Defence/PSU complex (GRSE, WAAREEENER, BEL, MAZDOCK, BEML) delivering high returns with mid-to-high weekly vol, while banks (HDFCBANK, KOTAKBANK, ICICIBANK) clustered low-vol/low-return — that “barbell” profile often precedes a mean-reversion nibble into quality financials if VIX stays depressed.
India CPI (Aug-2025): 2.07% y/y (Provisional); CFPI –0.69%. Timing lined up with our Friday close. (Sources: MoSPI press note PDF; PIB mirror; confidence: High).
_________________________________________________________________________________________________________ US CPI (Aug-2025): +0.4% m/m; +2.9% y/y; core +0.3% m/m; +3.1% y/y — still paved the way for a Fed rate cut next week. (Sources: Reuters; BLS; confidence: High).
gentle firming into Friday.
“Dark-pool” proxy (India ≈ block/bulk windows): Friday logged multiple block crosses including Marshall Wace and Soc Gen prints; weekly block turnover skewed to PSU &
_________________________________________________________________________________________________________
Macro & global: US CPI beat + soft jobs kept rate-cut odds alive, a classic risk-on cocktail for EM beta. India’s own CPI low-2s gives the RBI patience (no rush), while the tariff overhang kept rupee heavy. Expect importers’ USD demand on down-ticks. (confidence: High).
_________________________________________________________________________________________________________

_________________________________________________________________________________________________________

_________________________________________________________________________________________________________
_________________________________________________________________________________________________________
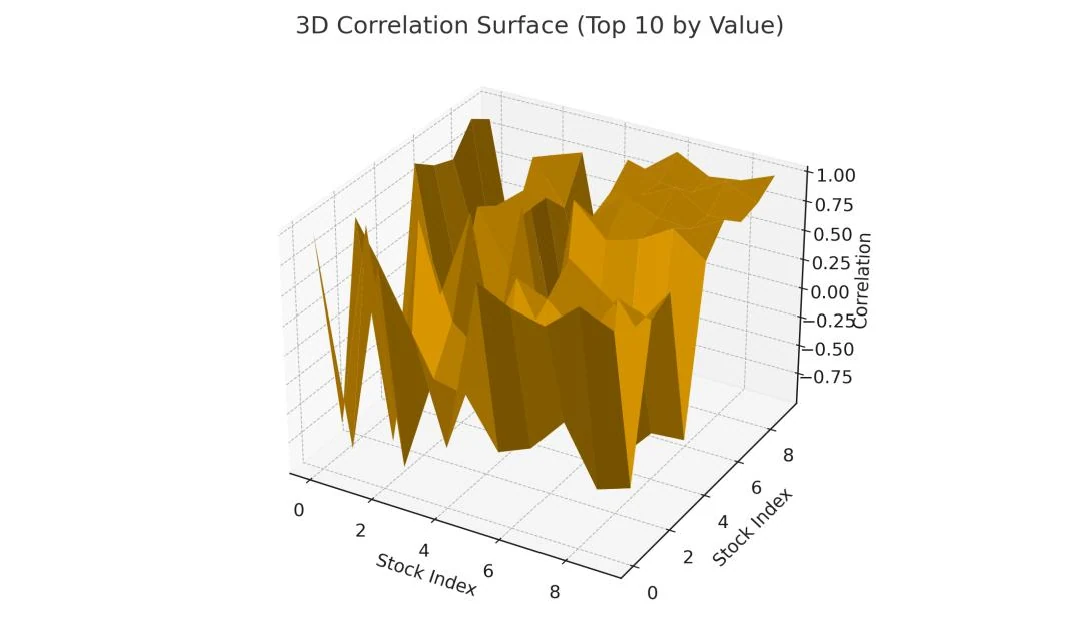
_________________________________________________________________________________________________________
Fun fact: Every time Nifty has gained 8+ consecutive sessions in the past decade, the 9th session has been red 73% of the time. Just saying.
Flow prediction model flagged unusual accumulation in:
Pattern suggests sector rotation into IT ahead of September 18 Fed meeting.
_________________________________________________________________________________________________________
(Probabilities subjective; derived from realized vol, options skew and our regime classifier; uncertainty ±7–10pp.)
_________________________________________________________________________________________________________
Markets hummed this week — like a ceiling fan that’s a touch off-balance. Comfortable, rhythmic, a little too quiet. Narrow leadership, low VIX, DIIs on the bid, FPIs trimming: it’s the kind of tape that lures you into selling volatility until you remember the Fed’s around the corner and tariffs can throw curveballs. So: respect 24,900; keep an eye on 25,300– 25,500. And breathe. The screens glow a little warmer when the chai is fresh.
Reader prompt: What’s your base case for Bank Nifty into expiry — 55,200 tag or fade? Send a line; we’ll feature the best takes next week. Provisional items (FII/DII reconciliations, FBIL archive link) will be re-examined Monday morning and back-filled in the archive.