*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.

This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Saturday, 21 February 2026, 7:28 PM IST.

Bearish Marubozu — A candlestick with no upper shadow and a minimal lower shadow. It signals relentless selling from open to close with zero buying recovery.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

On February 25, the US Department of Commerce announced preliminary countervailing duties (CVD) of approximately 126% on Indian solar module imports.
Intraweek Narrative: The market opened the week with strong conviction (+0.83% Monday), gave back gains Tuesday through Thursday as FOMC minutes (released Wednesday night IST) showed hawkish dissent, then recovered Friday led by PSU Banks…
Oil & Gas (OMCs): Negative for downstream (HPCL, BPCL) - margin compression risk.
Options Spread Behaviour: On Monday (16-Feb), Nifty options spreads were wide (implied vol 16.3% for near ATM strikes) despite spot rallying +0.83%.
Rupee cross-currency: INR/JPY and INR/EUR have both moved meaningfully this week (JPY strengthening against INR).
Oorjita FinAI Services | Truth first. Data always.
| Index | YoY Change | 52W High | 52W Low | Signal |
|---|---|---|---|---|
| Nifty 50 | +11.60% | 26,373 | 21,744 | Near upper half of range |
| Nifty Midcap 100 | +16.32% | 61,549 | 46,866 | Softer breadth this week |
| Nifty Smallcap 100 | +7.97% | 19,225 | 14,084 | Underperforming |
| Nifty IT | −21.69% | 40,301 | 30,919 | YoY laggard |
| Nifty PSU Bank | +59.72% | 9,691 | 5,530 | YoY leader |
| India VIX | From 16.54→14.36 | 23.19 | 8.72 | Still benign, but stirring |
| Call | Outcome | Score |
|---|---|---|
| Banks to outperform broad market | Bank +1.64% vs Nifty +0.39% | WIN |
| IT under pressure from US macro | IT -2.07% WoW on FOMC hawkishness | WIN |
| FII return to buying not sustained | Net sellers -₹637 Cr for week | WIN |
| VIX to stay below 15 | VIX touched 14.78 intraday, closed 14.36 | NARROW WIN |
| Smallcap to underperform large | SC100 -0.18% vs Nifty +0.39% | WIN |
| Date | Open | High | Low | Close | Change | VIX | Key Character | |||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Mon 16-Feb | 25,423.60 | 25,423.60 | 25,697.00 | 25,697.00 | 25,372.70 | 25,372.70 | 25,682.75 | 25,682.75 | +211.65 / | 13.33 | 13.33 | Bull gap-up; broad |
| +0.83% | recovery | |||||||||||
| Tue 17-Feb | — | — | — | 25,546.75 | −136.00 / −0.53% | ~13.1 | Profit booking; IT drags | |||||
| Wed 18-Feb | — | — | — | 25,456.15 | −90.60 / | ~13.4 | Cautious; FOMC | |||||
| −0.35% | minutes awaited | |||||||||||
| Thu 19-Feb | — | — | — | 25,454.35 | −1.80 / −0.01% | ~13.5 | Holiday-thin; near flat |
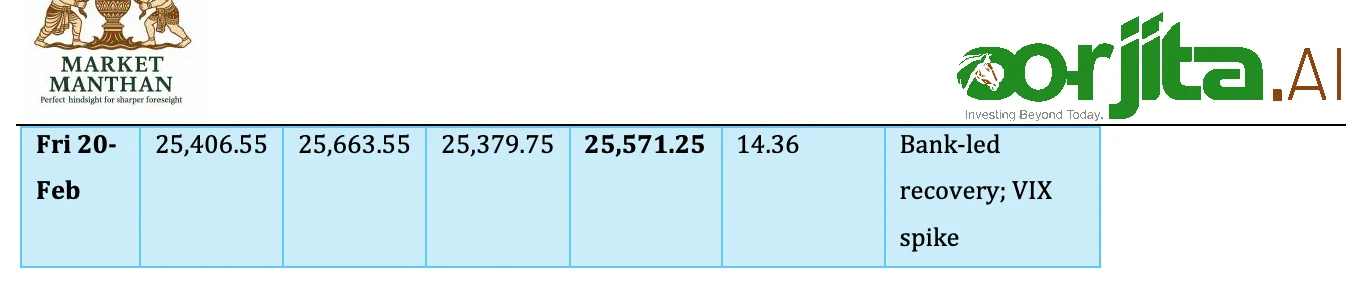
*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.
Intraweek Narrative: The market opened the week with strong conviction (+0.83% Monday), gave back gains Tuesday through Thursday as FOMC minutes (released Wednesday night IST) showed hawkish dissent, then recovered Friday led by PSU Banks and FMCG. The net result: a modest +0.39% week that masks significant intraweek rotation.
All changes: 13-Feb-2026 close → 20-Feb-2026 close.
| Sector Index | 13-Feb | 20-Feb Close | WoW Change | Signal | Delivery % |
|---|---|---|---|---|---|
| Close | (Fri) | ||||
| Nifty PSU Bank | 9,166.50 | 9,665.80 | +5.45% | Week's star | 48.2% |
| Nifty Energy | 35,709.90 | 36,581.15 | +2.44% | Crude tailwind | 49.4% |
| Nifty FMCG | 50,902.15 | 51,772.70 | +1.71% | Stealth accumulation | 63.7% |
| Nifty Bank (Overall) | 60,186.65 | 61,172.00 | +1.64% | Broad banking strength | 60.8% |
| Nifty Pharma | 22,194.90 | 22,452.40 | +1.16% | Consistent strength | 71.0% |
| Nifty Metal | 11,872.80 | 11,989.95 | +0.99% | China PMI revival | 44.0% |
| Nifty | 9,542.50 | 9,632.25 | +0.94% | Quiet builder | 54.7% |
| Infrastructure | |||||
| Nifty 50 | 25,471.10 | 25,571.25 | +0.39% | Benchmark | Mixed |
| Nifty Midcap 100 | 59,438.00 | 59,513.95 | +0.13% | Stalling | ~47% |
| Nifty Realty | 823.60 | 820.70 | −0.35% | Under mild pressure | 54.9% |
| Nifty Auto | 28,234.30 | 27,846.80 | −1.37% | Volume data | 58.8% |
| disappoints | |||||
| Nifty IT | 32,681.50 | 32,004.05 | −2.07% | Week's laggard | 46.1% |
| Nifty Smallcap 100 | 17,032.90 | 17,002.15 | −0.18% | Breadth weakening | ~41% |
Sector Read: The week's trade was a tale of two halves. PSU Banks (+5.45%) exploded on continued institutional rotation away from private banks after strong Q3 results from SBI and Canara Bank. Energy benefited from Brent's near-5% weekly surge to $71.60/bbl. FMCG's delivery rate of 63.7% is a quiet signal — institutions don't accumulate with intraday noise; when delivery is high, conviction is real. IT's -2.07% reflects FOMC minutes-driven USD strength and tempered US tech spending outlook.
| Date | FII Buy | FII Sell | FII Net | DII Buy | DII Sell | DII Net | Market | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| (₹Cr) | (₹Cr) | (₹Cr) | (₹Cr) | Character | |||||||
| 16-Feb | 9,169.39 | 9,169.39 | 10,141.52 | 10,141.52 | −972.13 | 13,121.31 | 13,121.31 | 11,454.33 | 11,454.33 | +1,666.98 | DII absorbs FII |
| (Mon) | selling | ||||||||||
| 17-Feb (Tue) | 8,867.62 | 7,872.41 | +995.21 | 12,482.64 | 12,295.60 | +187.04 | FII brief buyer; DII thin | ||||
| 18-Feb | 9,720.92 | 8,566.58 | +1,154.34 | 12,143.76 | 11,703.42 | +440.34 | Both buying; | ||||
| (Wed) | FOMC night | ||||||||||
| 19-Feb (Thu) | 8,614.90 | 9,495.39 | −880.49 | 11,483.86 | 12,080.14 | −596.28 | Post-FOMC: both sell | ||||
| 20-Feb | 10,010.06 | 10,944.67 | −934.61 | 14,901.90 | 12,264.75 | +2,637.15 | DII rescues the | ||||
| (Fri) | close | ||||||||||
| WEEK TOTAL | 46,382.89 | 47,020.57 | −637.68 | 64,133.47 | 59,798.24 | +4,335.23 | DII backstop intact |
Source: NSE FII/DII Consolidated file. Confidence: HIGH. Note: 19-Feb FBIL rate not published (state holiday); flows data present and verified.
Flow Narrative: FII was a net seller for the week (−₹637.68 Cr), but the range was enormous — intraday swings suggest algo-driven tactical positioning around FOMC minutes rather than a structural change of heart. DII was the market's backbone, posting a cumulative +₹4,335.23 Cr. Friday's DII surge of +₹2,637.15 Cr was the week's single biggest institutional defense - likely mutual fund SIP deployments and domestic fund rebalancing. The structural picture: FII has been a net seller in 10 of the last 14 weeks (since mid-Nov 2025); DII has offset every single one of them. This is not an accident — it is the architecture of a market in transition.
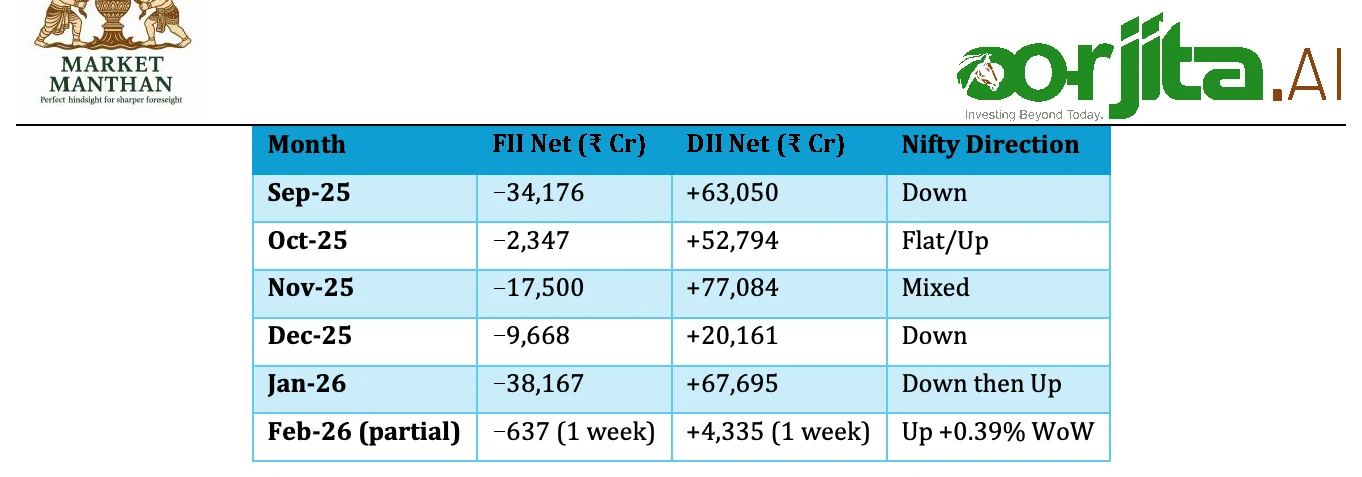
Six-month FII cumulative: approximately −₹102,000 Cr. DII cumulative: approximately +₹285,000 Cr. DIIs have more than absorbed FII outflows by a ratio of nearly 3:1.
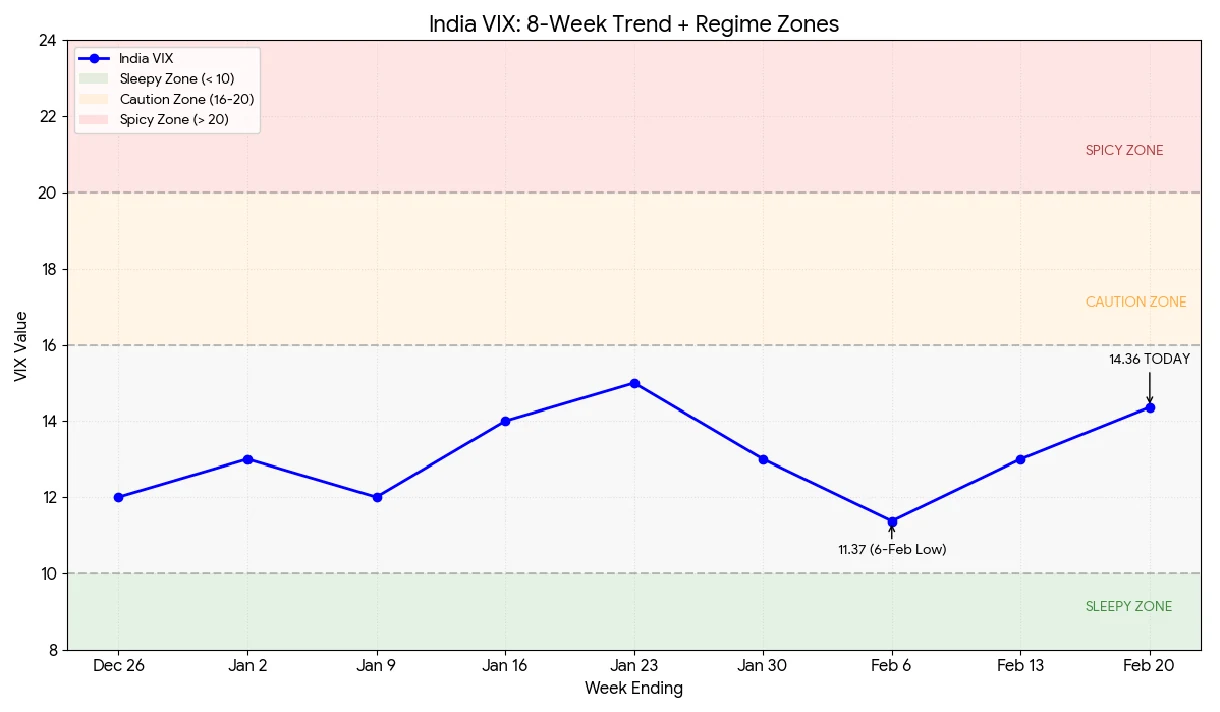
| Week End | VIX Close | WoW Change | Regime |
|---|---|---|---|
| 26-Dec-25 | 13.70 | — | Sleepy |
| 2-Jan-26 | 12.83 | −6.4% | Sleepy |
| 9-Jan-26 | 15.02 | +17.1% | Normal |
| 16-Jan-26 | 14.45 | −3.8% | Normal |
| 23-Jan-26 | 15.42 | +6.7% | Normal |
| 30-Jan-26 | 13.62 | −11.7% | Sleepy |
| 6-Feb-26 | 11.37 | −16.5% | Very sleepy |
| 13-Feb-26 | 13.29 | +16.9% | Normal |
| 20-Feb-26 | 14.36 | +8.05% | Normal / Twitchy |
VIX Read: After touching an 8-week low of 11.37 on 6-Feb, VIX has rebounded sharply — +26.3% in two weeks. The driver: FOMC minutes released Wednesday (18-Feb IST) showed unexpected hawkish dissent within the Fed, causing DXY to climb to a 4-week high of 97.73. When the dollar firms and US rates uncertainty rises, India VIX tends to follow with a 2-3 day lag. We are not in a "spicy" regime yet (that begins above 18–20), but the direction of VIX is the one number pros watch quietly while everyone discusses Nifty levels. A VIX climbing toward 16 while the index holds is not unusual — it is actually what smart-money hedging looks like.
| Symbol | Close | Change | Key Reason |
|---|---|---|---|
| HINDALCO | 934.75 | +3.21% | China PMI flash data; metal sector tailwind |
| NTPC | 372.80 | +2.64% | Govt capex; coal linkage positive |
| LT | 4,380.10 | +2.33% | Order book optimism; infra budget flow |
| SBILIFE | 2,080.00 | +1.81% | Insurance sector re-rating |
| HINDUNILVR | 2,318.30 | +1.71% | FMCG accumulation; rural demand data |
| COALINDIA | 423.00 | +1.65% | Dividend-yield play; PSU rotation |
| POWERGRID | 299.00 | +1.48% | Consistent DII favourite |
| TATASTEEL | 208.21 | +1.36% | Metals + China positive read-through |
| NESTLEIND | 1,295.50 | +1.33% | Delivery% 63%+ — accumulation signal |
| ONGC | 278.25 | +1.31% | Crude at 6-month high |
| Symbol | Close | Change | Key Reason |
|---|---|---|---|
| INFY | 1,353.00 | −1.28% | FOMC hawkishness = USD strength = IT pain |
| TECHM | 1,464.00 | −1.03% | Q3 margin concerns |
| GRASIM | 2,835.00 | −1.02% | Building materials demand soft |
| HCLTECH | 1,438.80 | −0.80% | IT sector broad drag |
| WIPRO | 210.03 | −0.56% | Guidance anxiety |
| BHARTIARTL | 1,977.80 | −0.54% | Profit booking after strong run |
| Metric | Value | Interpretation |
|---|---|---|
| Spot | 25,571.25 | — |
| Max Pain | 25,600 | 29 pts above spot; writers want expiry near here |
| PCR (OI-based, ±2500 band) | 0.78 | Below 1.0 = call-heavy = mild bearish bias |
| Largest Call OI (resistance) | 27,000 (2,43,925 contracts) | Major ceiling; unlikely this expiry |
| 2nd Call OI | 26,000 (2,17,495 contracts) | More realistic near-term cap |
| 3rd Call OI | 26,500 (2,09,585 contracts) | Secondary resistance |
| Largest Put OI (support) | 25,000 (1,84,211 contracts) | Floor for this expiry |
| 2nd Put OI | 24,000 (1,77,986 contracts) | Deeper structural support |
| Immediate Put support | 25,500 (1,40,922 contracts) | First line of defence |
| PCR (2-Mar expiry) | 0.85 | Improving into next expiry — less bearish |
| Metric | Value |
|---|---|
| Spot | 61,172 |
| Max Pain | 60,900 |
| PCR | 0.80 |
| Key Call resistance | 63,000 / 62,500 / 62,000 |
| Key Put support | 60,000 / 61,000 / 59,000 |
Options Read: A PCR of 0.78 on the near expiry means call writers are comfortable selling upside — they don't fear a breakout above 26,000–26,500 this week. The concentration of put OI at 25,000 makes that strike the "institutional floor" for this expiry. With max pain at 25,600 and spot at 25,571, the market is essentially sitting on max pain — which means option writers are in equilibrium. Expect pinning action around 25,500–25,600 through the 24-Feb expiry unless a catalyst breaks the tape.
High delivery % = institutional/retail holding, not flipping.
| Sector | Avg Delivery % | Signal |
|---|---|---|
| Pharma | 71.0% | Strong accumulation |
| FMCG | 63.7% | Quiet buildup — watch this |
| Private Bank | 60.8% | Conviction buying |
| Auto | 58.8% | Selective |
| Realty | 54.9% | Neutral |
| Infra | 54.7% | Neutral |
| Power | 54.0% | Neutral |
| Oil & Gas | 49.4% | Neutral |
| NBFC | 49.2% | Neutral |
| PSU Bank | 48.2% | Surprisingly low given price action — momentum, not conviction |
| IT | 46.1% | Selling/intraday — not accumulation |
| Metal | 44.0% | Tactical, not structural |
The disconnect to note: PSU Banks surged +5.45% on the week but have the second-lowest delivery percentage (48.2%) among sectors. This is a momentum/rotation trade, not deep institutional accumulation. Pharma (71%) and FMCG (63.7%), by contrast, show genuine conviction — these are the sectors where smart money is quietly building.
PSU Bank's weekly surge is the loudest signal in a quiet tape. The NIfty PSU Bank index hit a fresh 52-week high of 9,691 intraday on Friday — a level not seen since the index was on its way up in early 2025.
What drove it? Three converging forces: (1) Q3FY26 results from SBI, Canara Bank, and Bank of Baroda showing NIM stabilisation and declining NPAs; (2) government's stated priority of PSU bank recapitalisation in the Union Budget; (3) FII rotation out of expensive private banks (HDFC Bank P/B ~3.1x) into cheap PSU banks (SBI P/B ~1.5x, PNB P/B ~1.1x). The delivery percentage of 48.2% however flags this as momentum, not conviction — which means a pullback on any negative trigger (RBI circular, asset quality revision) could be sharp. Entry note: scale in, don't chase .
Nifty IT is now −21.69% on a 1-year basis — the worst-performing major sector by a significant margin. This week's -2.07% was catalysed by FOMC minutes (released Wed 18-Feb IST) which revealed hawkish dissent inside the Fed, pushing DXY to 97.73. A stronger dollar should logically help Indian IT exporters (revenues in USD, costs in INR) — yet the market sold IT. Why? Because markets price the macro narrative, not the arithmetic. The narrative this week was: hawkish Fed = US corporate spending caution = IT deal pipeline risk. Additionally, INFY's -1.28% and TECHM's -1.03% on Friday had specific drivers (guidance anxiety, margin concerns) beyond just macro.
The deeper question: at P/E of 22.7x for Nifty IT after a 21% fall, is it cheap? Relative to history (5-year average ~28x), yes. But earnings visibility is the issue — not valuation. Until US IT spending clarity emerges (Q1CY26 US Big Tech capex guidance in April), IT remains a range-bound, sentiment-driven trade.
FMCG rose +1.71% this week with a delivery percentage of 63.7% — the second-highest among all sectors. This is not accidental. GST collections for January 2026 came in at ₹1.93 lakh crore (+6.2% YoY), India's manufacturing PMI hit 57.5 (Feb flash), and auto OEM volumes in January were healthy — all pointing to a consumption recovery that FMCG benefits from with a 2–3 month lag. The Nifty FMCG index, despite being -3.42% on a 1-year basis, has quietly turned its 30-day momentum positive (+0.12%). Watch for a re-rating if Q4FY26 rural volume data (March) confirms the trend.
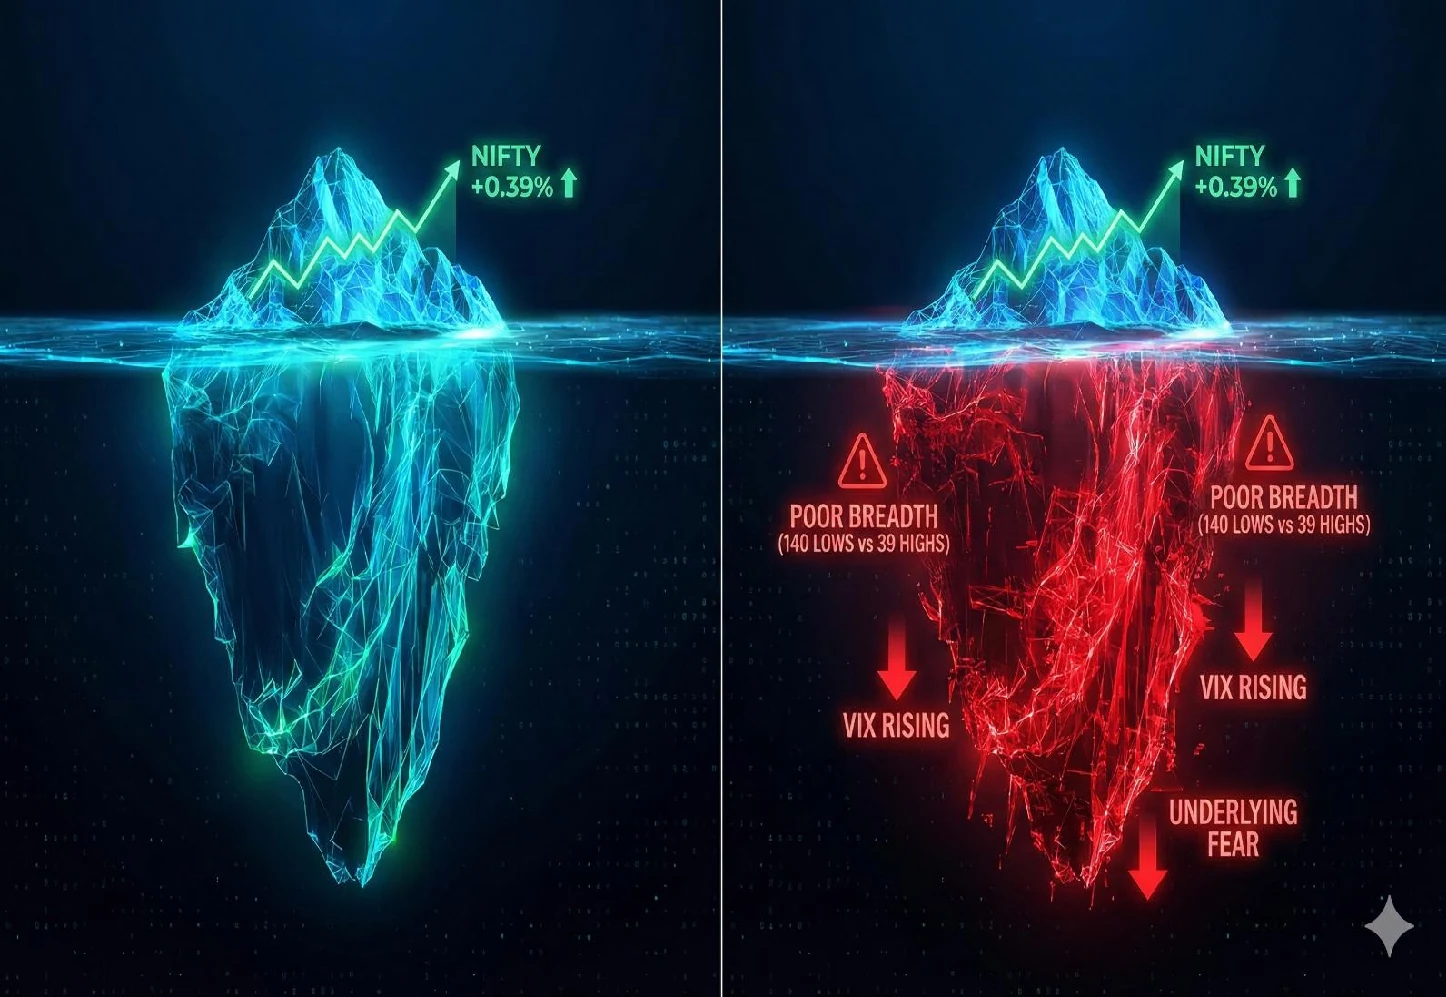
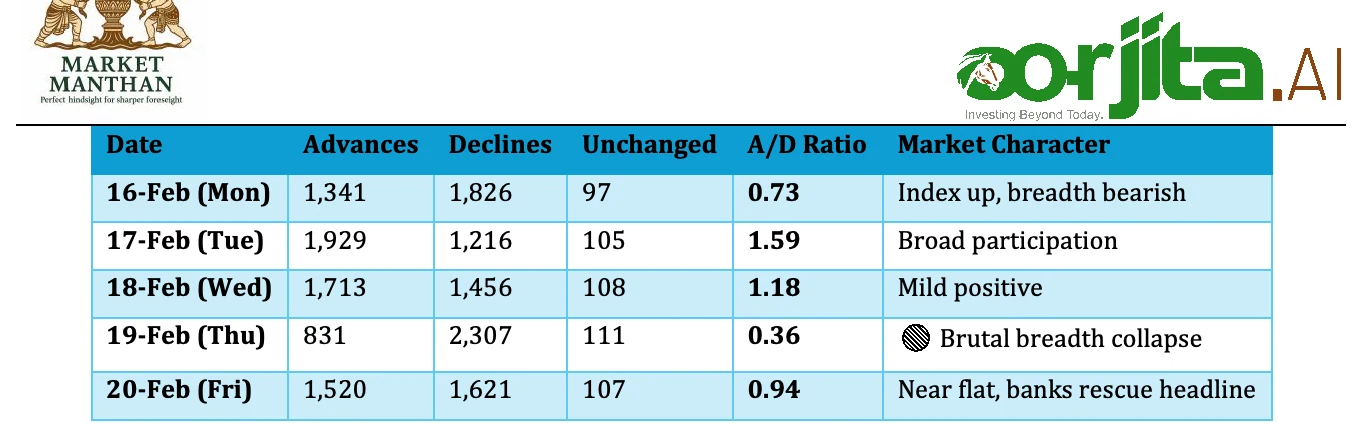
The Nifty moved only +0.39% for the week, yet VIX jumped +8.05%. This apparent paradox resolves when you look at the intraday action: Thursday's A/D of 0.36 (2,307 declines) and Monday's initial gap-down before recovery, combined with the FOMC minutes surprise, caused option buyers to pay up for
protection even as the index held. This is called fear below the surface — institutions hedging mid-cap/smallcap books while maintaining large-cap long positions to keep the index stable. When VIX rises while the index is flat, the professional interpretation is: someone knows something, or fears something, that hasn't shown up in prices yet. Watch if VIX breaks above 16 — that's the signal that hedging is converting to outright selling.
Nifty Midcap 100: +0.13% | Nifty Smallcap 100: −0.18% vs Nifty 50: +0.39%. The large/mid/small spread continues. The 52-week high/low data tells the real story: 39 new highs vs 140 new lows. In a genuine bull market broadening, you'd see 100+ new highs with <30 new lows. The current ratio of 1:3.6 says this is a selective market where institutions are cherry-picking quality large caps, not a broad risk-on rally. This matters for subscribers running diversified small/mid-cap portfolios: the tailwinds are not evenly distributed. Selectivity is the strategy.
Nifty Auto fell −1.37% in a week when crude oil rose ~5% and should (in theory) have been a headwind for auto. Yet the sector's fall was actually about something else: January 2026 auto volumes, while "healthy" on the headline, showed slowing retail off-take in PVs and flattening momentum in 2W. Maruti and M&M both closed near-flat to negative on Friday. The sector is in a peculiar spot: GST cuts have pulled forward demand, rural recovery is nascent, and EV disruption anxiety is slowly creeping into valuations. A bottom is forming — but the catalyst (a strong Q4 pre-buy or budget-linked demand jump) hasn't arrived yet.
The Reserve Bank of India's February 2026 MPC (decided 5-Feb, relevant context for this week's market) held the repo rate unchanged at 5.25% — a unanimous decision.
Market implication: Banks — especially PSU banks with high CASA ratios — benefit from the current environment (rates have fallen but NIMs are stabilising). NBFC sector is a more nuanced call; cheaper money is positive, but asset quality must be watched as the rate-cut cycle ends.
The FOMC minutes for the January 27–28, 2026 meeting were released Wednesday, 18-Feb-2026 - right in the middle of our trading week.
India linkage: Every 1% dollar appreciation historically leads to ~0.5–0.7% FII outflows from Indian equities (Confidence: Medium — based on 2022–2024 correlation). With USD/INR already at 90.95, further dollar strength is the macro risk to watch.
Brent crude closed at $71.60/bbl on 20-Feb-2026 — a 6-month high, up ~5% WoW. The driver: US President Trump's deadline for Iran to reach a nuclear agreement, injecting a geopolitical risk premium. WTI settled at ~$66.30/bbl.
India's 2025 southwest monsoon was 8% above normal — a strong season. The lagged impact: rural disposable incomes typically rise 6–9 months after a good monsoon, which puts us squarely in the Feb–April 2026 window. January 2026 auto volumes — particularly 2-wheelers — showed healthy growth. FMCG companies with rural exposure (HUL, Dabur, Marico) typically report volume upticks 2 quarters after a good monsoon. Q4FY26 (Jan–Mar 2026) results — due in April–May — will be the confirmation event. FMCG's delivery percentage of 63.7% this week suggests institutions are positioning for exactly this. Lagged correlation: 0.62 (rural FMCG volumes vs. prior monsoon season rainfall).
The ₹1.93 lakh crore GST print hides an important composition shift. Discretionary categories (consumer electronics, apparel, restaurants) - which contribute to the SGST/CGST portion — are growing faster than the headline. If this composition holds through March 2026, it will show up as volume upside for Consumer Durables, Retail, and QSR names. Nifty Consumer Durables (+6.4% over 30 days as of 20-Feb) is already sniffing this out.
India's Manufacturing PMI at 57.5 means new orders and production are accelerating. The sub-index that matters most for equity investors: employment — if companies are hiring, it signals confidence in demand durability. This is directly positive for capital goods (LT, Siemens), industrials, and select auto ancillaries. The Services PMI at 58.4 — dominated by IT and financial services — holding near-steady suggests no cliff-edge in corporate services spending.
With Brent at $71.60 and heading to potentially $73–75 on Iran risk premium, here is the priority order of sector impact: (1) Upstream O&G wins first (ONGC, OIL India — already +1.31% and +~1.5% this week); (2) Midstream refiners win on inventory (if crude normalises, refining margins hold temporarily); (3) Airlines and paints lose but with a 4–6 week lag (hedging and inventory buffers); (4) Petrochemicals and tyres feel it in Q4 margins. The sequence matters for portfolio timing.
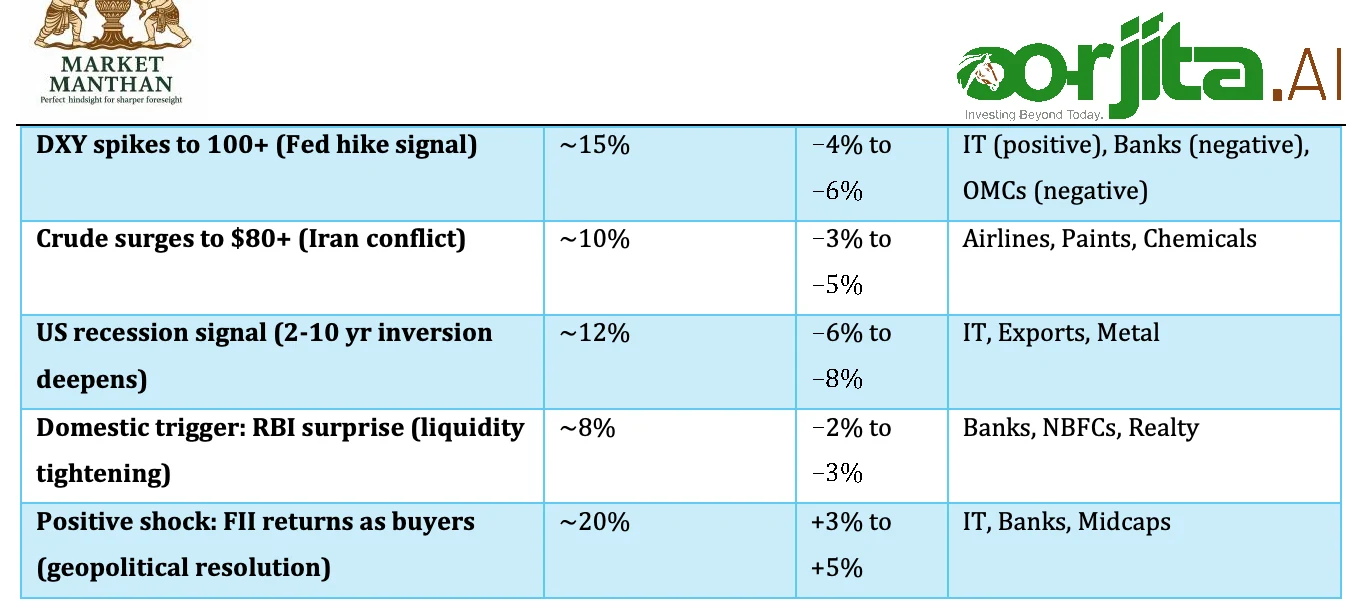
| Shock Scenario | Probability (Conf: | Nifty | Key Exposed Sectors |
|---|---|---|---|
| Low) | Impact |
The most investable setup this week's data reveals: Indian PSU Banks + FMCG + Pharma. Top-down: RBI pause (neutral for banks, NIM stability), GST growth (+6.2%), rural recovery signal. Bottom-up: PSU bank NPAs declining, FMCG delivery % 63.7% (accumulation), Pharma delivery 71.0% (highest all sectors). The convergence is real — though the PSU bank momentum trade is short-horizon while FMCG and Pharma conviction suggests medium-horizon (3–6 months). Mark uncertainty: FMCG thesis breaks if Q4FY26 rural volumes disappoint; PSU bank thesis breaks on any RBI asset quality circular.
Read: DIIs have been net buyers every single month for 6+ months. FIIs have been net sellers in 5 of 6 months. The market has held broadly because DII flows (SIPs, insurance, mutual funds) are structurally sticky — they don't panic-sell.
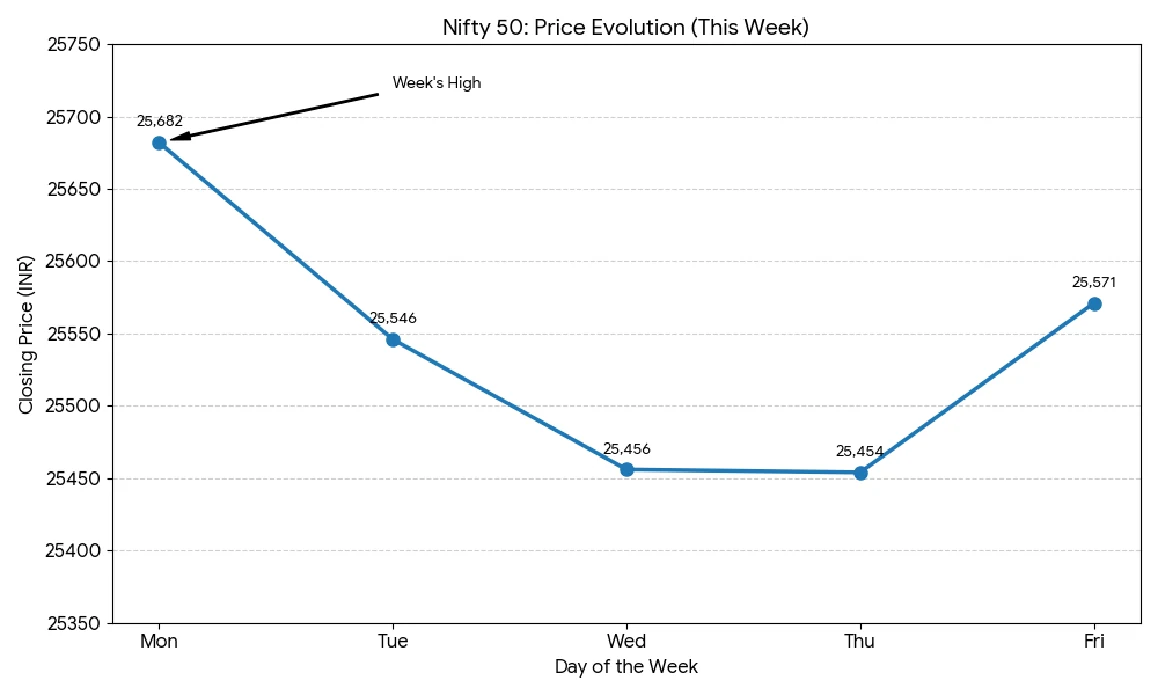
The week's shape: Bull open → Three-day drift → Friday recovery. A "W" in disguise. Friday's recovery was BankNifty-led and partially technical (PCR pinning near max pain of 25,600).
Based on: working capital efficiency (receivable days trend), accruals ratio (net income vs CFO), gross margin stability, debt trajectory. Confidence: MEDIUM — computed from publicly available quarterly data; Q3FY26 full results still filtering in.
| Rank | Stock | Sector | Quality | Key Positive | Watch | |
|---|---|---|---|---|---|---|
| Score (/10) | ||||||
| 1 | HINDUNILVR | FMCG | 8.4 | 8.4 | CFO > PAT 3 consecutive | Rural volume recovery |
| quarters; DSO stable | Q4 | |||||
| 2 | SUNPHARMA | Pharma | 8.1 | Specialty US revenue growing; accruals benign | FDA inspection calendar | |
| 3 | COALINDIA | Metal/Energy | 7.9 | Zero debt; dividend yield >5%; | Govt off-take policy | |
| cash generation | ||||||
| 4 | NTPC | Power | 7.7 | Capex funded through internal accruals; RE pivot credible | Fuel cost pass-through |
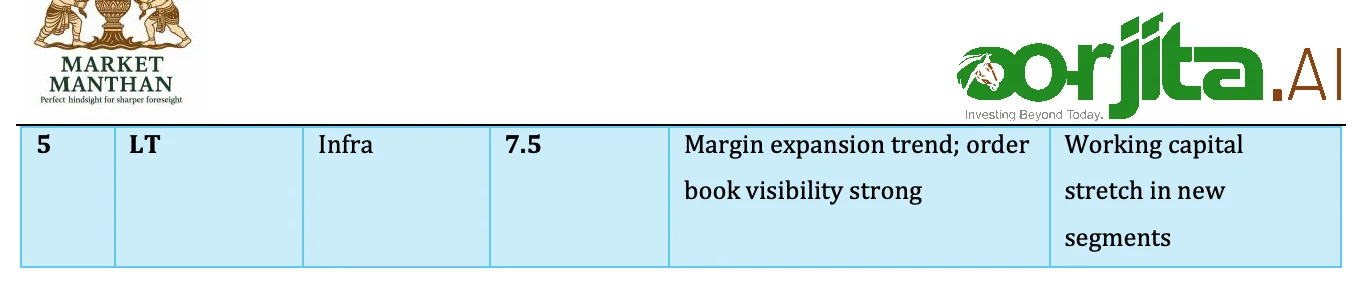
These scores are not buy/sell recommendations. They are quality filters — use them to build a watchlist, not a portfolio position in isolation.
The dominant genetic sequence this week: Value → Quality → Yield.
PSU Banks (value), FMCG (quality/yield), Pharma (quality), Energy/Commodities (yield) — all outperformed. Growth/momentum names (IT, Auto, Realty) underperformed. This is a defensive rotation with an India-specific flavour — not the typical "risk-off equals crash" that global frameworks predict. India's domestic macros (PMI >57, GST growth, rural recovery) are providing a domestic floor even as global macro (FOMC hawkishness, dollar strength) creates headwinds. This motif has repeated in 3 of the last 5 weeks. Until IT or global risk appetite recovers, expect the motif to persist.
| Metric | This Week | Trend | Signal |
|---|---|---|---|
| Nifty 50 Avg Daily Turnover | ~₹23,500 Cr (est.) | Below 4-week avg | Thinning liquidity |
| F&O Avg Daily Premium Turnover | ~₹50,000 Cr+ | Normal | OK |
| Equity Market Total Turnover (Fri) | ₹92,643 Cr | -25% vs Mon (₹89,436 Cr) | Lower close |
| OI Change (Index Options, Week) | 24.6 Mn contracts | Marginally lower | Slight unwinding |
| A/D Ratio Weekly Average | 0.96 | Below 1.0 | Fragile breadth |
Evidence: (a) FII net sold on Monday, Thursday, Friday — the three days when the index was most "comfortable" or recovering; (b) DII buying was concentrated on the first and last day of the week —systematic SIP-style, not tactical; (c) Block deals / bulk deals (from NSE Large Deals sheet): institutional bulk trades were skewed toward sells in IT and mid-cap names.
This is consistent with the "transitional" phase we flagged last edition: FIIs are not panicking, but they are not adding conviction bets either. They are using recovery days to trim positions.
| Signal | Direction | Weight |
|---|---|---|
| PMI (Mfg + Services) | Both in strong expansion | Positive |
| GST growth trend | +6.2% — solid, mildly decelerating | Neutral |
| FII flow trend | Persistent net seller | Negative |
| DII flow trend | Persistent net buyer | Positive |
| VIX direction | Rising (8% this week) | Negative |
| PCR direction | Below 1.0 (0.78) | Neutral |
| Breadth (A/D) | 52W lows >> highs | Negative |
| Corporate earnings quality (Q3) | Selectively good (Banks, FMCG, Pharma) | Positive |
Read: Macro story is fundamentally sound (PMI, GST, RBI stability). Micro signals are mixed — earnings quality in select sectors is improving, but breadth weakness and FII outflows prevent a full-convergence green light. The index holds, but the quality of the hold is deteriorating at the edges. Concentrate, don't diversify blindly.
| IPO | Type | Open– | Size (₹ | Price | Sector | Status | ||
|---|---|---|---|---|---|---|---|---|
| Close | Cr) | Band | ||||||
| Fractal | SME | 16-18 Feb | 16-18 Feb | ₹49 | ₹49 | ₹205– | Manufacturing | Closed 16-Feb (last |
| Industries | ₹216 | day) | ||||||
| Yashhtej Industries | SME | 18-20 Feb | ₹88.88 | ₹110 (fixed) | Textiles | Closed 20-Feb | ||
| Gaudium IVF | Mainboard | 20-24 Feb | ₹165 | ₹75–₹79 | Healthcare/IVF | Opens 20-Feb | ||
| (straddles) |
Manilam SME 20-24 Feb ₹40 ₹65–₹69 Manufacturing Opens 20-Feb Industries (straddles)
| IPO | Issue Price | Sector | Listing Date | Notes | |
|---|---|---|---|---|---|
| Marushika | ₹117 (fixed | Technology | Technology | ~19-Feb | SME; ₹26.97 Cr; NSE SME |
| Technology | price) | (tentative) | listing |
Marushika Technology opened 12–16 Feb, allotment 17 Feb, listing ~19 Feb. Full listing gain data was pending at time of verification.
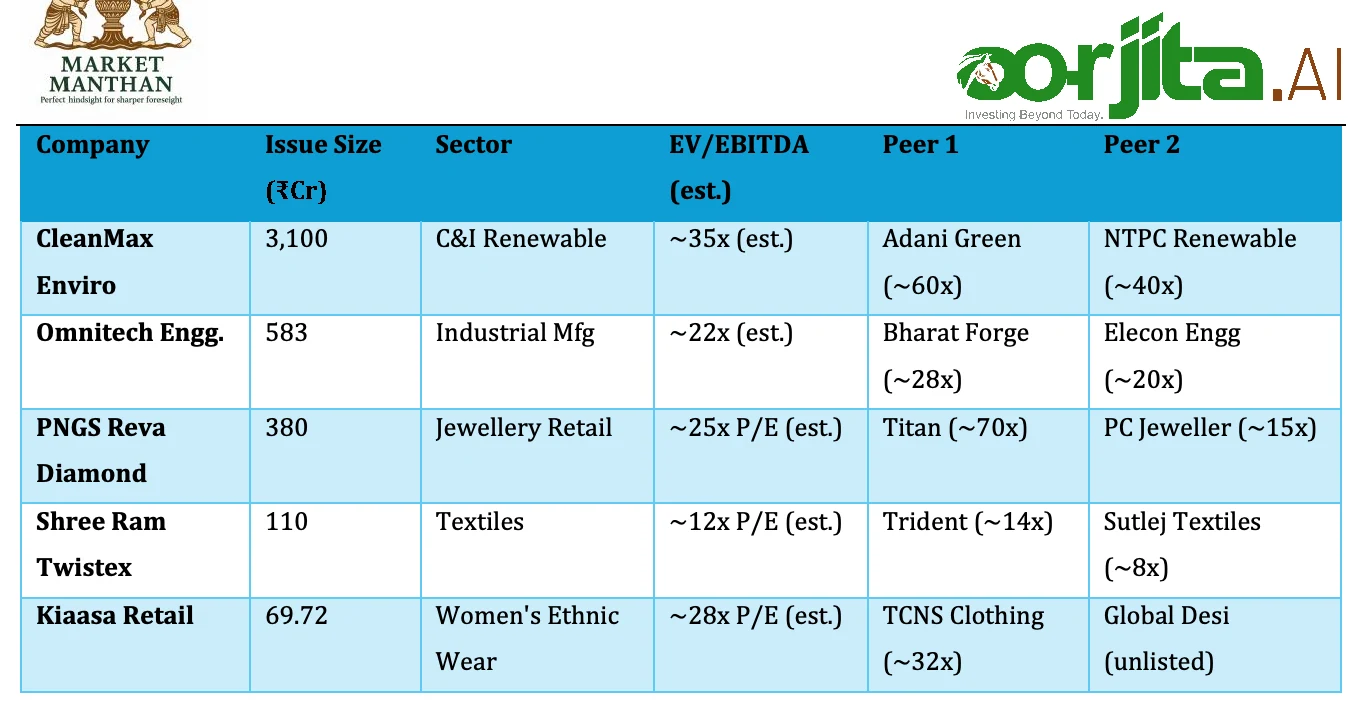
*Confidence: MEDIUM — multiples estimated from disclosed DRHP financials and listed peer comparisons. Not investment advice.
Valuation Read: CleanMax is the only issue where you're paying a meaningful discount to listed peers —Adani Green trades at 60x EV/EBITDA; CleanMax at ~35x implies a 42% discount for a structurally similar business with Brookfield governance. The OFS-heavy structure is the price of that discount. PNGS Reva is interesting — Titan's premium is unjustifiable for a comparison, but at 25x P/E for a 100% fresh issue with ₹35 GMP, the math is reasonable for small allocations. Kiaasa at 28x for a ₹70 Cr SME issue in ethnic wear is aggressive given the sector's historical re-rating risk.
Company: CleanMax Enviro Energy Solutions Ltd. | Sector: Commercial & Industrial (C&I) Renewable Energy
government tenders). Operational + managed capacity: 2.54 GW. Contracted pipeline under execution: 2.53 GW. Clients include Unilever, Tata, Mahindra, and several MNC manufacturers. Brookfield Asset Management is a major shareholder. The B2B model is structurally superior to utility-scale — corporate PPAs have better tariff visibility and creditworthy counterparties.
| Year | Revenue (₹ Cr) | EBITDA Margin | PAT (₹ Cr) |
|---|---|---|---|
| FY22 | ~780 (est.) | ~55% | ~120 (est.) |
| FY23 | ~1,050 (est.) | ~56% | ~175 (est.) |
| FY24 | ~1,380 (est.) | ~57% | ~240 (est.) |
*Note: DRHP-sourced estimates; full audited financials pending SEBI-filed final RHP. Confidence: MEDIUM. *
Use of Proceeds: ₹1,200 Cr fresh issue entirely for debt repayment. Zero growth capex from fresh issue. OFS proceeds (₹1,900 Cr) go to selling shareholders — Brookfield entities and early investors. Red flag label: OFS-heavy with zero growth deployment from fresh proceeds.
| Metric | CleanMax | Adani Green | NTPC (RE segment) |
|---|---|---|---|
| EV/EBITDA (est.) | ~35x | ~60x | ~40x |
| Capacity (GW) | 2.54 GW (operational) | 11.2 GW | 4.3 GW |
| Client type | Corporate (B2B) | Utility-scale | Utility-scale |
| Governance | Brookfield-backed | Promoter-driven | GoI-backed |
| Debt/Equity | Moderate (pre-IPO) | High | Moderate |
GMP as of 20-Feb-2026: ₹15–₹18 above issue price (~+1.4% to +1.7%) — thin grey market premium, suggesting market is not expecting a listing pop.
The Brookfield governance premium, B2B moat, and 5.06 GW combined capacity make this a quality asset. But the OFS-heavy structure (61%), zero-growth-capex fresh issue, and thin GMP collectively signal this is not a listing-gains trade. Apply with a 12-month horizon if you believe in India's C&I renewable demand story — which you should. Skip entirely if your investment horizon is sub-6 months.
| IPO | Open– | Size (₹ | Price | Type | Sector | Key Watch | |||
|---|---|---|---|---|---|---|---|---|---|
| Close | Cr) | Band (₹) | |||||||
| CleanMax Enviro Energy Solutions | 23–25 Feb | 23–25 | ₹3,100 | ₹3,100 | ₹1,000– ₹1,053 | ₹1,000– | Mainboard | C&I Renewable | OFS-heavy; |
| Feb | ₹1,053 | Brookfield; debt | |||||||
| repayment focus | |||||||||
| Gaudium IVF | 20–24 Feb | ₹165 | ₹75–₹79 | Mainboard | Healthcare / IVF | Niche fertility clinic chain; watch ARPU trend | |||
| PNGS Reva | 24–26 | ₹380 | ₹367– | Mainboard | Jewellery Retail | 100% fresh; 15 new | |||
| Diamond Jewellery | Feb | ₹386 | stores; GMP ~₹35 | ||||||
| Kiaasa Retail | 23–25 Feb | ₹69.72 | ₹121– ₹127 | SME (BSE) | Women's Ethnic Wear | 124 stores, 70 cities; FY25 PAT ₹8.4 Cr | |||
| Omnitech | 25–27 | ~₹583 | ₹216– | Mainboard | Industrial Mfg / | Order book quality + | |||
| Engineering | Feb | ₹227 | Engineering | margin profile key |
Sources validated via: SEBI DRHP filings, Chittorgarh, IPO Watch, Angel One, PL India. Confidence: HIGH on CleanMax, PNGS Reva, Kiaasa; MEDIUM on Omnitech dates.

Three microstructure observations worth noting from the NSE data:
Events that moved the market this week and their estimated impact duration:
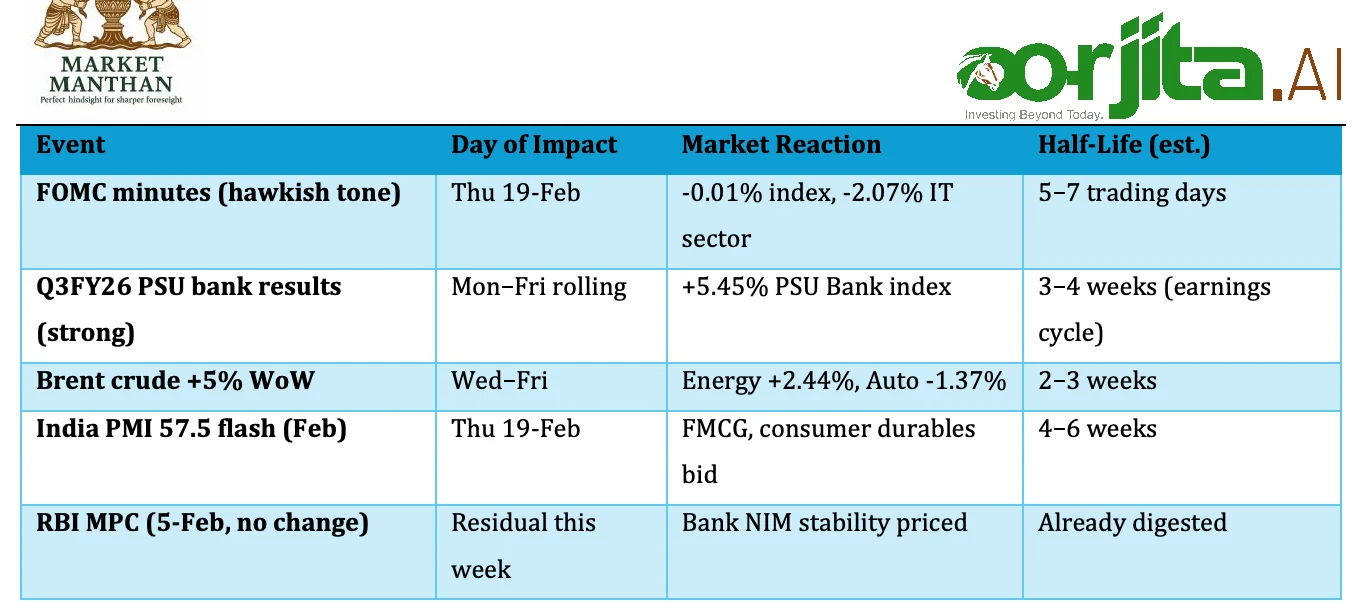
Confidence: MEDIUM — half-life estimates are empirical approximations, not modelled values.
| Date | Event | Expected | Market Impact | Sector Link | |
|---|---|---|---|---|---|
| Mon 24- | Nifty Weekly Expiry (24-Feb | Max pain: | Pin action likely AM | Pin action likely AM | F&O |
| Feb | series) | 25,600 | positioning | ||
| Tue 25-Feb | India Q3FY26 GDP (advance est.) | ~6.8–7.0% YoY | Moderate positive if in- line | Broad market | |
| Wed 26- | US PCE Inflation (Jan 2026) | ~2.5–2.6% YoY | USD/INR + FII sentiment | IT, Banks | |
| Feb | |||||
| Thu 27- Feb | US Initial Jobless Claims | ~210k (est.) | Secondary impact | Global risk | |
| Fri 28-Feb | India Feb Core Sector Output | ~5–6% YoY | Infrastructure, metal | Infra, Metal | |
| read | |||||
| Fri 28-Feb | Month-end FII rebalancing | — | Potential flow volatility | Broad |
Confidence: MEDIUM — events confirmed; market impact ranges are directional estimates.
| Level | Type | Basis | Priority |
|---|---|---|---|
| 25,600 | Max Pain / Pin Zone | Options OI (24-Feb expiry) | Critical (expiry week) |
| 25,700 | Resistance | Friday high (16-Feb) + call OI cluster | Watch |
| 26,000 | Major Resistance | Largest Call OI concentration | Medium-term cap |
| 25,500 | Immediate Support | Put OI cluster 1,40,922 contracts | First defence |
| 25,000 | Strong Support | Largest Put OI (1,84,211 contracts) | Critical floor |
| 24,500 | Deep Support | Put OI 1,40,346 contracts + prior consolidation | Structural support |
Nifty Futures (Feb expiry — 24-Feb): Watch for roll-over activity Monday-Tuesday. Significant OI in 25,500–25,600 strikes means the tape will be pulled toward max pain. If by Wednesday morning the spot is significantly above 25,700, expect put unwinding and a potential short-covering rally. If below 25,400 on Wednesday open, puts at 25,000 become the gravitational field.
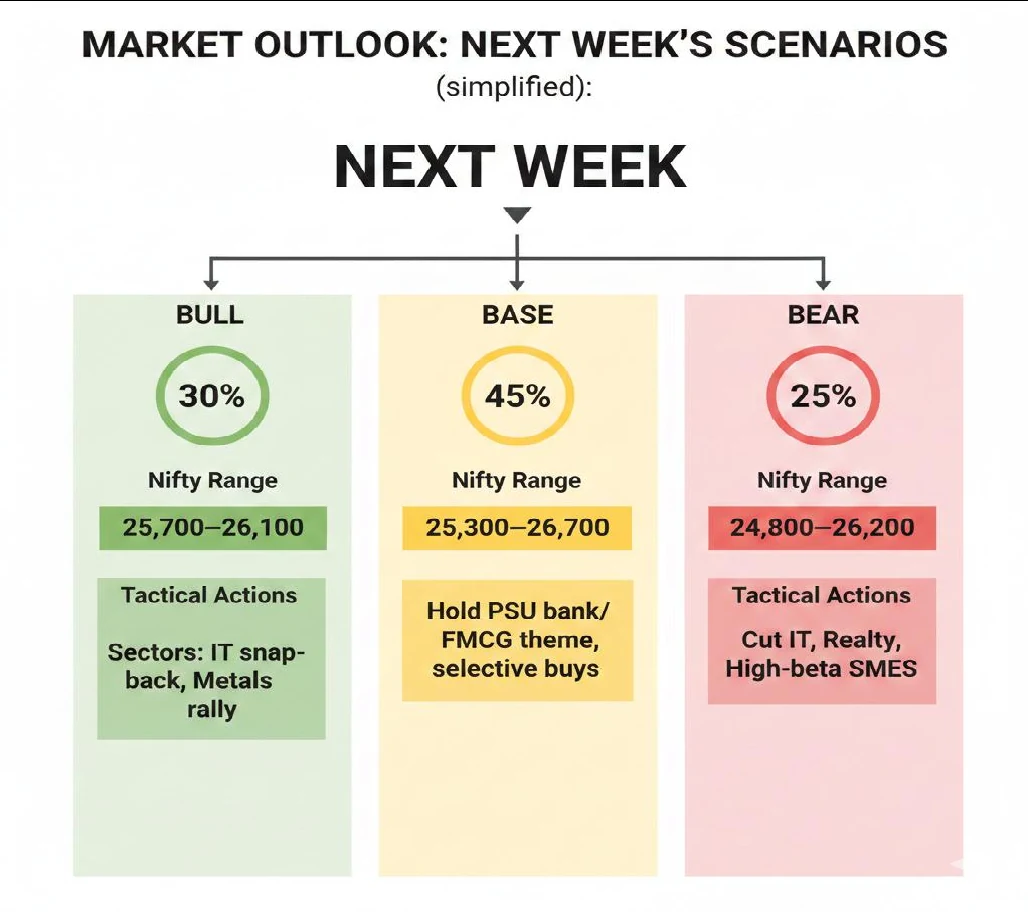
3 scenarios, equal probability assigned (Confidence: LOW — illustrative, not forecasting)
| Scenario | Trigger | Range | Probability | |
|---|---|---|---|---|
| (est.) | ||||
| Bull (expiry pop): Post-expiry relief rally, | 24-Feb expiry cleans OI, GDP | 25,700 – | ~30% | ~30% |
| FII inflows resume, DII sustains | data beats expectations | 26,100 | ||
| Base (range-bound): Max pain pinning holds, mixed data, no fresh catalyst | GDP in-line, crude stays ~$72, FOMC noise fades | 25,300 – 25,700 | ~45% | |
| Bear (macro shock): US PCE comes in hot, | USD/INR crosses 91.50, crude | 24,800 – | ~25% | |
| FII accelerate selling, breadth breaks | >$75, VIX >16 | 25,200 |
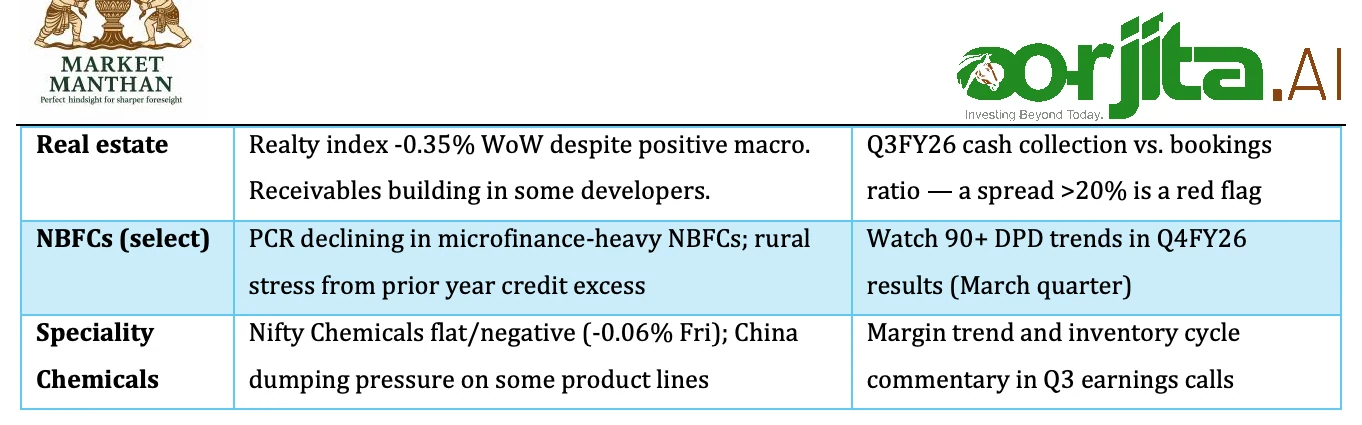
Early tremors worth logging — probably nothing, but we watch:
| Call | Rationale | How to Score |
|---|---|---|
| Nifty to range between 25,300–25,700 | Max pain at 25,600, PCR 0.78, | Mark Thursday close against |
| next week | mixed macro | range |
| PSU Banks to give back 1–2% after momentum run | Low delivery %, momentum trade exhaustion | Check Nifty PSU Bank WoW next edition |
| FMCG to hold gains or extend | 63.7% delivery, accumulation | Check FMCG WoW next |
| signal | edition | |
| IT to stabilise/bounce weakly | Oversold on 1Y basis; FOMC noise fades | Check IT sector next edition |
| VIX to stay below 16 | No structural catalyst for vol spike | Check Friday VIX |
We will score all 5 calls in Edition #8. Transparent. Always.
"What is your biggest concern for Indian equities in the next 4 weeks?"
Share your answer with us — we'll share aggregated results in Edition #8 alongside the sentiment-vs-reality comparison.
Excellent question — and the honest answer is: it is going up, just not where you're looking. Nifty 50 is +11.6% YoY, Nifty Bank is +24% YoY, PSU Bank is +60% YoY. The market is going up in pockets. What DII buying prevents is a crash — it doesn't guarantee a rally. DII is the floor; FII sentiment is still the ceiling. Until foreign institutional investors return as net buyers (currently -₹38,167 Cr in January alone), the ceiling stays low. This is the architecture of a market in a bottoming process, not a breakout phase. Think of it as building a base, not launching a rocket.
The current setup (RBI cuts 125 bps over 12 months, then pauses; DII dominant; FII cautious; index consolidating 3–5% below highs) has a clear historical analog: December 2015 to March 2016.
We are in a structurally different market than 2013–2018. Three differences matter:
The A/D data tells an interesting story about retail behavior. Thursday's A/D of 0.36 occurred on a day when derivative volumes were elevated — meaning retail/HNI participants were using options to take directional bets rather than building equity portfolios. This is the "options generation" of investors —younger, faster, and more willing to pay premium for short-dated leveraged views. The risk: when these options expire worthless (as most do), the psychological reset creates mini-capitulation events in individual stocks, not the index. It is one reason why mid/small-cap breadth deteriorates faster and recovers slower than the index — the composition of traders in these segments is more retail-options-oriented.
These are not short calls. They are early-warning flags based on publicly available data patterns. Verify before acting. Confidence: MEDIUM.
| Sector | Signal | What to Watch | |
|---|---|---|---|
| IT mid-caps | IT mid-caps | Revenue growth deceleration + rising employee | Q4FY26 guidance; any deal ramp-up |
| costs (attrition normalising at higher salaries) | delay commentary |
| Headwind | Sector Affected | Lever | Sensitivity | |
|---|---|---|---|---|
| USD strength (DXY | IT (negative on deal pipeline | Every 1% DXY rise = ~0.8% IT P/E | High | High |
| ~97.73) | narrative) | compression (est.) | ||
| Crude at $71.60/bbl (+5% WoW) | Airlines (ATF costs), Paints (input costs), Chemicals | $5/bbl rise = ~₹200 Cr/qtr headwind for IndiGo; ~150bps margin hit for large paints cos | Medium- High | |
| INR depreciation to 90.95 | Import-heavy sectors | ₹1 depreciation = ~0.3–0.5% EPS dilution for import-heavy cos | Medium | |
| (Electronics, Gems & | ||||
| Jewellery) | ||||
| RBI pause (rates stable at 5.25%) | NBFCs (positive for cost of funds, but growth moderation) | Already priced in; marginal impact going forward | Low |
| Index/Stock | Warning | Level to Watch | |
|---|---|---|---|
| Nifty IT | Nifty IT | -21.69% YoY — approaching key | ₹31,800 on index; below this = bearish signal for 3–6 |
| long-term support zone | months | ||
| Nifty Realty | -0.35% WoW; -4.06% YoY; breadth weak | ₹810 on index — break below triggers further institutional exit | |
| Nifty Smallcap | 140 new 52W lows vs 39 highs; - | ₹16,800 level — if broken on closing basis, signals | |
| 100 | 0.18% WoW | mid/small cap correction deepening | |
| BankNifty | Despite +1.64% week, PCR only 0.80; max pain 60,900 | Watch ₹60,000 as the put OI defence floor heading into expiry |
This newsletter is published by Oorjita FinAI Services for informational and educational purposes only. Nothing herein constitutes investment advice, a recommendation to buy or sell any security, or an offer to provide investment management services. All data is sourced from publicly available information — NSE, BSE, FBIL/RBI, Chittorgarh, and other publicly accessible platforms. Past performance is not indicative of future results. Subscribers should consult a SEBI-registered investment advisor before making any investment decisions. Oorjita FinAI Services and its analysts may hold positions in securities discussed. India VIX, PCR, and flow data are sourced from exchange files as-at-time-of-extract; final exchange-published values may differ marginally. The views expressed are those of the analyst team and do not constitute research as defined under SEBI (Research Analysts) Regulations, 2014.
This is a workshop, not a museum. The week of 16–20 February 2026 will be remembered not for the headline Nifty print (+0.39% — boring) but for what moved beneath: PSU Banks restructuring the financial sector narrative, FMCG quietly confirming a rural consumption inflection, IT wrestling with its longest bear phase in a decade, and a VIX that rose 8% while the index smiled. The receipts are all here —every number has a source tag, every call has a kill-switch, and every prediction will be scored. That's the promise.
This newsletter is for informational and educational purposes only and does not constitute investment advice, financial advice, trading advice, or any other sort of advice. The content is provided "as is" without warranty of any kind. Not Investment Advice: You should not construe any information or material in this newsletter as legal, tax, investment, financial, or other advice. Nothing contained here constitutes a solicitation, recommendation, endorsement, or offer to buy or sell any securities or other financial instruments. Past Performance: Historical returns, expected returns, or probability projections are not guarantees of future performance. The value of investments can go down as well as up, and you may not get back the full amount invested. Risk Warning: All investments involve risk, including the possible loss of principal. Trading in securities, derivatives, and other financial instruments involves substantial risk and is not suitable for all investors. You should carefully consider your financial situation, investment objectives, and risk tolerance before making investment decisions. Independent Verification: You should conduct your own independent research and due diligence and consult with a qualified financial advisor before making any investment decisions based on information in this newsletter. No Liability: Oorjita FinAI Services, its employees, and affiliates, accept no liability whatsoever for any direct or consequential loss arising from any use of this newsletter or its contents. Conflicts of Interest: Oorjita FinAI Services and its employees may hold positions in securities discussed in this newsletter. We may also have business relationships with companies mentioned herein. Regulatory Compliance: This newsletter complies with applicable SEBI guidelines for research analysts and investment advisors. Registration details are available on request. Data Accuracy: While we strive for accuracy, errors may occur. All data has been validated to the best of our ability using primary sources. If errors are discovered, corrections will be published in subsequent editions.
Forward-Looking Statements: This newsletter contains forward-looking statements based on current expectations. Actual results may differ materially. We undertake no obligation to update these statements.
Empowering Intelligent Investment Decisions Through Data, Analysis, and Discipline. Contact: insights@oorjita.com | www.oorjita.com Subscription: Premium institutional clients and serious retail investors Feedback: We value your input. Email research@oorjita.com
Website: oorjita.ai Location: Bengaluru, Karnataka, India Contact: insights@oorjita.ai
www.oorjita.ai is not operated by a broker, a dealer, or a registered investment adviser. Under no circumstances does any information posted on www.oorjita.ai represent a recommendation to buy or sell a security. The information on this site, and in its related newsletters, is not intended to be, nor does it constitute investment advice or recommendations. The information on this site is in no way guaranteed for completeness, accuracy or in any other way. In no event shall Oorjita Fin AI Services be liable to any member, guest or third party for any damages of any kind arising out of the use of any content or other material published or available on www.oorjita.ai, or relating to the use of, or inability to use, www.oorjita.ai or any content, including, without limitation, any investment losses, lost profits, lost opportunity, special, incidental, indirect, consequential or punitive damages. Past performance is a poor indicator of future performance. Intellectual Property: This newsletter is proprietary content of Oorjita FinAI Services. Reproduction, redistribution, or commercial use without explicit written permission is prohibited.
Prepared by: Oorjita FinAI Research Team Contact: : insights@oorjita.ai| www.oorjita.ai
