Indian markets are poised for a cautious start this Friday as GIFT Nifty futures signal muted opening amid weak global cues and ongoing U.S. government shutdown entering its ninth day.

India (Thu close): Nifty 25,182 (+0.54%), Sensex 82,172 (+0.49%); broad green with IT/Metals firm ahead of TCS.
Actionable Trigger: Monitor India's semiconductor policy updates and Google's data centre timeline announcements for sectoral plays in IT infrastructure and real estate; watch for IT sector earnings guidance for Q3 demand outlook.
Ceasefire Impact on Oil: Reports of an Israel-Hamas ceasefire pushed crude oil lower, with Brent crude trading at $65.52/barrel (forecast decline toward $62.55) as geopolitical risk premium eased, improving risk appetite across Asian equities.
Investor Takeaway: Space tech represents a high-risk, high-reward bet with long gestation periods; however, government contracts, defense applications, and satellite broadband (competing with Starlink) offer near-term revenue visibility.
Indian markets are poised for a cautious start this Friday as GIFT Nifty futures signal muted opening amid weak global cues and ongoing U.S. government shutdown entering its ninth day. Benchmark indices staged a sharp recovery on Thursday, with Nifty closing near 25,200 and Sensex gaining 398 points, led by broad-based buying across pharma, metals, PSU banks, and IT sectors. What's different today? Focus shifts to quarterly earnings reactions, particularly TCS which beat revenue estimates, while investors navigate the absence of U.S. economic data due to the federal shutdown. Key watch factors include Q2 earnings momentum, global rate cut expectations (94.6% probability of 25 bps Fed cut on Oct 28-29), and sectoral rotation into defensives.
India (Thu close): Nifty 25,182 (+0.54%), Sensex 82,172 (+0.49%); broad green with IT/Metals firm ahead of TCS.
Overnight: Wall St slipped into earnings; Asia mixed this morning; gold cooled from fresh records; Brent steady ~65–66. Net read-through: risk tone softer but orderly.
Today’s setup (08:10 IST): GIFT Nifty ~25,241 (-0.1%) telegraphs a muted/flat start.
Google's $10 Billion India Bet: Google announced plans to build Asia's largest data centre cluster in Visakhapatnam, Andhra Pradesh, marking one of the biggest tech infrastructure investments in India's AI and cloud computing push. The move underscores global tech giants' commitment to India's digital infrastructure backbone.
Karnataka Space Tech Leadership: Karnataka signed a memorandum with the Indian Space Research Organisation (ISRO) to establish India's first state-level Centre of Excellence in Space Technology, positioning Bengaluru as the epicentre of the country's NewSpace revolution. The initiative aims to accelerate private sector participation in satellite technology and launch services.
Google Pixel 10 Pro Fold Launch: Google commenced sales of its Pixel 10 Pro Fold (₹1,72,999) and Pixel Buds 2a (₹12,999) in India, with the foldable flagship offering HDFC Bank cashback up to ₹13,000. Separately, Google rolled out its AI-powered Search Live feature in India (English and Hindi), marking its first expansion outside the U.S. for real-time voice-based conversational search.
India's startup ecosystem continues its selective funding trajectory in 2025, with year-to-date funding reaching an estimated $11-12 billion across ~800 deals through September, reflecting cautious optimism post-2024's recovery. Fintech dominates capital allocation, with H1 2025 seeing $1.6 billion deployed (+56% YoY), driven by credit, wealthtech, and embedded finance models. AI emerges as H2's breakout theme, with generative AI, SaaS productivity tools, and applied AI in logistics and healthcare attracting significant late-stage capital. E-commerce logged 109 deals in H1 2025 with deal activity leading all sectors despite valuation compression in consumer tech.
Thursday's Top Performers: HCL Technologies, JSW Steel, and Tata Steel led Nifty gains, while SBI Life Insurance and InterGlobe Aviation added to the momentum as sectoral indices closed in the green—pharma, oil & gas, realty, metals, and PSU banks rose 0.5-1%. Laggards included Tata Consumer, Axis Bank, Maruti Suzuki, Titan Company, and Bharti Airtel.
TCS Post-Earnings Watch: TCS reported Q2FY26 revenue of ₹65,799 crore (beat estimates of ₹65,069 crore), up 3.7% QoQ, with operating margin expanding 70 bps to 25.2%. PAT stood at ₹12,075 crore, up 1.4% YoY but below estimates of ₹12,573 crore. The IT major declared an interim dividend of ₹11 per share (record date: Oct 15, payment: Nov 4) and reported robust TCV of $10 billion, signaling steady demand in BFSI (+1.1% QoQ CC) and Technology Services (+1.8% QoQ CC). Actionable levels: Watch for TCS share price reaction above ₹3,066 for continuation; defensive IT plays remain attractive amid global rate cut optimism.
Sectoral Heatmap: BSE Midcap Index outperformed with +0.75% gains, while Smallcap Index ended flat, reflecting selective buying amid valuation concerns.
Ceasefire Impact on Oil: Reports of an Israel-Hamas ceasefire pushed crude oil lower, with Brent crude trading at $65.52/barrel (forecast decline toward $62.55) as geopolitical risk premium eased, improving risk appetite across Asian equities. Gold retreated below $4,000 after hitting record highs, with profit-taking evident as the precious metal closed at $3,950-$4,000 range.
U.S. Shutdown Enters Day 9: The Senate failed for the seventh time to approve temporary funding, delaying critical economic data releases including jobless claims, leaving investors reliant on Fed commentary and earnings for direction. New York Fed President John Williams advocated for additional rate cuts before year-end, supporting market expectations of 25 bps reduction on Oct 28-29 (94.6% probability per CME FedWatch).
Asian Market Divergence: South Korea's Kospi surged 1.81% after reopening from holidays, while China's CSI 300 fell 1.08%, Hong Kong's Hang Seng dropped 0.85%, and Japan's Nikkei slipped 0.63% in early Friday trade, tracking Wall Street's consolidation.
Gold’s quick slip under $4k after a record run may ease hedging intensity, allowing cyclicals (metals/industrials) a bit of oxygen — provided oil stays near $65 and USD doesn’t lurch higher. Keep barbell: quality IT + selective domestic cyclicals; fade at resistance if volumes don’t confirm.
India's space technology sector is witnessing a transformative shift with Karnataka's pioneering establishment of a state-level Centre of Excellence in partnership with ISRO, signaling aggressive subnational competition to attract NewSpace startups. The move comes as India's space economy is projected to grow from $8.4 billion (2023) to $44 billion by 2033, with private sector participation accounting for an estimated 15-20% share by 2030.
Policy Tailwinds: The Indian government's 2020 space sector reforms opened satellite launches, ground infrastructure, and space-based services to private players, catalyzing over 150 registered space startups as of 2025. Karnataka's move builds on this momentum by offering co-development infrastructure, testing facilities, and regulatory sandboxes for satellite manufacturing and launch vehicle innovation.
Peer Comparison: While the U.S. space economy ($469 billion, 2024) and China ($178 billion) dwarf India's current scale, India's cost advantage (launch costs 60-70% lower than global averages) positions it as a competitive player in small satellite and rideshare launch markets. Domestic players like Skyroot Aerospace, Agnikul Cosmos, and Pixxel are competing for a share of the $500 billion global space economy projected by 2030.
Earnings Calendar: Elecon Engineering, Indosolar, Waaree Renewable Technologies, Yash Highvoltage, and GK Energy report Q2 results; post-earnings reactions for TCS and Tata Elxsi remain in focus.
IPO Activity: Canara HSBC Life Insurance opens for subscription; WeWork India Management lists; LG Electronics India allotment basis to be finalized. SME IPOs SK Minerals & Additives and Sihora Industries open, while NSB BPO Solutions lists.
Global Cues: U.S. markets remain data-starved due to shutdown; Fed speakers and Q3 earnings (PepsiCo, Delta already reported) will drive sentiment. Asian markets track Wall Street consolidation, with key levels at Nifty 25,200 (resistance) and 24,900 (support).
Macro Events: No major domestic data releases; global focus on Fed rate cut timeline and U.S. shutdown resolution progress.
"The quarter also saw a robust Total Contract Value (TCV) of US$10 billion... TCS continued to strengthen its global client relationships through expanded strategic partnerships." — TCS Management Commentary, Q2FY26 Earnings (October 9, 2025)
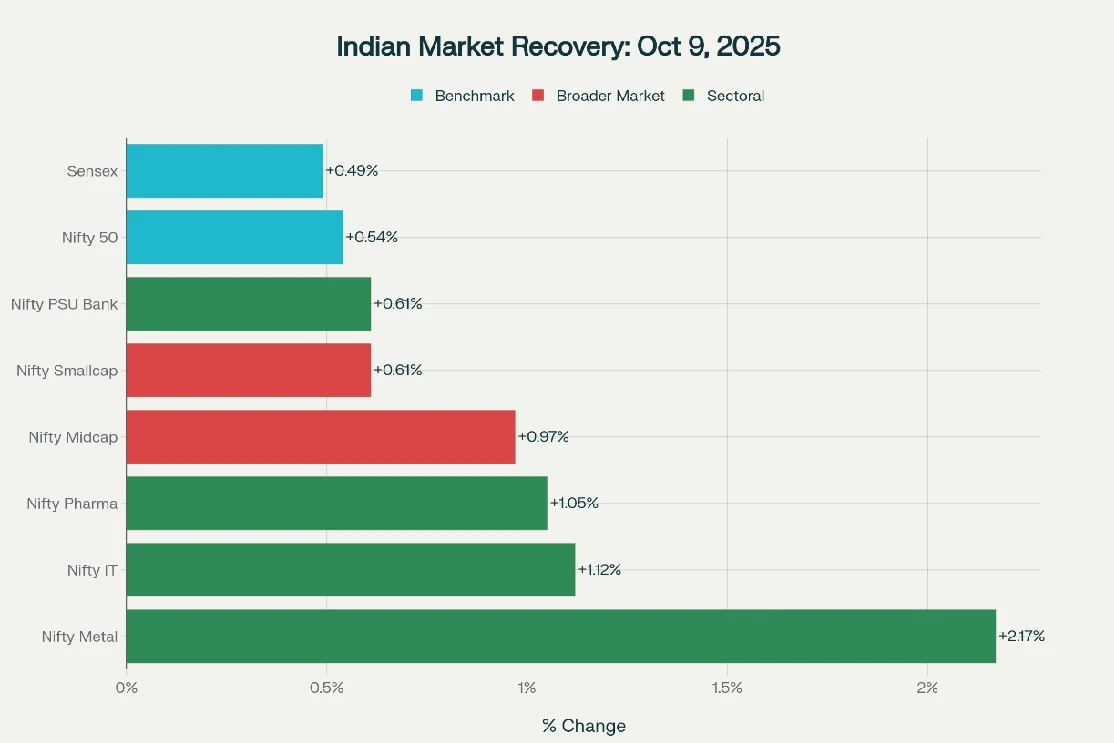
Note: Broad-based recovery with sectoral rotation into pharma, metals, PSU banks, and IT; Midcap outperformance signals risk-on sentiment.
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple verified platforms and cross-validated as per our editorial standards. Investors should conduct independent research and consult financial advisors before making investment decisions. Oorjita FinAI Services is not liable for any investment decisions based on this content. Markets are subject to volatility and past performance does not guarantee future results.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Friday, 10 October 2025, 8:16 AM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

1 advancing sector vs. 8 declining sectors Market Breadth: Negative (11% advance rate) Interpretation: Risk-off week; only financials held ground

Indian equity markets extended losses for the second consecutive session on Thursday, February 13, 2026, with benchmark indices closing sharply lower amid broad-based selling pressure.
