Indian markets are poised for a positive opening on Wednesday after shrugging off Wall Street's mixed close, with GIFT Nifty futures trading 68 points higher at 25,274 as of 6:40 AM.

Key watch factors today: Euro Area industrial production data, India's trade and unemployment data, passenger vehicle sales figures, and Q2 earnings from Axis Bank, HDFC Life, HDFC AMC, and Angel One.
WeWork India: The co-working space provider's IPO is currently open but has seen more muted demand compared to its peers.
Trade War 2.0: China imposed sanctions on five US-linked subsidiaries of South Korea's Hanwha Ocean, preventing Chinese entities from doing business with them.
Playbook: Barbell: quality lenders + steady-EoD IT; fade froth in illiquid beta until gold cools or trade rhetoric de-escalates.
Indian markets are poised for a positive opening on Wednesday after shrugging off Wall Street's mixed close, with GIFT Nifty futures trading 68 points higher at 25,274 as of 6:40 AM. Asian markets defied overnight US weakness, with Japan's Nikkei rising 0.3%, South Korea's Kospi up 0.8%, and Australia's S&P/ASX 200 gaining 0.93%. The rebound comes despite escalating US-China trade tensions after President Trump threatened "retribution" against China, including a potential cooking oil embargo.
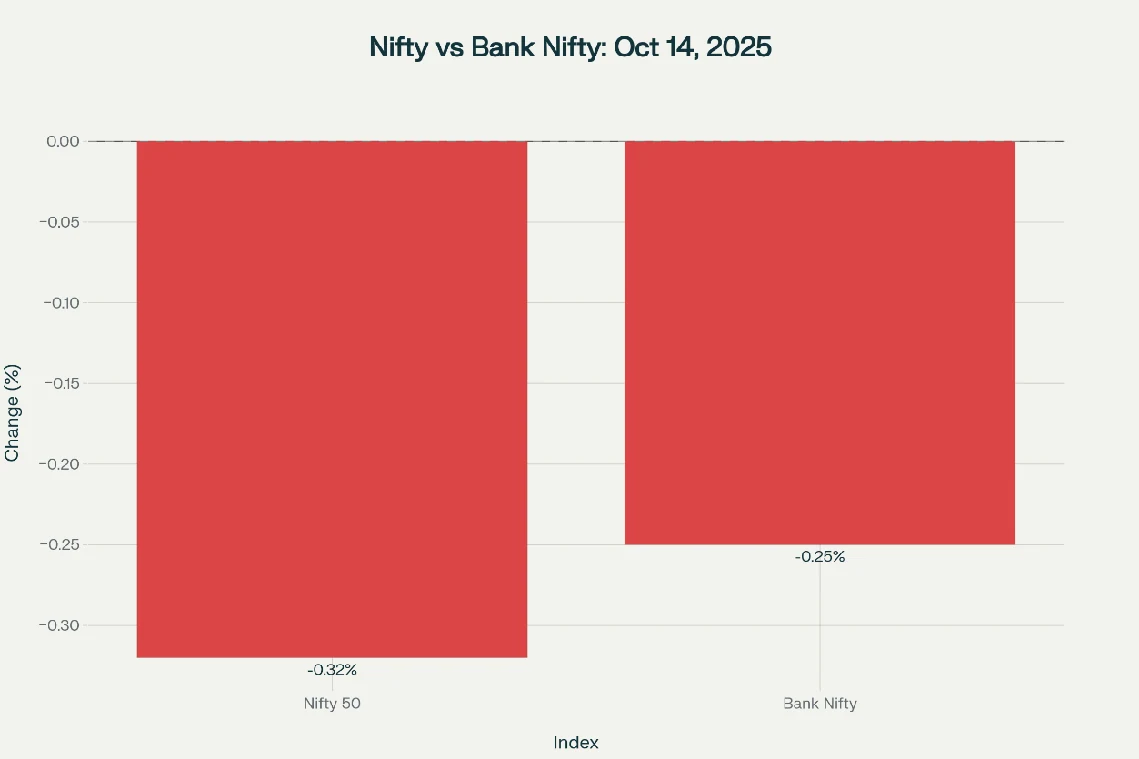
Domestic indices faced broad-based selling on Tuesday, with the Sensex closing at 82,029.98 (down 297.07 points, -0.36%) and the Nifty settling at 25,145.50 (down 81.85 points, -0.32%). All sectoral indices ended in the red, led by Nifty PSU Bank which plunged 1.52%, followed by Consumer Durables, Media, and Pharma. Bank Nifty closed at 56,598.65.
Key watch factors today: Euro Area industrial production data, India's trade and unemployment data, passenger vehicle sales figures, and Q2 earnings from Axis Bank, HDFC Life, HDFC AMC, and Angel One.
RBI posture around 88.8 on USD/INR; U.S.–China tariff rhetoric; earnings beats/misses in IT/financials.
What’s different today? Energy input costs ease (Brent at five-month lows) while the safety bid in gold persists—a mix that can Favor quality domestic cyclicals but cap high-beta rallies.
Google's Mega AI Investment: Alphabet's Google announced a landmark $15 billion investment to build India's first AI-focused data center hub in Visakhapatnam, Andhra Pradesh, marking the company's largest infrastructure commitment outside the United States. Google Cloud CEO Thomas Kurian confirmed the project will create significant AI data center capacity in Southern India, strengthening the nation's digital infrastructure. This strategic move positions India as a critical node in global AI development and could trigger increased FDI flows into India's tech sector.
Artha Venture Fund Milestone: Artha India Ventures (AIV) secured the first close of ₹250 crore for its Artha Venture Fund II (AVF II), targeting a total fund size of ₹500 crore. The micro-VC fund will invest in 36 seed-stage startups across premium consumption, fintech infrastructure, applied AI, and deep tech themes. This marks the family office's second micro-VC fund, signaling sustained appetite for early-stage venture capital despite broader market volatility.
Weekly Funding Snapshot: Indian startups raised $284.5 million across 26 deals in the week ending October 10, up 78% from the previous week, with fintech seeing the highest weekly funding at $146.5 million. Dhan became India's sixth unicorn of 2025, raising $120 million at a $1.2 billion valuation. The AI sector recorded the most deals with six startups collectively raising $24.5 million.
WeWork India: The co-working space provider's IPO is currently open but has seen more muted demand compared to its peers.
RBL Bank rallied on chatter of Emirates NBD stake talks (preferential allotment/warrants up to ~25% discussed). Use as sector governance read-through for private banks; no official filing yet.
Top Losers (Oct 14): Dr. Reddy's Laboratories, Bajaj Finance, Bharat Electronics, TCS, and Trent led the decline, each shedding 1.5-2%. Tata Steel and BEL were among the worst-hit large-caps amid metal and defense sector weakness.
Top Gainers (Oct 14): Healthcare emerged as a relative outperformer with Max Healthcare and Apollo Hospitals leading gains, while Tech Mahindra, Wipro, and ICICI Bank also closed in the green.
Broader Markets: The Nifty MidCap 100 index fell 0.75% and the Nifty SmallCap 100 slipped 0.89%, underperforming benchmark indices. Market breadth was weak with 2,692 shares declining against only 1,140 advances.
Actionable Watch Levels: Nifty support at 25,100; resistance at 25,300. Bank Nifty support near 56,500; watch for bounce toward 56,800 if global cues remain supportive.
Wall Street's Mixed Close: US markets ended mixed on Tuesday as strong bank earnings collided with renewed US-China trade frictions. The Dow Jones rose 0.44% to 46,270.46, while the S&P 500 dipped 0.16% to 6,644.31 and the Nasdaq fell 0.76% to 22,521.70. JPMorgan Chase, Goldman Sachs, and Wells Fargo beat third-quarter expectations, but tech stocks led declines with Nvidia falling over 3%.
Trade War 2.0: China imposed sanctions on five US-linked subsidiaries of South Korea's Hanwha Ocean, preventing Chinese entities from doing business with them. The VIX "fear gauge" spiked above 22, hitting a four-month high as investors priced in escalating geopolitical risks.
Safe-Haven Surge: Gold prices rallied to near-record highs of $4,179.79, with spot gold trading at $4,162.98/oz (up 0.5%), driven by safe-haven demand amid trade tensions and Fed rate cut speculation. In India, 24-karat gold touched ₹1,28,360 per 10 grams ahead of Dhanteras.
Oil Under Pressure: Crude oil prices declined amid demand concerns, with Brent crude falling to $62.31/barrel (down 0.16%) and WTI crude at $58.64/barrel (down 0.10%).
The resurgence of US-China trade hostilities presents both risks and opportunities for Indian markets. President Trump's threats of "retribution" against China, including potential cooking oil embargoes and expanded tariffs, have rattled global risk sentiment. Treasury Secretary Scott Bessent's comments that China is "attempting to pull everyone else down" underscore the severity of the standoff.
India's Positioning: Historically, US-China trade conflicts have benefited India through supply chain diversification. Google's $15 billion AI hub investment in Visakhapatnam exemplifies this "China+1" strategy. Sectors like pharmaceuticals, textiles, electronics manufacturing, and IT services stand to gain as global companies seek alternative sourcing destinations.
Validated Statistics: India's merchandise exports to the US grew 12% year-over-year in recent quarters, while Chinese exports faced tariff headwinds. Indian pharma companies already supply 40% of US generic drug demand, positioning them to capture additional market share if China-US tensions escalate further.
Earnings Calendar: Axis Bank, HDFC Life Insurance, HDFC Asset Management Company, HDB Financial Services, Angel One, Tata Communications, Delta Corp, Indian Railway Finance Corporation announce Q2FY26 results.
IPO Activity: Midwest IPO opens for subscription (price band ₹1,014-₹1,065); allotment for Canara HSBC Life Insurance IPO finalizes today.
Macro Data: India trade balance, unemployment rate, and passenger vehicle sales data; Euro Area industrial production numbers.
FII/DII Flows: After FIIs sold ₹1,059.41 crore and DIIs bought ₹3,024.10 crore on Tuesday, watch for continuation of domestic support.
Global Triggers: Fed Chair Powell's commentary on rate trajectory; any escalation in US-China trade rhetoric.
"In investing, what is comfortable is rarely profitable." – Robert Arnott
Nifty 50: 25,145.50 (-0.32%) | Bank Nifty: 56,598.65 (-0.25% approx) Both indices closed lower with Bank Nifty showing relative resilience despite PSU Bank index plunging 1.52%.
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple verified platforms and cross-validated as per our editorial standards. Investors should conduct independent research and consult financial advisors before making investment decisions. Oorjita FinAI Services is not liable for any investment decisions based on this content. Markets are subject to volatility and past performance does not guarantee future results.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Wednesday, 15 October 2025, 7:54 AM IST.

FIIs bought ₹45,960.02 cr of Indian equities this week — 615.28% above their 4-week average of -₹8,919.37 cr. Nifty rose 8.58% and closed at its weekly high, back above both its 25-week and 200-day averages. It did this while the S&P 500 fell 2.68%, the Nikkei 9.25% and Brent 16.42%.

All four layers aligned bearish. A/D = capitulation breadth.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.
