Foreign institutional investors turned net buyers after recent selling, purchasing ₹161.84 crore worth of shares, while DIIs remained aggressive with net buying of ₹4,492.26 crore on October 15.

What's different today?: GIFT Nifty futures signal a positive opening at 25,447-25,464, up 40-45 points, suggesting momentum continuation toward the crucial 25,500 resistance level.
PropTech Major HouseEazy Secures ₹150 Crore: Real estate technology platform HouseEazy raised ₹150 crore in Series B funding led by Accel, Chiratae Ventures, and Antler to expand its property transaction platform and enhance technology capabilities.
Actionable levels: Nifty finds crucial support at 25,200 with next resistance at 25,500, where a breakout could trigger momentum toward the September swing high of 24,400-24,500.
Earnings Calendar: Infosys (post-market), Wipro (post-market), LTIMindtree, Nestle India, Eternal, Jio Financial Services, Waaree Energies, JSW Infrastructure, Metro Brands, Indian Bank.
Indian markets snapped a two-day losing streak with broad-based buying on Wednesday, as the Nifty 50 surged 0.71% to close at 25,323.55 and the Sensex gained 0.70% to settle at 82,605.43. The rally was driven by dovish signals from Fed Chair Jerome Powell regarding interest rate pauses and strong US bank earnings that lifted global sentiment. Realty, Power, and PSU Bank sectors led the charge with gains of 1-3%, while broader indices showed renewed strength with Midcap 100 advancing 1.11% and Smallcap 100 gaining 0.82%.
US Chip Rally Boosts Tech Sentiment: US chipmakers surged in overnight trading after ASML exceeded third-quarter expectations for orders and operating income, with ASML's US-listed shares jumping 4.4%. Broadcom, Intel, and AMD posted strong gains, propelling the Nasdaq up 0.66%, signaling positive spillover effects for Indian semiconductor and tech stocks.
BlackRock's $40 Billion Data Center Play: A consortium led by BlackRock announced plans to acquire a major privately-owned data center operator for $40 billion (including debt), underscoring massive institutional investment flowing into AI infrastructure. This validates the secular growth trend in data center demand driven by AI adoption, benefiting Indian IT services providers with cloud and infrastructure practices.
PropTech Major HouseEazy Secures ₹150 Crore: Real estate technology platform HouseEazy raised ₹150 crore in Series B funding led by Accel, Chiratae Ventures, and Antler to expand its property transaction platform and enhance technology capabilities. This marks one of the largest PropTech deals in recent weeks, indicating investor confidence in India's digitizing real estate sector.
EdTech Platform SpeakX Raises $16 Million: AI-based language learning platform SpeakX secured $16 million in Series B funding from WestBridge Capital and Elevation Capital, highlighting continued investor appetite for education technology despite sector consolidation. The funding will support product development and market expansion in the growing English learning segment.
Agritech Funding Momentum: Two Brothers Organic Farms raised ₹110 crore in Series B from 360 One Asset and Rainmatter Investments, while drone logistics startup Airbound secured $8.65 million in seed funding from Lachy Groom, Humba Ventures, and Lightspeed. The diverse sectoral spread—from organic foods to drone delivery—demonstrates robust early-stage capital deployment across multiple high-growth verticals.
Banking Sector Mixed on Earnings: Axis Bank shares will be in focus after reporting a 26% decline in Q2 net profit to ₹5,090 crore, impacted by a one-time standard asset provision of ₹1,231 crore following RBI's FY25 inspection advisory. Despite the provisions, management expressed optimism about recent GST cuts and CRR reductions flowing through the banking system, with positive signs emerging in retail disbursements. HDB Financial Services reported a marginal 2% profit decline to ₹581 crore, though its gross loan book grew 13% YoY to ₹1.11 lakh crore.
Sectoral Heatmap: Realty stocks surged 3% on Wednesday, followed by Power (+2%), Consumer Durables (+1-2%), PSU Banks (+1-2%), Metals (+1-2%), and Telecom (+1-2%). Media was the only sector to close in the red. Today's watchlist includes Infosys, Wipro, LTIMindtree, Nestle India, Jio Financial Services, Waaree Energies, JSW Infrastructure, and Metro Brands announcing Q2FY26 results.
Actionable levels: Nifty finds crucial support at 25,200 with next resistance at 25,500, where a breakout could trigger momentum toward the September swing high of 24,400-24,500. Traders should watch for healthy momentum indicators and the continuation of the higher high-higher low formation.
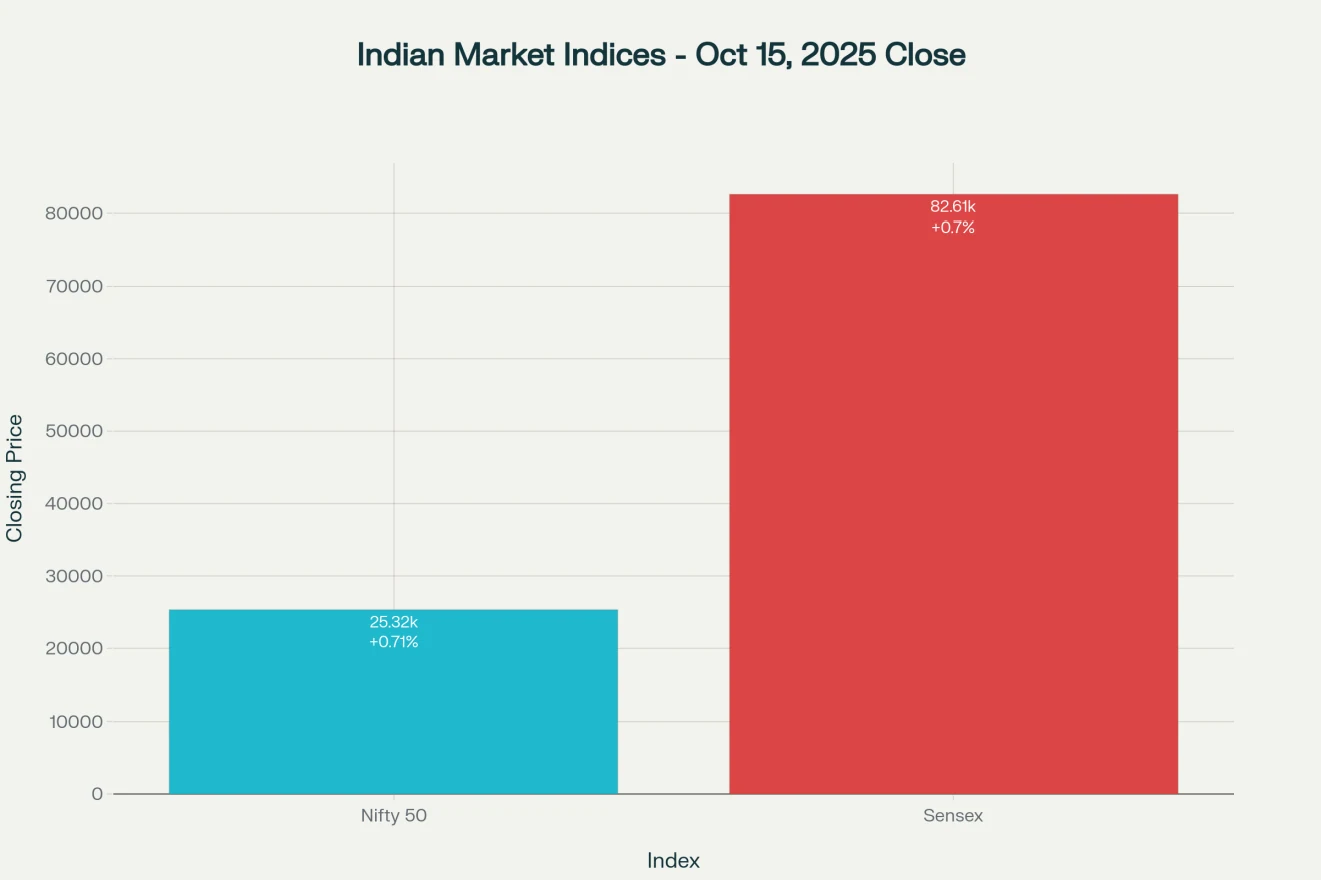
Major Indian indices closed higher on October 15, 2025, snapping a two-day declining streak
Gold hit fresh record highs at $4,220.81 per troy ounce, up 0.29% and marking a stunning 56.69% gain year-over-year as investors seek safe havens amid trade tensions and geopolitical uncertainty. Crude oil prices remain under pressure with WTI at $58.27/barrel (down 0.73%) and Brent at $62.22-62.46/barrel, reflecting concerns about global demand amid US-China trade frictions.
US Treasury Secretary Scott Bessent indicated the United States is nearing conclusion of a trade agreement with South Korea, while discussions with Canada have resumed positively, offering a rare bright spot in the otherwise tense global trade landscape. Morgan Stanley and Bank of America shares surged on Wednesday after reporting upbeat Q3 results driven by substantial stock-trading profits, with analyst estimates for S&P 500 Q3 earnings growth rising to 9.2% from 8.8%.
The renewed US-China trade war escalated with China announcing export restrictions on rare earth elements on October 9, followed by President Trump's warning of potential 100% tariffs, keeping markets on edge. Beijing disclosed sanctions against five American subsidiaries of South Korean shipping firm Hanwha Ocean and is reviewing a US government trade inquiry into China's maritime operations.
When Brent sits near low-60s and FBIL INR is stable/firm, domestic cyclicals (banks, autos, realty) typically see multiple-day tailwinds—until either oil spikes or INR weakens.
Q2 Earnings as Growth Barometer: India's $250+ billion IT services sector faces a critical test with Infosys and Wipro reporting Q2FY26 results today, amid mixed signals on client spending and large deal momentum. Analysts expect Infosys to report moderate sequential growth of 1.5-2% in constant currency terms, supported by recent large deal wins, while Wipro is projected to show flat growth as upfront costs from deal ramp-ups pressure margins.
Margin Pressures and Deal Pipeline Dynamics: The key concern for investors is margin sustainability, with both companies facing headwinds from wage increases, visa costs (including potential H-1B visa policy impacts under the Trump administration), and initial investment requirements for recently won large deals. Wipro's Q1FY26 saw exceptional total contract value (TCV) from large and mega deals, but analysts expect this quarter to show normalization and potential dips as the lumpy nature of deal wins becomes apparent. Management commentary on the consulting business- particularly in the critical BFSI (Banking, Financial Services, and Insurance) vertical-will be crucial, as will updates on client-specific issues and the outlook for discretionary spending.
Sector Comparison with Global Peers: The Indian IT earnings come on the heels of strong US bank earnings, which typically correlate with increased technology spending in financial services—a positive indicator for Indian IT services providers with significant BFSI exposure. However, the divergence between robust bank profits and cautious client technology spending reflects enterprises prioritizing cost optimization and AI-led transformation over traditional IT spend.
Actionable Investor Takeaway: Investors should focus on three metrics: (1) large deal TCV and pipeline visibility for the next 2-3 quarters; (2) margin guidance and the company's ability to absorb deal ramp-up costs while maintaining profitability; and (3) commentary on AI-led opportunities versus traditional service line headwinds. Stocks trading at 20-25x forward earnings require sustained deal momentum and margin stability to justify valuations—any disappointment could trigger 5-7% corrections. Conversely, better-than-expected margins or accelerated deal wins could drive 3-5% upside, with Nifty IT index positioned to test 42,000 levels.
Earnings Calendar: Infosys (post-market), Wipro (post-market), LTIMindtree, Nestle India, Eternal, Jio Financial Services, Waaree Energies, JSW Infrastructure, Metro Brands, Indian Bank.
IPO Activity: Canara Robeco Asset Management Co. and Rubicon Research shares make their D-Street debut today, while Midwest IPO enters the second day of subscription.
Economic Data: India—Foreign Direct Investment (FDI) data and M3 money supply data release; UK—GDP, industrial production, manufacturing production, and goods trade data; US—Weekly jobless claims data.
Derivative Expiry: Weekly Sensex derivatives contracts expiry today, which typically brings increased volatility in the last hour of trading.
Global Cues: Continuation of US-China trade tension monitoring; corporate earnings season in the US continues; Asian market momentum sustainability.
"We are positive about the recent GST cuts and the CRR cut flowing through the banking system. We are seeing some positive signs on the retail disbursements, and we have already demonstrated strong corporate loan growth."
— Amitabh Chaudhry, MD & CEO, Axis Bank (October 15, 2025)
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple verified platforms and cross-validated as per our editorial standards. Investors should conduct independent research and consult financial advisors before making investment decisions. Oorjita FinAI Services is not liable for any investment decisions based on this content. Markets are subject to volatility and past performance does not guarantee future results.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Thursday, 16 October 2025, 7:48 AM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.

1 advancing sector vs. 8 declining sectors Market Breadth: Negative (11% advance rate) Interpretation: Risk-off week; only financials held ground
