Focus shifts to Reliance Industries' Q2 results announcement and over 80 companies reporting earnings, alongside key data on bank loan growth and forex reserves that will set the tone for near-term market direction.

What's different today?: Focus shifts to Reliance Industries' Q2 results announcement and over 80 companies reporting earnings, alongside key data on bank loan growth and forex reserves that will set the tone for near-term market direction.
Enterprise Tech & SaaS Deals: Automotive AI startup Intangles raised $30 million in Series B funding led by Avataar Venture Partners and Baring Private Equity Partners India, while cap-table management platform Qapita closed $26.5 million in Series…
Gold Hits Fresh Record Highs: Gold prices extended their record-breaking rally for the fifth consecutive session, touching $4,361 per ounce in Asian trading on October 17, driven by escalating trade tensions, safe-haven demand, and bets on further…
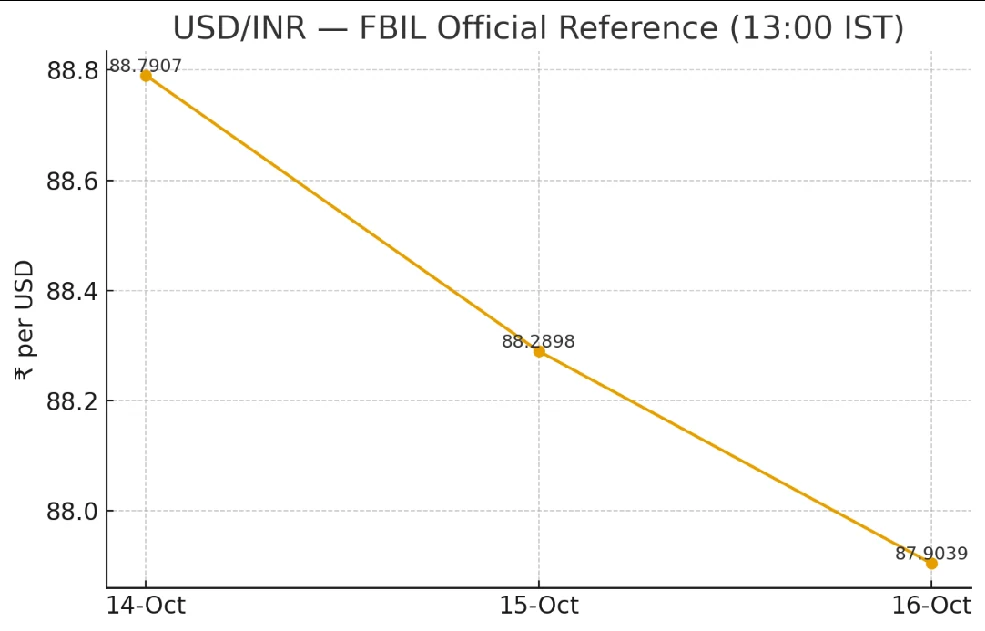
Anchor data: Brent near five-month lows earlier this week; FBIL references eased from ₹88.79 (14-Oct) → ₹88.29 (15-Oct) → ₹87.90 (16-Oct).
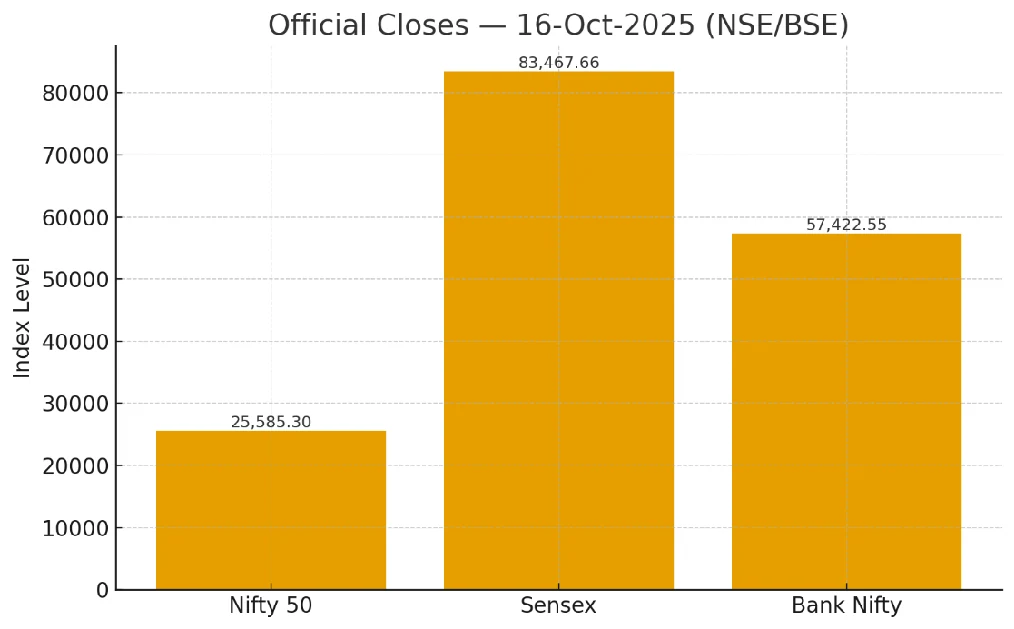
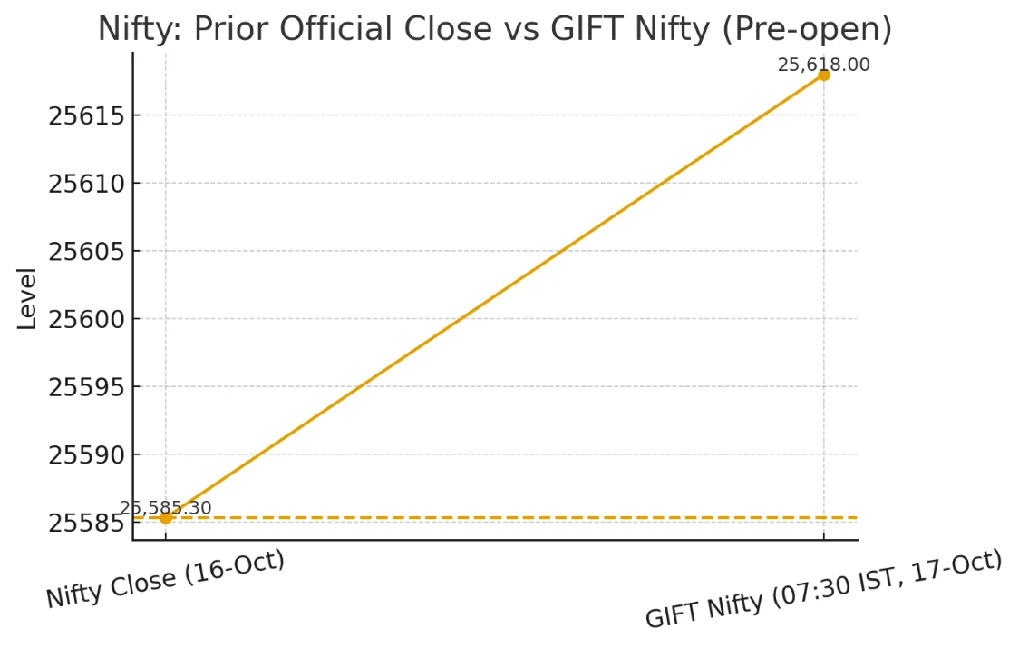
Indian markets are poised for a cautious start on Friday as global headwinds dominate sentiment, with GIFT Nifty signaling a muted-to-negative opening near 25,600 levels. Overnight, Wall Street closed in the red as regional banking sector stress and escalating U.S.-China trade tensions rattled investor confidence, pushing the S&P 500 down 0.63% to 6,629.07 points, while the Dow Jones shed 0.65% to close at 45,952.24. Thursday's strong domestic rally—where Nifty crossed 25,600 for the first time since June 27 and Sensex surged 862 points—faces a reality check as Asian markets trade broadly lower, with Japan's Nikkei down 1%, South Korea's Kospi off 0.47%, and Australia's ASX 200 declining 0.60%.
OnePlus 15 Global Launch: Chinese smartphone maker OnePlus officially launched the OnePlus 15 and OnePlus Ace 6 in China on October 17, with the flagship OnePlus 15 featuring a massive 7,300mAh battery and Snapdragon 8 Gen 5 chipset, setting the stage for a later global rollout including India. The launch comes as premium smartphone demand in India continues to outpace budget segments, offering sectoral tailwinds for telecom and consumer tech stocks.
Google's $15 Billion AI Hub in India: U.S. tech giant Google announced plans to invest $15 billion over the next five years to establish its largest AI hub outside the United States in southern India, significantly enhancing data center capacity and artificial intelligence infrastructure. This marks the largest single tech infrastructure investment in India for 2025 and signals continued bullishness on India's AI and cloud computing ecosystem.
Semiconductor Ecosystem Expansion: India's growing role in the global chip ecosystem remains in focus as global players like Applied Materials, IBM, Infineon, TSMC, and LAM Research deepen their engagement, addressing critical technology gaps in high-speed precision machinery currently 100% import-dependent. Taiwan's Delta Electronics has committed $500 million toward localizing semiconductor equipment manufacturing in India, targeting both fab and assembly-testing segments.
Fintech Funding Surge: Indian startup funding rebounded sharply during October 6-11, with 26 startups raising $284.6 million—a 78% jump from the preceding week's $160.3 million across 14 startups. Leading the charge was stock broking platform Dhan, which secured $120 million in Series B funding led by Hornbill Capital and MUFG, with participation from BEENEXT, DMart founder Ramesh Damani, and DSP Family Office.
Enterprise Tech & SaaS Deals: Automotive AI startup Intangles raised $30 million in Series B funding led by Avataar Venture Partners and Baring Private Equity Partners India, while cap-table management platform Qapita closed $26.5 million in Series B from Charles Schwab Corporation and Citi. The continued flow of institutional capital into fintech SaaS and vertical AI solutions underscores sustained investor confidence in India's B2B tech infrastructure.
Mega IPO Pipeline: India's primary market is heating up with five major IPOs worth over ₹35,000 crore expected in November—Groww (₹7,000 crore), Lenskart (₹8,000 crore), Pine Labs (₹5,800 crore), ICICI Prudential AMC (₹10,000 crore), and boAt (₹2,000 crore)—following strong investor appetite demonstrated by LG Electronics India and Tata Capital listings.
Earnings in Focus: Reliance Industries leads the pack of over 80 companies reporting Q2 results today, including JSW Steel, Wipro, Infosys, Havells India, Dixon Technologies, AU Small Finance Bank, CEAT, Dalmia Bharat, IndiaMART InterMESH, and Tata Technologies. Reliance is expected to post an 11% YoY rise in consolidated net profit to ₹18,450 crore, driven by improved refining margins, robust retail growth, and Jio's sustained subscriber additions.
Thursday's Top Gainers: Nestle India, Tata Consumer, Titan Company, Kotak Mahindra Bank, and Axis Bank led Nifty's 1.03% rally, while sectoral indices including auto, bank, consumer durables, realty, and FMCG rose 0.5-1.7%. PSU Bank index bucked the trend, closing 0.4% lower.
Watch Levels: Nifty tested four-month highs at 25,600 and experts expect a move toward the year's high of 25,669, followed by the crucial 26,000 resistance before challenging record peaks. Support zone remains at 25,400-25,300, with Bank Nifty holding firm above key technical levels after banking stocks drove Thursday's rally.
Stock-Specific Action: LG Electronics India shares continue to command premium valuations after surging 50% on debut, surpassing its parent company's market cap—the highest institutional demand for an IPO since 2008. Monitor RIL for post-earnings price action and guidance on telecom tariffs, retail momentum, and new-energy initiatives.
Gold Hits Fresh Record Highs: Gold prices extended their record-breaking rally for the fifth consecutive session, touching $4,361 per ounce in Asian trading on October 17, driven by escalating trade tensions, safe-haven demand, and bets on further Federal Reserve rate cuts. HSBC raised its 2025 average gold price estimate to $3,355 per ounce, citing geopolitical tension and economic uncertainty.
Oil Plunges to Nearly Five-Year Lows: Crude oil prices tumbled more than 2% on Thursday, with U.S. WTI trading near $57 per barrel and Brent crude at $62, hitting the lowest levels since 2021 after President Trump indicated agreement with Russia's Putin for another summit to discuss ending the Ukraine war. The crude glut has pushed U.S. oil futures down 19% over the past year.
Two Indian refiners have purchased Guyanese crude oil for the first time from Exxon Mobil. The 4 million barrels are scheduled for delivery in late 2025 or early 2026, diversifying India's crude import sources.
Forex Reserves Update: India's foreign exchange reserves stood at $699.96 billion for the week ending October 3, down from the record high of $704.9 billion in late September, reflecting RBI's forex interventions to stabilize the rupee amid foreign investor outflows.
Mukesh Ambani's Reliance Industries is set to unveil its Q2 FY26 results today, with analysts expecting a robust 11-14% year-on-year EBITDA growth to approximately ₹44,400 crore, powered by synchronized strength across its oil-to-chemicals (O2C), retail, and digital services verticals.
O2C Segment Leads the Charge: Brokerages including Axis Capital, UBS, and JPMorgan forecast O2C EBITDA growth of 20-26% YoY, supported by improved refining margins (stronger cracks), resilient petrochemical spreads, and rupee depreciation benefits. HSBC notes that supportive refining margins have bolstered the energy business despite global volatility.
Digital Services (Jio) Momentum: UBS and Nomura project 15-16% EBITDA growth in digital services on the back of continued subscriber additions and modest ARPU (average revenue per user) gains following last year's tariff hikes. The telecom business continues to benefit from India's rising data consumption and 5G rollout tailwinds.
Retail Growth Moderated: Reliance Retail is expected to deliver 10% YoY EBITDA growth, with JPMorgan noting that GST cuts announced in early September contained margins to some extent. However, festive season demand and omnichannel expansion continue to drive top-line growth.
Valuation & Outlook: Most brokerages—including UBS, Axis Capital, Kotak, HSBC, and Morgan Stanley—maintain Buy/Overweight ratings with target prices ranging from ₹1,700-₹1,780, reflecting confidence in RIL's diversified earnings profile. Investors will closely watch management commentary on new-energy initiatives, retail expansion plans, and telecom tariff trajectory.
Anchor data: Brent near five-month lows earlier this week; FBIL references eased from ₹88.79 (14-Oct) → ₹88.29 (15-Oct) → ₹87.90 (16-Oct).
Read-through: Historically supports banks/realty/autos over a 2–5 day window-pending confirmation via breadth and delivery % into close. (Model-based heuristic.)
Actionable Investor Takeaway: RIL's ability to deliver synchronized growth across multiple verticals positions it as a defensive play amid global uncertainty, with the new-energy and digital infrastructure narrative offering long-term re-rating potential. Monitor guidance on capital allocation toward green hydrogen and 5G infrastructure.
Corporate Earnings: Reliance Industries, JSW Steel, Wipro, Infosys, Havells India, Dixon Technologies, AU Small Finance Bank, Bank of India, Central Bank of India, CEAT, CRISIL, Dalmia Bharat, DCB Bank, HFCL, IndiaMART InterMESH, Poonawalla Fincorp, Shoppers Stop, Sobha, Tata Technologies, Tejas Networks, UCO Bank.
Macro Data: India bank loan growth data, foreign exchange reserves update (weekly), Euro Area inflation figures, U.S. import-export statistics.
Global Events: TwitchCon 2025 kicks off in San Diego (October 17-19), Asia-Pacific market reaction to U.S. banking sector stress signals, gold's continued record run amid safe-haven flows.
IPO/Listings: No major listings scheduled; market tracking primary market appetite post-LG Electronics India and Canara HSBC Life Insurance debuts.
"The desire to perform all the time is usually a barrier to performing over time."
A timely reminder as markets navigate volatility—disciplined, patient investing trumps the urge to chase every rally.
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple verified platforms and cross-validated as per our editorial standards. Investors should conduct independent research and consult financial advisors before making investment decisions. Oorjita FinAI Services is not liable for any investment decisions based on this content. Markets are subject to volatility and past performance does not guarantee future results.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Friday, 17 October 2025, 8:08 AM IST.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.
