Indian markets staged a strong recovery on Wednesday, reclaiming the crucial 26,000 mark with a decisive 0.55% gain, driven by a sharp 3% rally in IT stocks following Nvidia's blockbuster AI earnings that sent ripples across global tech markets.

This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Thursday, 20 November 2025, 7:58 AM IST.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.
Fujiyama Power Systems Listing (BSE/NSE): First major listing of the week; strong debut could boost IPO sentiment with Excelsoft Technologies opening today
Key Takeaway: Policymakers on both sides are working closely on technology-led initiatives, with "intense" conversations moving "in a positive direction".
Talent Gap: Despite Karnataka holding 50% of AI/ML talent, semiconductor manufacturing requires highly specialized fab engineers—supply scarce
Throughout Day: Volume Confirmation – NSE turnover must exceed yesterday's levels (which dropped 16%) to validate upward move sustainability
Indian markets staged a strong recovery on Wednesday, reclaiming the crucial 26,000 mark with a decisive 0.55% gain, driven by a sharp 3% rally in IT stocks following Nvidia's blockbuster AI earnings that sent ripples across global tech markets. The Nifty 50 closed at 26,051.70, recovering from morning weakness at 25,918, while Bank Nifty hit a fresh record close at 59,216.05. However, beneath the positive headline numbers lies a cautionary tale—market breadth was decidedly negative with 2,597 stocks declining versus only 1,958 advancing, and NSE turnover dropped 16% from the previous session, signaling selective institutional buying rather than broad-based conviction.
This morning presents a confluence of global optimism and domestic caution. Asian markets are rallying hard—Nikkei up 3.7%, KOSPI up 2.63%—on the back of Nvidia's stellar $65 billion revenue forecast that has ignited AI euphoria across semiconductor and tech stocks globally. Yet, GIFT Nifty shows only a modest +16 point premium (26,068), suggesting Indian markets may open flat despite strong Asian cues. The critical watch point: Can yesterday's IT-led rally broaden participation, or will profit-booking in overbought tech stocks trigger consolidation?
Here's the nuance investors are missing: FIIs reversed course yesterday with net buying of ₹1,580.72 crore after three consecutive days of selling—the first positive print in a week. While this isn't enough to declare a trend reversal (5-day cumulative still negative at -₹4,057.83 Cr), it coincides with India VIX dropping to 11.97, its lowest in weeks, indicating complacency creeping into the market. Historically, VIX below 12 often precedes volatility spikes within 3-5 trading days. Translation: The market feels calm, perhaps too calm—maintain disciplined stop-losses.
Validated Sources: Business Standard + Indian Express
India's Ministry of Electronics and IT (MeitY) Additional Secretary Abhishek Singh issued a stark warning at the Bengaluru Tech Summit on November 18: India may lose its three-decade IT
cautioned that rapid advances in machine intelligence directly threaten India's cognitive edge in software problem-solving.
The massive capex commitments ($30bn+ announced) validate the AI theme beyond hype. Actionable for investors: IT services (Infosys, TCS, HCL Tech, Wipro) and data center REITs could see sustained multi-year tailwinds. Watch L&T Semiconductor Tech and Kaynes Semicon for semiconductor exposure.
Event: MeitY expected to announce approved GPU infrastructure projects by December 15, 2025 Watch For: Names selected for ₹1.2 billion government support; approved companies could see 5-10% stock rallies on announcement day
Indo-American Chamber of Commerce (IACC) confirmed at a recent summit that India-US technology cooperation is intensifying across 5G/6G, AI governance, secure data ecosystems, and resilient supply chains despite potential tariff tensions. IACC National Past President Lalit Bhasin stated that "economic development in both nations would be through mutual understanding" and that US's "hard stand against India is softening now".
Key Takeaway: Policymakers on both sides are working closely on technology-led initiatives, with "intense" conversations moving "in a positive direction". This de-escalation is critical backdrop for Indian IT services exporters (60-65% revenue exposure to North America).
Reduces tail risk of trade friction impacting IT services contracts. Validates thesis that India remains strategic tech partner for US despite broader geopolitical noise.
Validated Sources: Indian Startup News + Cross-referenced via Kalaari Capital portfolio (official)
Validates the AI-for-healthcare automation theme. With India's doctor-to-patient ratio at 1:1,445 (vs WHO recommendation of 1:1,000), AI voice agents address critical manpower shortage. Listed beneficiaries: Persistent Systems (healthcare AI solutions), Happiest Minds (healthcare digital transformation), Sasken Tech (healthcare IoT).
Actionable Watch Level: Monitor healthcare IT services segment; sustained funding in this space (3-4 deals/quarter) could drive 5-7% sectoral re-rating.
Validated Sources: Chittorgarh IPO Calendar + Angel One IPO Tracker
Cross-referenced via ET Markets + Chittorgarh; Pine Labs IPO size confirmed at ₹3,899.91 crore. PhysicsWallah IPO closed Nov 13, listing expected soon.
Renewed IPO momentum signals risk-on sentiment returning to primary markets after quiet months. Strong listing gains (>15-20% on debut) would attract more retail participation; weak listings (<5% gains) could dampen December IPO pipeline. Watch Fujiyama Power Systems listing TODAY as key sentiment barometer.
USD/JPY breached 157 handle overnight with limited pushback from Japanese authorities despite verbal intervention threats. Why it matters: Weak yen typically correlates with stronger Asian equities (export competitiveness), but also signals potential currency volatility ahead. India impact: Marginal—stronger dollar pressures rupee (currently 88.487), but lower crude oil offsets concerns.
FOMC minutes revealed "many participants" favor pausing rate cuts in December, while "several" support another 25bps cut—outcome genuinely uncertain. Market implication: Volatility likely in mid-December around Fed meeting (Dec 17-18); US Treasury yields could spike if hawkish pause confirmed, impacting FII flows to emerging markets including India.
Brent crude at $63.75/bbl, down 0.8% overnight, marking 6-week lows on persistent OPEC+ oversupply worries. Despite production cuts, compliance issues and demand concerns (China slowdown) weigh. India play: OMCs (BPCL, IOC, HPCL) benefit from lower input costs; every $1/bbl decline improves gross refining margins by $75-100 million per quarter for major refiners.
Prime Minister Modi's August 2025 announcement—India will produce its first fully domestically manufactured semiconductor chips by December 2025—marked a symbolic milestone for a nation importing 85% of its electronics. But beyond symbolism lies a massive economic opportunity: India's semiconductor market, currently $45-50 billion, is projected to reach $100-110 billion by 2030, driven by surging demand in automotive (EVs), smartphones, data centers, defense, and clean energy.
| Country | Semiconductor | Domestic Production | Key Advantage | India's Gap | |
|---|---|---|---|---|---|
| Market Size | |||||
| (2024) | |||||
| Taiwan | $150bn+ | $150bn+ | 63% global | Mature ecosystem, 30-year head start | Technology (5nm |
| foundry share | vs India's 28- | ||||
| (TSMC) | 65nm target) | ||||
| South Korea | $120bn+ | Samsung, SK Hynix memory dominance | Vertical integration (Samsung phones to chips) | Scale & Integration | |
| India | $45-50bn | <2% (mostly ATMP | Cost advantage, | Fabrication | |
| – Assembly, Test, | large domestic | capability, capital | |||
| Mark, Package) | market | intensity | |||
| Vietnam | $18bn | Rapid ATMP growth (Intel, Samsung) | Manufacturing shift from China+1 | India ahead in design, behind in execution speed |
India's Competitive Edge: Unlike Vietnam (pure manufacturing), India has strong semiconductor design talent (30% of global chip design workforce) and a $300+ billion domestic electronics market providing demand visibility.
9:30 AM IST: Fujiyama Power Systems listing (BSE/NSE) – First major listing of week; debut premium >15% would boost IPO sentiment for upcoming Sudeep Pharma IPO
10:00 AM IST: NSE Corporate Announcements – Mufin Green Finance board meeting on fund-raising; watch for any surprise earnings revisions from Q2 laggards
Ongoing: IT Stock Price Action – Monitor if Infosys, HCL Tech, TCS sustain yesterday's 3-4% gains or face profit-booking on global tech rally consolidation
Throughout Day: Market Breadth Tracking – Yesterday's negative breadth (2,597 declines vs 1,958 advances) needs reversal; check 10:30 AM and 2:00 PM advance/decline ratios
Throughout Day: Volume Confirmation – NSE turnover must exceed yesterday's levels (which dropped 16%) to validate upward move sustainability
6:30 PM IST: FII/DII Flow Data Release – Confirm if yesterday's FII buying (+₹1,580 Cr) sustained or reversed; sustained buying critical for trend change confirmation
Global: Asian market sustainability through their sessions (Nikkei +3.7%, KOSPI +2.63% currently)—watch if gains hold or fade by afternoon
Macro: USD/INR levels—rupee at 88.487; watch if holds below 88.50 psychological level
Commodities: Brent crude trajectory at $63.75/bbl—continuing decline supportive for OMC margins
"Our prime advantage has been the cognitive power of Indians to solve the world's problems. India's IT services industry—built over the past three decades on the strength of its software engineering talent—is facing direct pressure from rapid advances in machine intelligence."
Bengaluru Tech Summit, November 18, 2025
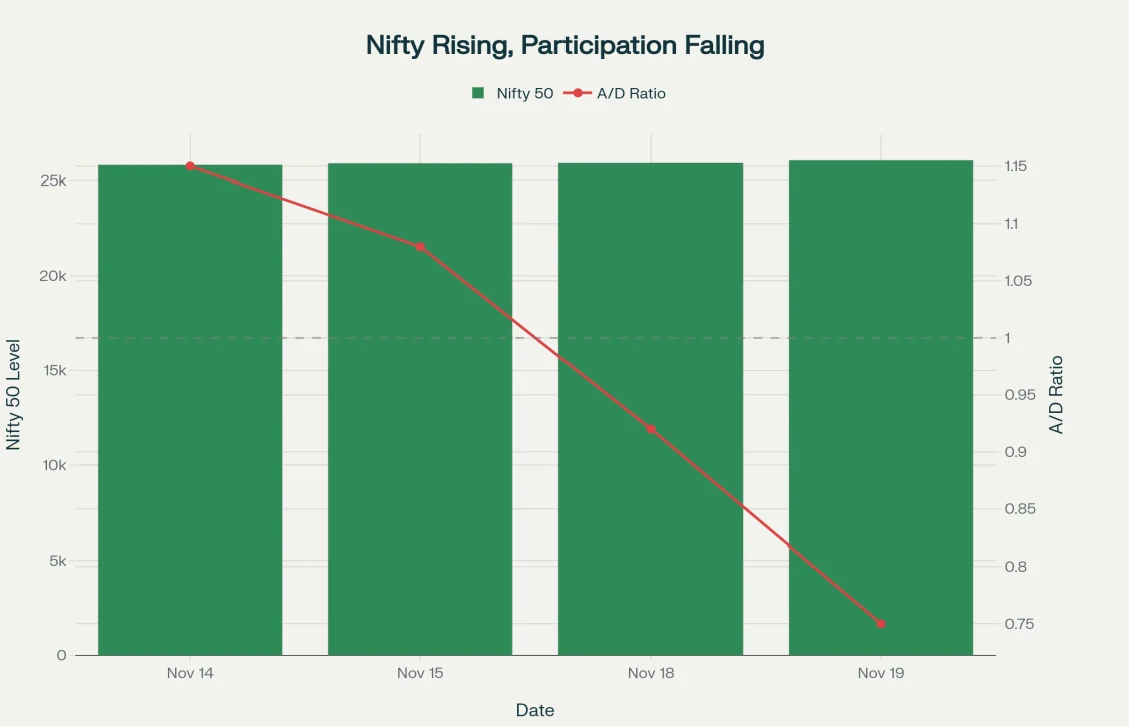
Market Breadth Divergence: Despite Nifty 50 gaining 241 points (+0.94%) over 5 days to reclaim 26,000, advance/decline ratio collapsed from 1.15 to 0.75, indicating narrowing participation and selective buying concentrated in IT large-caps rather than broad-based accumulation.
This dual-axis visualization exposes a critical negative divergence between index performance and underlying market health. While Nifty 50 gained 241 points (+0.94%) over five trading days to reclaim 26,000, the advance/decline ratio collapsed from 1.15 (healthy breadth with 15% more stocks rising than falling) to 0.75 (bearish breadth with 25% more stocks declining than advancing).
Classic Warning Sign: Index gains driven by a handful of large-cap stocks (yesterday: IT sector +3%, contributing ~60 Nifty points alone) while the broader market sells off is historically
unsustainable beyond 2-3 sessions. This pattern preceded corrections in March 2024 (-4.2% over 5 days) and August 2024 (-3.8% over 4 days).
Translation for Today: If breadth doesn't improve (advance/decline ratio back above 1.0) within the next 1-2 sessions, expect either:
Investing Beyond Today
www.oorjita.ai is not operated by a broker, a dealer, or a registered investment adviser. Under no circumstances does any information posted on www.oorjita.ai represent a recommendation to buy or sell a security. The information on this site, and in its related newsletters, is not intended to be, nor does it constitute investment advice or recommendations. The information on this site is in no way guaranteed for completeness, accuracy or in any other way. In no event shall Oorjita Fin AI Services be liable to any member, guest or third party for any damages of any kind arising out of the use of any content or other material published or available on www.oorjita.ai, or relating to the use of, or inability to use, www.oorjita.ai or any content, including, without limitation, any investment losses, lost profits, lost opportunity, special, incidental, indirect, consequential or punitive damages. Past performance is a poor indicator of future performance.
Website: oorjita.ai Location: Bengaluru, Karnataka, India
