Ajax Engineering, a leading manufacturer in India's concreting equipment sector, holds a dominant position with a 75% market share in the Self Loading Concrete Mixer (SLCM) segment.

Key Assumptions: Anticipates H2 FY26 demand recovery, margin normalization by FY27, and continued infrastructure investment.
Ajax Engineering, a leading manufacturer in India's concreting equipment sector, holds a dominant position with a 75% market share in the Self Loading Concrete Mixer (SLCM) segment.
Ajax Engineering Limited stands at the forefront of India's concrete equipment manufacturing sector, especially in the SLCM segment.
Ajax Engineering commands a clear lead with 75% market share in SLCMs, classified within the automobile/commercial vehicle sector and positioned as a mid-cap entity.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Friday, 19 September 2025, 9:16 PM IST.

All four layers aligned bearish. A/D = capitulation breadth.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.
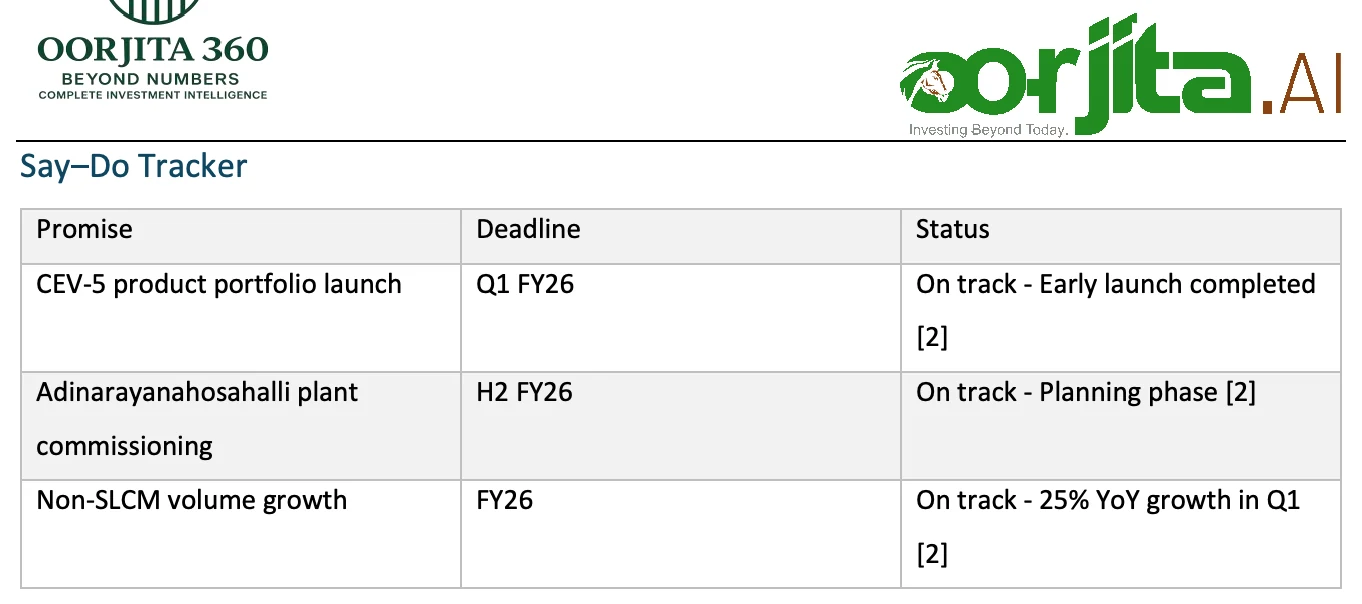
Ajax Engineering, a leading manufacturer in India's concreting equipment sector, holds a dominant position with a 75% market share in the Self Loading Concrete Mixer (SLCM) segment. The company is currently navigating the challenges of transitioning to CEV-5 emission norms, which has impacted margins during Q1 FY26. Despite these pressures, Ajax trades at premium valuations (P/E 29.66x), with a fair value estimated between ₹580-650. The potential for margin recovery and demand revival serve as key catalysts for future performance. Primary risksincluderegulatory transitioncosts, possible delays ininfrastructure execution, and margin compression resulting from changes in the product mix. In the short term, watch for demand recovery in H2 FY26, progress on new plant commissioning, and stabilization of the CEV-5 product portfolio.
| Metric | Value |
|---|---|
| P/E Ratio | 29.66x |
| EV/EBITDA | 22.66x |
| ROCE | 28.33% |
| FCF Yield | — |
| Debt/EBITDA | -2.21x |
| Dividend Yield | 0.00% |
Ajax Engineering Limited stands at the forefront of India's concrete equipment manufacturing sector, especially in the SLCM segment. The company achieved a revenue milestone of ₹2,000 crore in FY25, a testament to its solid market leadership. Its business segments span SLCM equipment and a range of diversified products for infrastructure construction. Long-term demand prospects are buoyed by ongoing infrastructure development and urbanization, with the company focusing on B2B expansion in metro areas for diversified growth.
Ajax Engineering commands a clear lead with 75% market share in SLCMs, classified within the automobile/commercial vehicle sector and positioned as a mid-cap entity. While recent stock performance has lagged sector benchmarks, the company benefits from its first-mover advantage in launching CEV-5 compliant products, enabling early market penetration despite transition costs. Its debt-free balance sheet ensures flexibility during regulatory transitions.
Ajax Engineering relies on a primarily domestic supply chain, minimizing geopolitical risk. Debt-free status providesstabilityduringdisruptions,whilestrongdomesticmarketsharereducesexposuretointernationaltrade tensions.
AjaxEngineering’sinnovationindevelopingand launchingCEV-5 compliant productsunderscoresitscompetitive edge. Ongoing R&D investments reinforce this position, enabling differentiation from competitors.
ICICI Securities maintains a Buy rating with a target price of ₹900. Marketsmojo, however, considers the stock overvalued at current levels due to premium PE multiples, reflecting mixed analyst sentiment during this transition period.
Ajax Engineering operates alongside major automobile names and specialized concrete equipment manufacturers. Its competitive strengths include a debt-free balance sheet, early adoption of CEV-5 standards, and commanding a 75% SLCM market share.
Promoter concentration remains high, ensuring managerial control, while institutional interest has grown. Retail holding decline may affect liquidity during volatility.
