
The H-1B Shock: Impact Analysis for Indian IT
The Trump administration's $100,000 H-1B visa fee hike, effective September 21, 2025, represents a paradigm shift for Indian IT services companies.
The Trump administration's $100,000 H-1B visa fee hike, effective September 21, 2025, represents a paradigm shift for Indian IT services companies.

Revenue Mix: Q1 FY26 revenue of $7.42 billion (-3.1% YoY in CC); North America contributes ~50% of revenues.
Pricing Power: Premium positioning with industry-leading margins (24.5% operating margin).
Pricing Power: Operating margin of 20.8%, raised FY26 guidance lower end to 1-3%.
Client Communication: Proactive outreach on pass-through mechanisms and delivery model changes
The Trump administration's $100,000 H-1B visa fee hike, effective September 21, 2025, represents a paradigm shift for Indian IT services companies. While the fee applies only to new petitions (not existing visa holders), it fundamentally alters the economics of the traditional onsite-offshore delivery model that has powered the sector's growth for decades.
Revenue Mix: Q1 FY26 revenue of $7.42 billion (-3.1% YoY in CC); North America contributes ~50% of revenues. Strong presence across BFSI (31%), Manufacturing (15%), and Tech/Telecom verticals.[6][7][8][9]
Delivery Mix: Offshore-heavy model with ~80% offshore, 20% onsite mix. Company maintains significant US operations but has been localizing aggressively - current US employee base is 50-60% Americans.
H-1BExposure:Largestrecipientwith5,505H-1Bvisasannually,butrepresentssmallfractionof600,000+ global workforce. Strong local hiring capabilities provide buffer.
Pricing Power: Premium positioning with industry-leading margins (24.5% operating margin). Historical precedence of passing through regulatory cost changes via contract renegotiations.
Revenue Mix: $4.94 billion revenue (+3.8% YoY); highest US exposure at ~60% of revenues. Strong in Financial Services (27.9%), Manufacturing (16.1%).
H-1B Dependency: 2,004 H-1B visas with estimated highest percentage of visa-dependent workforce among Tier-1 players. Onsite mix around 25-30%.
Pricing Power: Operating margin of 20.8%, raised FY26 guidance lower end to 1-3%. Strong deal momentum with $3.8B TCV in Q1.
Revenue Mix: $3.55 billion (+3.7% YoY); ~45% US revenue exposure. Services revenue grew 4.5% YoY in CC terms.
H-1B Profile: HCL America holds 1,728 H-1B visas. Onsite mix estimated at 30%. Operating margin pressured at 16.3% due to Gen AI investments.
LTIMindtree: $1.15B revenue, 1,844 H-1B visas, high US exposure (~55%) creates vulnerability. Wipro: 1,523 H-1B visas but 70% US workforce now comprises locals, reducing direct impact. Persistent Systems: Stellar 18.8% YoY growth, but 75% US revenue and 45% onsite mix creates high exposure. Coforge: $442M revenue, claims "minimal impact" from H-1B changes, strong growth momentum.
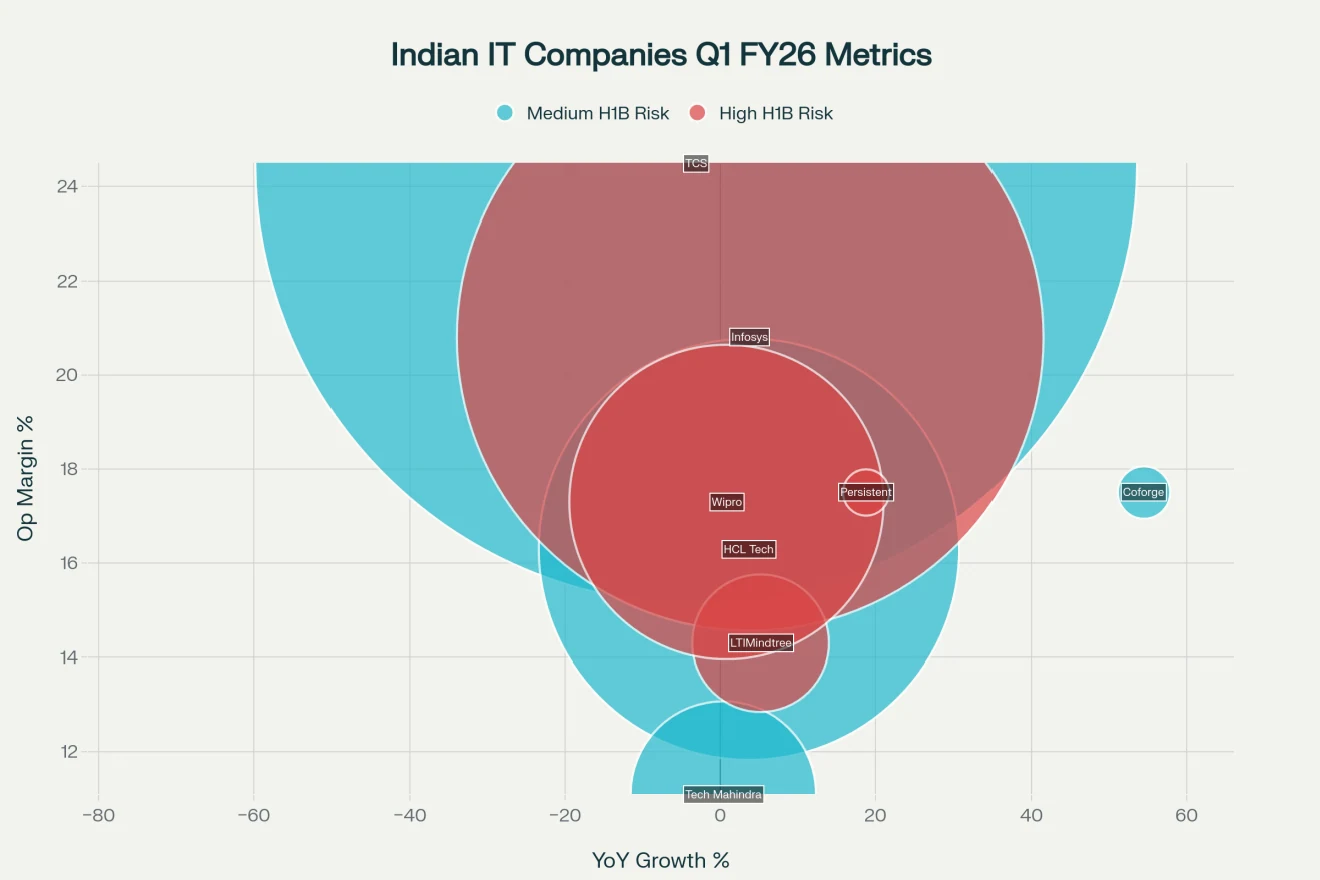
Indian IT Companies: Q1 FY26 Performance & H-1B Exposure Assessment
−30% petitions −15–25 bps −10–20 bps −5–15 bps ~flat to −10 bps Base petitions −40–80 bps −25–60 bps −10–45 bps −0–30 bps +30% petitions −70–120 bps −50–100 bps −30–75 bps −15–55 bps
Secondary sliders: Local‑hire +25ppt typically improves EBIT by ~10–25 bps net; Offshore +5ppt over 3 quarters can recoup ~10–30 bps if SLA intact.
Q+1 (Oct-Dec 2025): Fee shock absorption, client negotiation intensive.
Q+2 (Jan-Mar 2026): Local hiring ramp-up, margin pressure peak.
Q+3 (Apr-Jun 2026): Steady state with repriced contracts, productivity recovery
Overweight: TCS, HCL Tech (defensive positioning).
Underweight: High-exposure mid-caps until clarity on pass-through success.
Tactical: Monitor Q+1 earnings for magnitude of impact and management commentary
This analysis is for informational purposes only and should not be considered investment advice. Impact estimates are scenario-based and highly sensitive to assumptions around policy implementation, client behavior, and company execution capabilities. Readers should verify all data points with primary company sources and consult qualified financial advisors before making investment decisions. The H-1B policy landscape remains fluid and subject to further regulatory changes.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 22 September 2025, 2:13 PM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.

1 advancing sector vs. 8 declining sectors Market Breadth: Negative (11% advance rate) Interpretation: Risk-off week; only financials held ground