
H1-B Visa Storm: Redefining India's IT Playbook
Key watch factors for the day include the market's reaction to the H-1B visa fee hike, the rollout of new GST regulations, and ongoing FII activity, which saw net buying of ₹390.74 crore on Friday.
Key watch factors for the day include the market's reaction to the H-1B visa fee hike, the rollout of new GST regulations, and ongoing FII activity, which saw net buying of ₹390.74 crore on Friday.

H-1B Visa Shock: The US administration's decision to impose a steep $100,000 annual fee per H-1B visa, effective September 21, is expected to send shockwaves through the Indian IT sector.
Key watch factors for the day: include the market's reaction to the H-1B visa fee hike, the rollout of new GST regulations, and ongoing FII activity, which saw net buying of ₹390.74 crore on Friday.
Technical levels: Nifty finds support at 25,200 with first resistance at 25,400, while Bank Nifty closed at 55,458.85 (-0.48%).
Corporate Events: Several companies have board meetings scheduled, including Asian Hotels (West) and Sudarshan Chemical Industries for financial results, and Brand Concepts for fund-raising
Indian markets brace for a tepid start as GIFT Nifty trades marginally higher at 25,369.50, up just 0.05% as of 6:31 AM. Friday's session broke a three-day winning streak with Nifty closing at 25,327.05 (-0.38%) and Sensex at 82,626.23 (-0.47%), primarily due to selling pressure in IT, FMCG, and banking sectors.
Today is different as two major factors come into play:
Key watch factors for the day include the market's reaction to the H-1B visa fee hike, the rollout of new GST regulations, and ongoing FII activity, which saw net buying of ₹390.74 crore on Friday.
Corporate earnings updates from Manba Finance, and Melstar Information Technologies' announcements.
The Indian IT sector faces a seismic shock as the US implements a $100,000 H1-B visa fee, affecting the $245 billion industry where an estimated 40-50% of mid-level engineers aspire to work in the US. Major companies including Microsoft have issued 24-hour deadline warnings to employees, while the White House clarified the fee applies only to new applications. The sector sentiment is decidedly negative, with analysts anticipating a direct financial impact and a strategic overhaul of talent deployment. Sector sentiment remains bearish with TCS, Infosys, and Wipro expected to be in sharp focus as investors assess the long-term implications on the traditional onshore-offshore business model.
Semiconductor push (India): Momentum continues (Lam Research capex; Tata-PSMC fab progress; MeitY partnerships). Theme tailwind for equipment, gases/chemicals, specialty materials suppliers.
India's startup ecosystem witnessed a robust uptick with $245 million raised across 19 deals in the third week of September, compared to $146 million the previous week. Notable deals include Infra.Market securing ₹732 crore (~$83 million) from Tiger Global and Accel, FinBox raising $40 million from WestBridge Capital, and Blue Energy Motors bagging $30 million. The late-stage funding surge signals renewed investor confidence, with sectors spanning fintech, electric vehicles, and B2B services leading the charge.
Primary market: India is in the midst of a record IPO month into Sep-end; Ganesh Consumer Products opens today (₹306–₹322). Multiple SME/mainboard deals crowd the week (Atlanta Electricals, TechD Cybersecurity listing etc.). Liquidity test for secondary markets.
Key stocks in focus include Garden Reach Shipbuilders, Shipping Corp, Infosys, and NBCC as per market trackers. Friday's biggest losers were HCL Technologies, ICICI Bank, and Nestle, while Adani Enterprises, Adani Ports, and SBI Life emerged as gainers.
IT services: Sentiment negative on H-1B headlines; watch gap reactions in large-caps vs mid-caps; any intraday recovery on low advance-decline would be telling.
Technical levels: Nifty finds support at 25,200 with first resistance at 25,400, while Bank Nifty closed at 55,458.85 (-0.48%). Sectoral action: Power and PSU banks gained 1% each, offsetting losses in consumer durables and IT.
Global cues remain supportive with US markets hitting fresh record highs - Dow up 0.37% to 46,315.27, S&P 500 advancing 0.49% to 6,664.36, and Nasdaq surging 0.72% to 22,631.48. Asian markets opened positively with Japan's Nikkei climbing 0.74% and South Korea's Kospi gaining 0.71%. Commodity corner: Crude oil rose to $62.73/barrel (+0.53%), while gold touched $3,689.48/oz (+0.13%).
What changed: A $100k one-time fee on new H-1B petitions (White House clarification) introduces friction to onsite hiring costs. Earlier reports suggested an annual charge; that has been walked back officially, but headline risk remains.
leverage, and pricing power; be selective in mid-caps with high onsite reliance until policy noise settles.
"The 'American Dream' for hopeful workers is going to be difficult. Companies will limit international travel and maximize work output from countries such as India, Mexico, and the Philippines." - Ganesh Natarajan, Former CEO, Zensar Technologies[6]
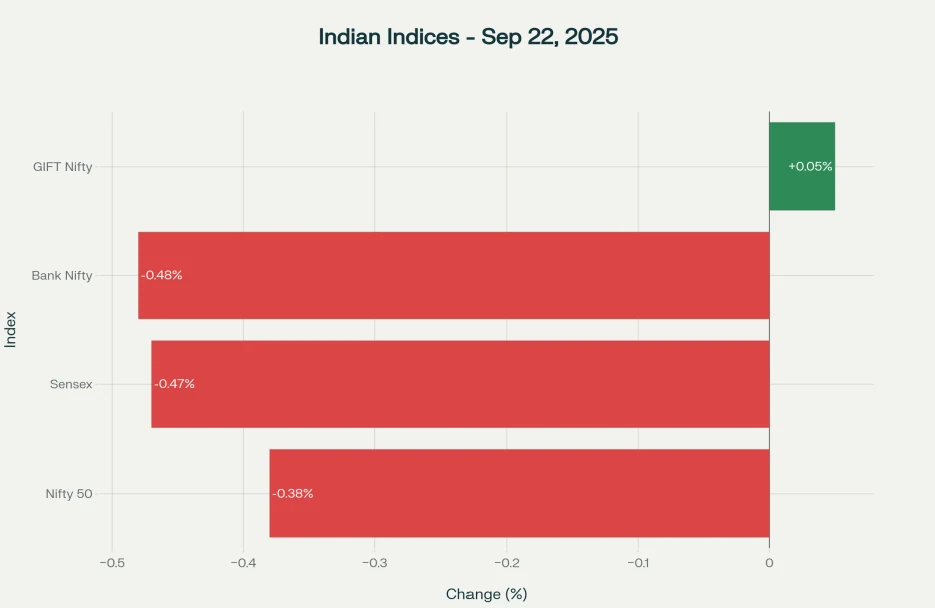
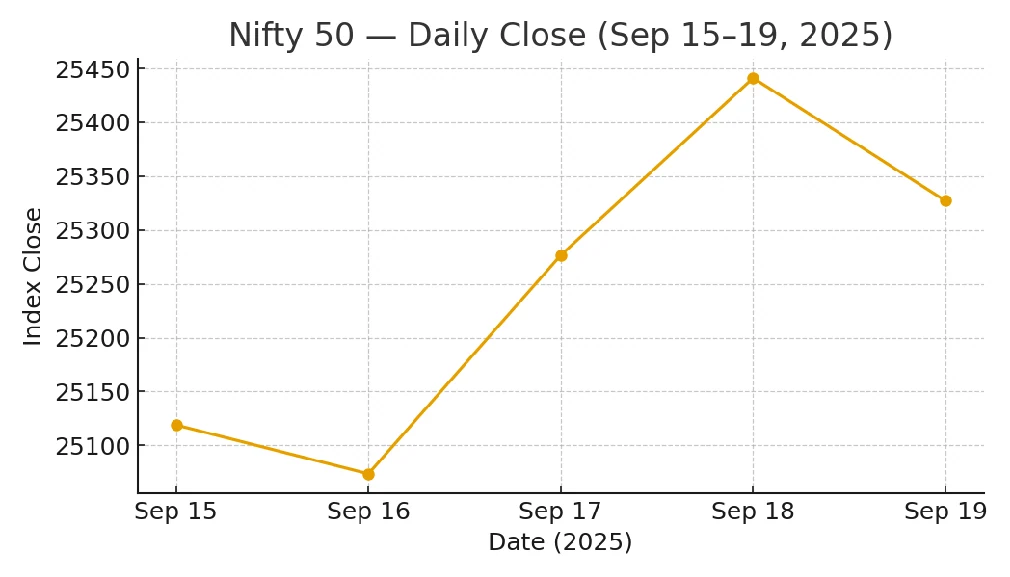
Key Indian market indices performance showing mixed sentiment with GIFT Nifty marginally positive while major indices closed lower on Friday.
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple reliable platforms and validated for accuracy. Readers should conduct their own research and consult with financial advisors before making investment decisions. Past performance does not guarantee future results. Oorjita disclaims responsibility for any investment decisions based on this content.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 22 September 2025, 8:21 AM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.

1 advancing sector vs. 8 declining sectors Market Breadth: Negative (11% advance rate) Interpretation: Risk-off week; only financials held ground