Indian markets closed Monday on a weak note with Nifty 50 slipping below 25,200 and Sensex down 466 points, extending the losing streak for a second consecutive day.

Global Tech Surge: Nvidia surged to record highs after announcingup to $100billion investment in OpenAI over the next few years, fueling AI optimism and driving Nasdaq to a 0.7% gain.
Major International Interest: UK's NatWest Group announced plans to invest $250,000 to $2 million in early-stage Indian startups, focusing on AI, payments, and digital tools while expanding its India tech centers to hire 3,000 additional…
Urban Company's Secondary Sale: Home services firm Urban Company is in advanced discussions for a secondary share sale worth approximately ₹450 crore.
Sectoral Divergence: Monday's session saw power (+1.6%), oil & gas (+0.4%), and metals (+0.4%) gaining ground while IT (-2.7%) and pharma (-1.2%) faced selling.
Indian markets closed Monday on a weak note with Nifty 50 slipping below 25,200 and Sensex down 466 points, extending the losing streak for a second consecutive day. The selloff was primarily driven by IT stocks facing headwinds from potential H-1B visa fee hikes, while global cues remained supportive with US markets hitting record highs for the third straight session.
GIFT Nifty futures indicate a flat opening at 25,305 levels, up marginally by 16.50 points, suggesting cautious sentiment ahead of today's session. Key watch factors include IT sector recovery potential, FII/DII flows, and global tech momentum spillover effects.
Global Tech Surge: Nvidia surged to record highs after announcingup to $100billion investment in OpenAI over the next few years, fueling AI optimism and driving Nasdaq to a 0.7% gain. Oracle also rallied on reports of joining TikTok's US operations management alongside White House backing.
Indian IT Under Pressure: Domestic IT giants faced selling pressure with TCS, Infosys, Wipro, and Tech Mahindra among top Nifty losers, declining 2.7% as a sector on concerns over proposed $100,000 H-1B visa fees. The sentiment remains fragile with pre-open data showing continued weakness in IT majors.
Sector Impact: The divergence between global tech euphoria and Indian IT caution creates interesting arbitrage opportunities, with focus on companies with domestic revenue exposure versus those dependent on US visa workers.
Major International Interest: UK's NatWest Group announced plans to invest $250,000 to $2 million in early-stage Indian startups, focusing on AI, payments, and digital tools while expanding its India tech centers to hire 3,000 additional professionals.
Chakr Innovation (deeptech/materials): $23m Series C led by Iron Pillar — ET + TOI. Ripple: clean-air, industrial emissions & cap-goods adjacencies.
Tide (fifintech): $120m led by TPG; ~half of customers in India. Ripple: SME banking/embedded fifinance partnerships domestically.
IPOs opening (today): Mainboard/SME names per calendar (check bidding as day progresses).
Domestic Funding Momentum: Recent weeks saw significant funding across sectors - ILJIN Electronics raised $144M from ChrysCapital, GREW Solar secured $36M from GeeCee Holdings, and All Things People (ATP) HR tech startup among notable deals. The funding ecosystem shows resilience with investors backing both traditional manufacturing and new-age tech solutions.
Pre-Open Leaders: Eternal (+1.03%), Shriram Finance (+0.76%), SBI Life (+0.72%) show strength in pre-market trading, while IT stocks continue their decline with Infosys (-3.73%), Tech Mahindra (-3.53%), and HCL Tech (-3.03%) facing pressure.
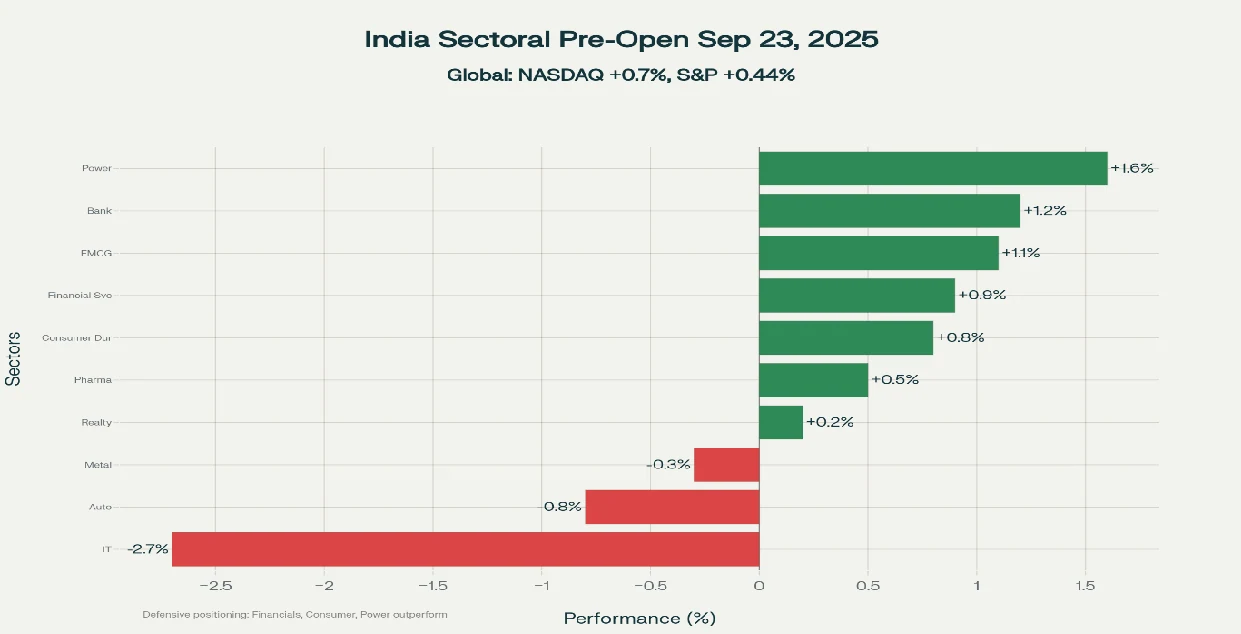
Sectoral Divergence: Monday's session saw power (+1.6%), oil & gas (+0.4%), and metals (+0.4%) gaining ground while IT (-2.7%) and pharma (-1.2%) faced selling. Watch for rotation into defensive sectors and infrastructure plays.
Sectors: IT underperform; power/oil & gas/metals showed resilience on Mon. Bias at open: mild bounce if GIFT signal holds; IT remains headline-sensitive to H-1B updates.
Gold touched fresh record highs at $3,756.57/oz, up 0.25% as Fed rate cut expectations intensify with speculation of two more cuts before year-end. Bitcoin and cryptocurrencies faced selling pressure despite broader risk-on sentiment. Asian markets showed mixed performance with Japan's Nikkei up 0.99% while Hong Kong's Hang Seng declined 0.76%.
PFRDA mulls allowing pension funds exposure to gold/silver ETFs, VC/AIFs & private credit — medium-term tailwind for India alt-assets.
Europe autos wobble (Porsche/VW outlook cuts); watch Indian ancillary/export names for sympathy.
The tech sector presents a tale of two narratives today. While Nvidia's $100 billion OpenAI commitment showcases the massive capital flowing into AI infrastructure globally, Indian IT services face regulatory headwinds with proposed H-1B visa fee increases. This divergence creates strategic implications for Indian tech companies - those with strong domestic AI capabilities and reduced US visa dependency may outperform peers heavily reliant on traditional offshore models.
The contrast highlights the importance of business model evolution, with companies investing in automation, AI tools, and local talent likely to weather regulatory changes better than those dependent on cost arbitrage through visa programs.
Macro Events: No major domestic economic data releases; focus on FII/DII flow data and global cues from Asian markets. Earnings/Corporate: Monitor IT sector management commentary on H-1B impact and Q2 guidance revisions. Technical: Nifty's ability to reclaim 25,250 levels and Bank Nifty's hold above 55,000 crucial for sentiment.
“ AI capex is becoming the new oil—whoever controls compute shapes margins. ” — Sell-side reaction to Nvidia–OpenAI plan
Pre-open market leaders showing sectoral rotation with financials and consumer stocks gaining while IT continues decline - highlighting defensive positioning ahead of potential market volatility.
This newsletteris forinformational purposes only and should not be construedas investment advice. Please consult with a qualified financial advisor before making any investment decisions. Past performance is not indicative of future results. Oorjita FinAI Services and its affiliates are not responsible for any investment losses incurred based on this information.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Tuesday, 23 September 2025, 8:08 AM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.

Institutional flows showed a divergence, with Foreign Institutional Investors (FII) registering net outflows of ₹972.13 crore (provisional), while Domestic Institutional Investors (DII) pumped in ₹1,666.98 crore (provisional), resulting in a net combined inflow of ₹694.85 crore.
