
Dharmaj Crop Guard: A Small Agrochemical Player Building Its Moats
Dharmaj Crop Guard (DCGL) manufactures agro-chemicals across branded formulations (B2C), institutional formulations (B2B domestic & exports), and active ingredients (AIs/technicals).
Dharmaj Crop Guard (DCGL) manufactures agro-chemicals across branded formulations (B2C), institutional formulations (B2B domestic & exports), and active ingredients (AIs/technicals).

Dharmaj Crop Guard (DCGL) manufactures agro-chemicals across branded formulations (B2C), institutional formulations (B2B domestic & exports), and active ingredients (AIs/technicals).
DCGL is a small/mid-cap player relative to Rallis, Sumitomo Chemical India, Sharda Cropchem, etc.
Key moats include distribution scale, regulatory filings, and AI integration.
Distribution: 6.5/10 | Cost/process: 5.5/10 | Regulatory: 6/10 | AI integration: 6.5/10
Dharmaj Crop Guard (DCGL) manufactures agro-chemicals across branded formulations (B2C), institutional formulations (B2B domestic & exports), and active ingredients (AIs/technicals). It operates within the Indian agrochemicals industry, which is expanding at mid-to-high single digit CAGR. India’s agrochemicals TAM is ~US$9–13bn, with global opportunities as China+1 sourcing continues.
DCGL is a small/mid-cap player relative to Rallis, Sumitomo Chemical India, Sharda Cropchem, etc. Its differentiation lies in branded B2C reach (~18,000 retailers), institutional tie-ups, and AI capacity expansion.
Key moats include distribution scale, regulatory filings, and AI integration. Moat durability is moderate but improving as branded sales and AI exports scale.
Distribution: 6.5/10 | Cost/process: 5.5/10 | Regulatory: 6/10 | AI integration: 6.5/10
Overall competitive-advantage score: 6.2/10.
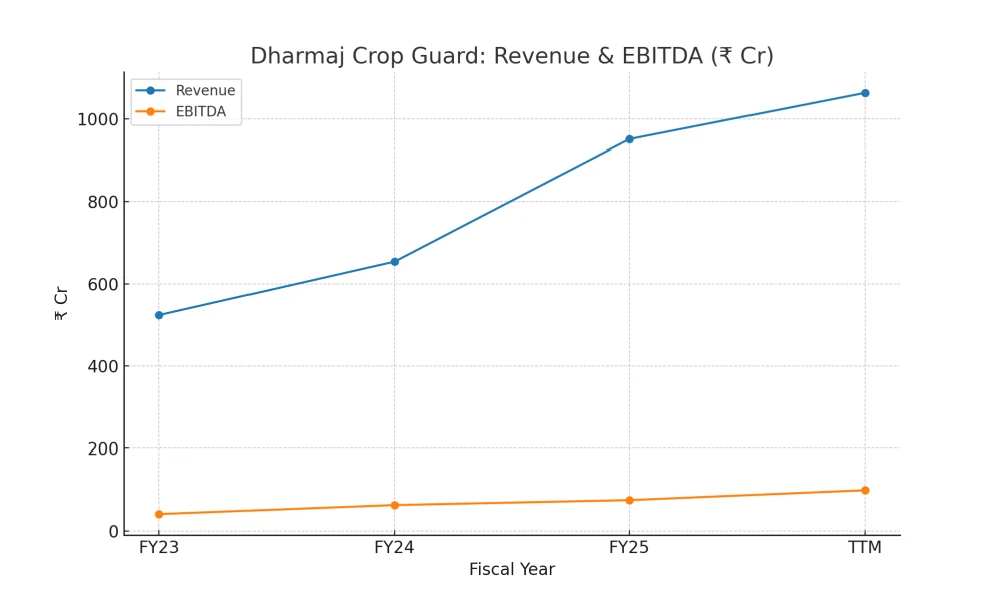
Q1 FY26 showed a strong rebound with revenue of ₹367 Cr, EBITDA ₹51 Cr, and PAT ₹33 Cr (margins 13.8%).
Sales grew from ₹524 Cr (FY23) to ₹951 Cr (FY25), with EBITDA ₹75 Cr and PAT ₹35 Cr. Margins volatile (8–10%) but stabilizing with AI contribution.
Debtor days stretched to 95 in FY25 (vs 66 in FY24). CCC improved to 67 days (vs 84), driven by higher payables. Cash flows improved in FY25 (₹39 Cr CFO).
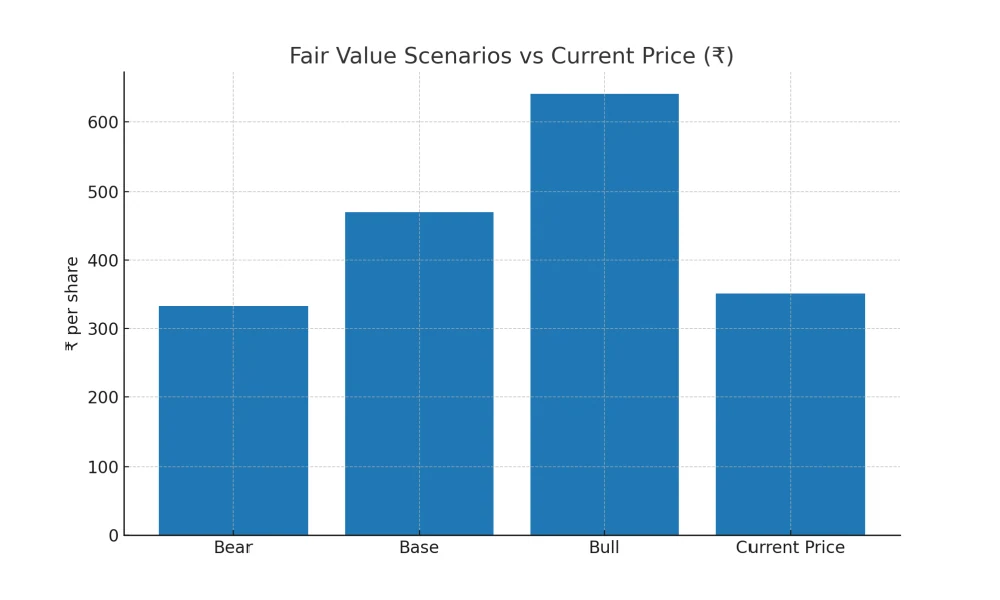
Base case fair value ~₹470/share; Bear case ₹333, Bull case ₹641. Current price ~₹351.
EV/EBITDA multiples: DCGL ~13x, Rallis 13x, India Pesticides 12x, Sumitomo 42x, Sharda 9x.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Sunday, 2 November 2025, 3:21 PM IST.

Indian agro sector experiencing bifurcation - Large players (PI, UPL) with diversified portfolios and export strength maintaining margins 18-28%; Mid-tier players (Dharmaj) struggling with 9-11% margins due to lack of pricing power and commodity product mix.

FIIs bought ₹45,960.02 cr of Indian equities this week — 615.28% above their 4-week average of -₹8,919.37 cr. Nifty rose 8.58% and closed at its weekly high, back above both its 25-week and 200-day averages. It did this while the S&P 500 fell 2.68%, the Nikkei 9.25% and Brent 16.42%.

Bearish Marubozu — A candlestick with no upper shadow and a minimal lower shadow. It signals relentless selling from open to close with zero buying recovery.