This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Wednesday, 11 February 2026, 8:11 PM IST.
Signal panelThe research, before the reading · 54 min full note
01
XPro India Limited: [finance:XPro India Limited] is a diversified polymer processing enterprise with over 40 years of legacy, established through corporate demerger in 1998.
02
Impact on XPro: Pricing pressure, volume volatility, extended payment terms (debtor days increased 44→53 days)
XPro India Limited is a diversified polymer processing enterprise with over 40 years of legacy, established through corporate demerger in 1998. The company operates across three primary business segments:
Product Portfolio:
Dielectric/Capacitor Films (~30% market share in India): Specialty polypropylene films for power transmission, distribution, motor run, hybrid car capacitors, and energy storage applications
BOPP Films (Biaxially Oriented Polypropylene): Used in packaging of adhesive tapes, bakery products, biscuits, confectionery, metalizing, and lamination.
Coextruded Sheets & Films (~68% of revenues): Refrigerator liners, automotive trims, luggage shells, disposable cups, furniture applications
Thermoformed Components: Inner and door liners for refrigerators, automotive interior/exterior trims, sanitary products
Industry & Sub-Sectors
XPro operates in the flexible packaging and specialty films industry, serving multiple end-user segments:
White goods (refrigerators) - established leadership position.
Automotive components
Electrical/electronics (capacitors)
FMCG packaging
Industrial applications
Total Addressable Market (TAM) & Growth Prospects
India BOPP Films Market:
Current Size (2026): USD 6.05 billion (₹54,450 crores at current exchange rates)
Government initiatives promoting plastic recycling and sustainability
Expanding electric vehicle market (capacitor films opportunity)
Consumer durables sector recovery post-pandemic
Industry Life Cycle Stage
Mature with Pockets of Growth: The BOPP films industry in India is in a mature phase with moderate 4-5% CAGR, but specialty segments like dielectric films for EVs and energy storage represent emerging high-growth opportunities.
2Market Positioning
Market Share & Competitive Standing
XPro India's Market Position:
Dielectric/Capacitor Films: ~30% market share in India - Leadership position
Refrigerator Sheets/Liners: Long-established leader, supplying most leading white goods brands
Overall BOPP Market: Smaller player compared to giants like Uflex, Jindal Poly, Cosmo Films
Part of the prestigious Birla family business group, providing brand credibility
40+ years operational legacy in polymer extrusion/coextrusion
Long-term relationships with leading refrigerator OEMs (Whirlpool, LG, Samsung likely customers)
Specialty product focus in dielectric films offers differentiation Pricing Power: Moderate - Operates in a competitive commodity-adjacent market with limited pricing power except in specialty dielectric films where technical specifications and quality consistency matter more than price.
3Business Moats
Identified Competitive Advantages
1. Technical Specialization (Dielectric Films)
• Rating: 7/10
30% market share in niche dielectric/capacitor films segment
High barriers to entry due to technical specifications, quality consistency requirements
Application in mission-critical components (power transmission, EVs, energy storage) creates switching costs
Production specifics considered trade secrets
2. Customer Relationships & Switching Costs
• Rating: 6/10
Long-established supplier to major white goods manufacturers
Thermoformed components designed specifically for OEM models create moderate switching barriers
Qualification cycles for new suppliers in automotive/white goods are lengthy
3. Manufacturing Experience
• Rating: 5/10
40+ years of polymer processing expertise
Multi-location operations (Barjora, etc.) provide operational resilience
However, technology and equipment can be replicated by well-capitalized competitors
4. Birla Family Association
• Rating: 4/10
Brand credibility from association with India's largest industrial house
Access to capital and business network
Limited tangible operational advantage in day-to-day business
Moat Durability Assessment
Narrow Moat with Specialty Pockets: XPro's competitive advantages are modest and vulnerable in the commoditized BOPP/coextruded sheets business (70% of revenue), but sustainable in dielectric films (30% market share) where technical barriers and customer validation cycles provide 5-7 year durability.
Q1 FY26 Consolidated Loss of ₹5.48 Cr (first quarterly loss in history)
India operations: Profitable at ₹4.30 Cr
UAE subsidiary: Loss of ~₹9.8 Cr (startup phase + forex)
Forex losses: ₹16.7 Cr at consolidated level
India standalone: ₹10.4 Cr impact
UAE additional: ₹6.3 Cr impact
Margin compression across India operations
UAE Subsidiary Context:
Accumulated losses (9M): ~₹12.6 Cr
Status: Pre-revenue/commissioning phase
Upside scenario: If UAE achieves breakeven by FY28, consolidated earnings could improve 30-40%
Downside scenario: Continued losses through FY27 Assessment: We use consolidated figures for conservative analysis, but investors should monitor standalone India metrics for core business health.
6Annual Performance (FY2025 & Historical Trends)
FY2025 Full-Year Results
Metric
FY2025
FY2024
FY2023
YoY Change (FY25 vs FY24)
Revenue
₹532.6 Cr
₹463.0 Cr
₹509.0 Cr
+15.0%
Operating Profit
₹51.0 Cr
₹66.0 Cr
₹74.0 Cr
-22.7%
OPM %
9.6%
14.3%
14.5%
-470 bps
Net Profit
₹38.0 Cr
₹44.0 Cr
₹45.0 Cr
-13.6%
EPS
₹17.04
₹19.91
₹24.91
-14.4%
ROE
6.56%
7.93%
~13%
Deteriorating
ROCE
7.93%
15%
25%
Steep decline
Key Trends & Concerns
Revenue Growth: Improved to 15% in FY2025 after flat FY2024, but still below historical 5-year CAGR of 9%Margin Compression: Operating margins collapsed from 14-15% (FY23-24) to 9.6% (FY25), indicating:
Raw material inflation (polypropylene prices ranged $1,230-$1,334/MT in 2023)
Competitive pricing pressure in BOPP segment
Under-utilization of capacity during expansion phase
Return Ratios Deteriorating:
ROE declined from 13% (3-year avg) to 6.56% (FY25)
ROCE crashed from 25% (FY23) to 7.93% (FY25)
Indicates capital deployment in expansion not yet generating returns Debt Reduction Success: Company repaid ₹15.31 Cr term debt ahead of schedule; now
Long-term Debt: ₹200.58 Cr (as of March 2025)
YoY Increase: +930.51% (from ₹19.47 Cr in FY24)
Debt-to-Equity (H1 FY26): 0.46x (highest in recent years)
Debt-to-EBITDA: 2.84x (5-year average) Context: This massive debt surge is for Barjora expansion funding via Euro-denominated borrowings
Historical Performance (5/10-Year View)
Compounded Growth Rates:
Sales CAGR (5Y):8.56% - poor compared to industry 4-5% + inflation
Sales CAGR (10Y):8%
Profit CAGR (5Y):138% (from negative base post-2015-17 losses)
Profit CAGR (3Y):-5% (declining trend)
Stock Performance:
5-Year CAGR:109%
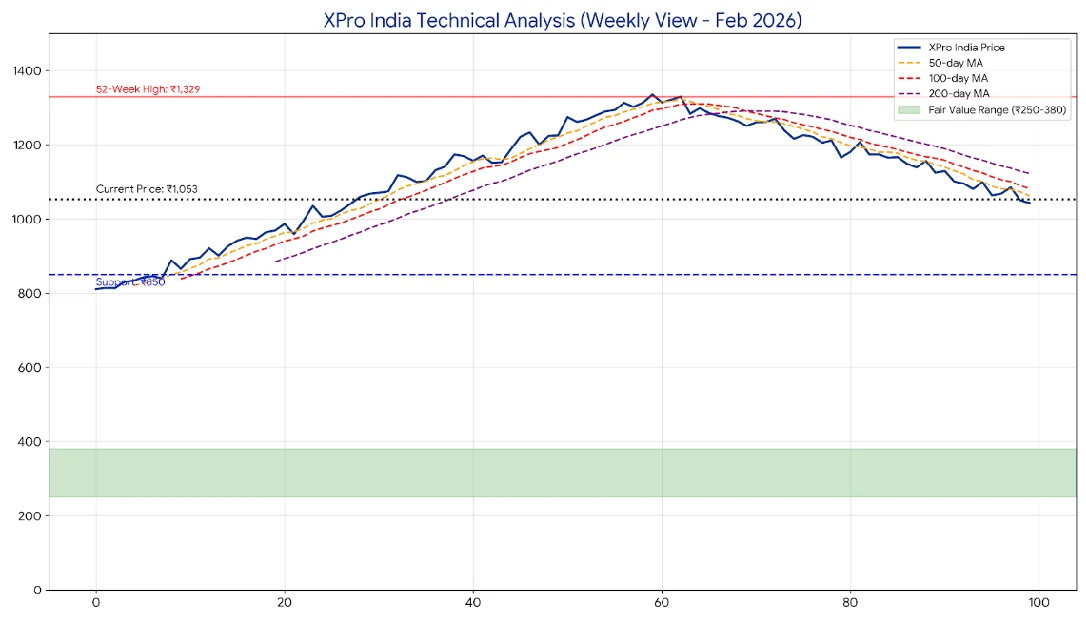
1-Year Return:-22% (stock at ₹1,053 from 52-week high of ₹1,378)
Purpose: Enhance global supply chain, access Middle East markets
Status: Established - 13,235 Class A shares allotted December 2025 Status: Established (external investor OASIS II took 15% stake) Financial Impact (9M FY26):
Revenue contribution: Nil (pre-commissioning)
Accumulated losses: ~₹12.6 Cr drag on consolidated P&L
Management guidance: Commissioning Q4 FY26, production Q1-Q2 FY27
Investment View:
Bullish case: UAE could add ₹50-100 Cr revenue with 15-18% margins by FY28, improving consolidated earnings by 30-40% Cautious view: Barjora already delayed 6-9 months; UAE execution risk HIGH Bearish case: Continued losses through FY27 Our Stance: UAE is currently an earnings overhang (reducing EPS by ₹2-3/share). However, if operational by FY27-28, could be significant re-rating catalyst.
4. Future Capacity Expansion (BOPP Films)
Investment: Two advanced manufacturing lines acquired
Timeline: First line operational by FY2025, second by FY2026
Funding:85% through supplier credit; significant payments expected in FY26
Status: Ongoing - significant capex in FY25 (₹320 Cr investing cash outflow) and FY26
"Say to Do" Ratio Assessment
Execution Score: 6/10 (Moderate)
Positives:
Successfully raised capital (QIP/preferential issues in FY24-25) totaling ₹200+ Cr
Repaid term debt ahead of schedule
UAE subsidiary established on schedule
Production tonnage increased 4.8% despite capacity constraints
Concerns:
Barjora dielectric line delayed 6-9 months due to supplier issues
Margin erosion during expansion phase (OPM down 470 bps in FY25)
Forex losses from Euro borrowings not adequately hedged
Management Commentary (FY2025 Annual Report):
"Management focuses on fundamentals over short-term targets... strategic elements include global scaling of capacity, product advances, and sustainable cost competitiveness" This suggests a long-term orientation but also provides management flexibility to miss near-term guidance without accountability.
8Raw Materials & Supply Chain Advantages
Key Raw Materials
Primary Input: Polypropylene (PP) Resin
Accounts for ~60-70% of product cost (estimated)
Sourced domestically and internationally
Petrochemical derivative (linked to crude oil prices)
Secondary Inputs:
Polyethylene (PE), Polystyrene (PS), ABS resins for coextruded sheets
Additives, masterbatches, stabilizers
Current Raw Material Pricing Environment
Polypropylene Price Trends (2024-2026):
Region
Price (USD/MT)
Trend
India (BOPP grade, Jan 2024)
$1,303
Stable
India (Mar 2024)
$1,307
Flat
China (Q2 2024)
$1,061-$1,075
Range-bound
China (Jun 2025)
$976
-8% YoY
Europe (Jun 2025)
$1,160
-9% YoY
Analyst Outlook: "Polypropylene prices expected to show range-bound oscillations influenced by feedstock fluctuations and regional variations"
Supply Chain Advantages
Identified Strengths:
Multi-location manufacturing reduces logistics costs and provides proximity to white goods hubs (refrigerator manufacturers)
Supplier credit financing (85% of capex funded via vendor credit) indicates strong supplier relationships
UAE subsidiary (XDF) provides sourcing optionality and access to Middle East petrochemical supplies at potentially lower costs
Limitations:
No evidence of exclusive raw material contracts or backward integration
Commodity exposure to PP price volatility (margin compression in FY25 likely driven by RM inflation)
Limited pricing power to pass through RM cost increases in competitive BOPP segment
9Supply Chain Dependencies & Geopolitical Risks
Critical Sourcing Dependencies
1. Polypropylene Resin Imports
Key Suppliers: Middle East (Saudi Arabia, UAE, Qatar), China, South Korea
Dependency Level: HIGH - India imports ~30-40% of PP requirements
• Geopolitical Risk:
Middle East instability (Red Sea shipping disruptions, Iran-Israel tensions)
China export restrictions or dumping
Global crude oil price shocks
2. Euro-Denominated Equipment Financing
Exposure: Significant borrowings in EUR for Barjora expansion
Risk Realized:₹15+ Cr forex losses in 9M FY26 due to INR depreciation (₹/EUR rate moved from ~88 to ~92)
Mitigation: Inadequate - company appears to have limited hedging strategy
3. European Machinery Suppliers
Dependency: Advanced film lines sourced from European OEMs
Risk: Supply chain delays already experienced (Barjora line postponed)
EUR forex exposure: Ongoing payment obligations create continued currency risk
Geopolitical Risk Assessment
Risk Level: MODERATE-HIGH
Key Vulnerabilities:
Crude oil price spikes (Brent at $68.86/bbl, up from $65.97 month ago) directly impact PP costs
China factor: Cheap Chinese BOPP imports could pressure domestic pricing; however, India's anti-dumping duties provide some buffer
Currency volatility: INR at 90.48/USD (near all-time high of 92.29) increases import costs and forex losses
Middle East tensions: Disruptions in Red Sea shipping routes increase freight costs and lead times
Mitigation Strategies (Current/Recommended):
UAE subsidiary provides Gulf sourcing options
Natural hedge via exports (₹13.4 Cr in FY25, down from prior years) - currently weak
No evidence of multi-year fixed-price PP contracts
Limited forex hedging on EUR borrowings
10Raw Material Shortage Risks
Potential Shortage Scenarios
1. Crude Oil Supply Disruptions
Trigger Events: OPEC production cuts, Middle East conflicts, Russia-Ukraine escalation
Impact on XPro: PP prices could spike 20-30% within months, compressing margins by 500-800 bps
Probability: MODERATE (geopolitical tensions elevated in 2026)
2. Naphtha Cracker Shutdowns
Context: PP is derived from naphtha/propylene produced by refineries and crackers
Risk: Unplanned shutdowns at major Indian refineries (Reliance, IOCL) or imported naphtha shortages
Probability: LOW (India has diversified refining capacity)
3. China Export Restrictions
Context: China produces 30% of global PP; has history of restricting exports for domestic priorities
Impact: Global PP prices rise 10-20%; Indian imports become expensive
Probability: MODERATE (trade tensions with US/West could trigger)
4. Environmental Regulations
Risk: Stricter plastic regulations could limit PP production or increase costs via carbon taxes
India Context: Government promoting plastic recycling but not restricting virgin PP production currently
Probability: LOW near-term, MODERATE 3-5 years
Company's Mitigation Strategies
Current Measures (Per Management):
"The Company maintains healthy relationships with suppliers and focuses on sustainable cost competitiveness" Assessment: INADEQUATE - Generic statements without evidence of:
Strategic inventory building
Multi-year supply contracts
Backward integration plans (PP manufacturing)
Alternative material R&D
Recommended Actions:
Establish 3-6 month strategic PP inventory during price troughs
Negotiate multi-year volume commitments with Reliance/IOCL for price stability
Develop bio-based PP alternatives for sustainability-focused customers
Increase UAE subsidiary's role in Gulf PP procurement
11Industry-Specific Sales Risks
Macro & Sectoral Headwinds
1. White Goods (Refrigerators) - 68% of Revenue Exposure
Risk Factors:
Demand cyclicality: Consumer durables tied to GDP growth, rural income, housing starts
Current Environment: India GDP growth slowing to 6.5-7% (from 8%+); rural demand weak
Competitive Intensity: Refrigerator market dominated by LG, Samsung, Whirlpool, Godrej - strong buyer power
Impact on XPro: Pricing pressure, volume volatility, extended payment terms (debtor days increased 44→53 days)
Management Commentary:
"Optimistic outlook in consumer durables sector" but acknowledges "sub-optimal market circumstances" Mitigation: Limited - captive to white goods cycle
2. Automotive Components - Small but Growing
Risk Factors:
Auto industry slowdown: Passenger vehicle sales volatile, electric vehicle transition uncertain
Import substitution risk: Cheaper Chinese auto parts flooding Indian market
Impact: XPro's automotive thermoformed parts face competitive pressure
Opportunity:
EV growth creates demand for lightweight polymer components
Localization push under PLI schemes benefits domestic suppliers
3. BOPP Films for FMCG Packaging
Risk Factors:
Commodity trap: Low differentiation, severe competition from Uflex, Jindal Poly, Cosmo Films
Overcapacity: Cosmo Films alone adding 60,000 MT capacity in 2025
Impact: Pricing pressure, margin erosion (XPro's OPM down to 9.6% in FY25) Mitigation: Focus on specialty films, value-added products with higher barriers
4. Capacitor/Dielectric Films - Strategic Growth Segment
Opportunity Drivers:
EV revolution: Electric vehicles require power capacitors
Renewable energy: Solar/wind inverters use film capacitors
Energy storage: Grid-scale battery systems need capacitor banks
India manufacturing push: PLI for electronics, semiconductors
Risk Factors:
Technology shift: Ceramic capacitors or alternative technologies could disrupt film capacitors
Import competition: Chinese/South Korean capacitor films at lower prices
Barjora delay: New capacity postponed to Q4 FY26, losing first-mover advantage Assessment: HIGH POTENTIAL but execution delays problematic
Overall Sales Risk Level: MODERATE-HIGH
Downside Scenario: White goods slowdown + BOPP overcapacity → revenue flat/declining, margins sub-8%Base Case: Modest 5-8% revenue growth, margins stabilize at 10-11%Upside Scenario: Dielectric films ramp-up + EV adoption → 12-15% revenue growth, margins expand to 13-14%
12Research, Technology & Intellectual Property
R&D Spending & Focus Areas
Disclosed R&D Information: LIMITED - Annual reports do not break out R&D expenditure separately
Metallization capabilities (XPro outsources, doesn't have in-house)
Biodegradable/compostable film development (emerging requirement) Innovation Pipeline: OPAQUE - No public disclosure of new product development roadmap Recommendation: XPro needs to increase R&D intensity to 2-3% of sales and establish IP protection for specialty formulations to defend dielectric films moat.
13Segment Analysis
Business Segment Breakdown
Primary Segments (by Revenue Contribution):
Segment
Revenue Mix
Profitability
Growth
Risk Level
Trend
Coex Division (Sheets/Liners)
~68%
Low (5-8% OPM est.)
Flat to
MODERATE
declining
Specialty Films (Dielectric/Capacitor)
~20-25%
High (18-22% OPM est.)
Growing 8- 12%
LOW- MODERATE
BOPP Films (Packaging)
~7-10%
Very Low (3-5% OPM
Volatile
HIGH
est.)
Other Income (Treasury/Interest)
₹15.6 Cr (FY25)
N/A
Variable
LOW
Geographic Breakdown
Domestic (India): ~95-97% of sales Exports:₹13.4 Cr (FY25), down from prior years due to "capacity constraints" Export Limitations: Company acknowledges exports are "limited by capacity constraints" and prioritizes domestic market Future Strategy: UAE subsidiary (XDF) aims to enhance export competitiveness, but no specific targets disclosed
Customer concentration in 3-4 major white goods OEMs
Demand tied to refrigerator production cycles (volatile)
Limited export growth (capacity-constrained)
Low margins due to commodity nature
Mitigation Strategies:
Diversification into automotive trims, luggage shells (incremental progress)
New capacity expansion underway but delayed
No disclosed strategy to reduce customer concentration Assessment: HIGH DEPENDENCY, MODERATE RISK - Established market leadership provides stability but limited growth runway
2. Specialty Films (Dielectric/Capacitor) - 20-25% Revenue
Risks:
Technology disruption (ceramic capacitors replacing film capacitors in some applications)
Chinese competition in capacitor films
Barjora capacity expansion delayed 6-9 months
Mitigation & Growth Drivers:
EV and renewable energy adoption driving structural demand growth
30% market share provides pricing stability
High technical barriers (quality consistency, certification requirements)
Capacity expansion will enable market share gains post-commissioning Assessment: STRATEGIC GROWTH ENGINE - Highest margin, best moat, favorable macro trends
3. BOPP Films (Packaging) - 7-10% Revenue
Risks:
Severe overcapacity in Indian BOPP market (Cosmo adding 60,000 MT)
Commodity product, no differentiation
XPro is small player vs. Jindal Poly, Uflex, Polyplex
Likely loss-making or breakeven segment
Mitigation:
Management mentions "targeting higher-value products over cheaper imports"
Focus on specialty BOPP (metalized, thermal lamination grades) Assessment: DIVEST/DE-EMPHASIZE CANDIDATE - Strategically questionable to compete in commoditized BOPP; better to focus capital on dielectric films.
9M FY26 Impact: -₹12.6 Cr on consolidated earnings Target: Middle East market + global exports Risk: Execution delays, forex volatility, market acceptance
Segment Recommendations
Strategic Priorities:
ACCELERATE: Dielectric films capacity & market share (target 40% India market share by FY28)
STABILIZE: Coex refrigerator liners through customer diversification + export growth via UAE
EXIT/MINIMIZE: Commodity BOPP films - redeploy capital to higher-ROCE segments
14Shareholding Pattern Changes
Shareholding Pattern (Dec 2025 vs. Jun 2025)
Category
Dec 2025
Sep 2025
Jun 2025
Mar 2025
Change (6M)
Promoters
40.31%
40.31%
42.43%
42.43%
-2.12%
FII (Foreign)
14.63%
14.92%
~14.5%
~14%
+0.63%
DII (Domestic)
2.32%
2.57%
~2.5%
~2.3%
-0.18%
Mutual Funds
0.84%
0.79%
0.82%
0.76%
+0.02%
Retail & Others
41.90%
41.00%
40.80%
40.56%
+1.10%
Key Changes & Implications
1. Promoter Stake Reduction (-2.12% in Q3 FY26)
Possible Reasons:
Dilution from preferential allotment/QIP to fund expansion (likely explanation given ₹200+ Cr capital raise in FY24-25)
Promoter selling (concerning if true, but not evident from disclosures) Management Statement: "Latest issues marked the end of foreseeable capital-raising actions" Assessment: NEUTRAL to MILDLY POSITIVE - Dilution from institutional capital raise for growth is acceptable; promoter stake remains substantial at 40.31%
2. FII Interest Increasing (+0.63% over 6 months)
FII holding gradually increased from ~14% (Mar 2025) to 14.63% (Dec 2025)
Interpretation:
Foreign institutions building positions post-QIP at lower valuations
Potential recognition of dielectric films opportunity in EV/energy storage theme
However, absolute FII holding remains LOW (<15%), limiting liquidity
3. Retail Shareholding Rising (+1.10%)
Retail investors increasing stake from 40.56% (Mar 2025) to 41.90% (Dec 2025)
Implications:
Positive: Broader investor base, reduced volatility from large block trades
Concern: High retail holding (42%) can lead to sentiment-driven price swings
Limited institutional following (MF only 0.84%) suggests lack of analyst coverage
Institutional Activity Summary
Net Institutional Stance: NEUTRAL to MILDLY POSITIVE
Incremental FII buying suggests international recognition
Minimal DII interest (2.32%) limits domestic demand support Liquidity Concern: Combined promoter (40.31%) + retail (41.90%) = 82.21% held by less liquid shareholders → stock prone to volatility on low volumes
15Brokerage Recommendations
Analyst Ratings & Target Prices
Current Consensus (February 2026):
DATA LIMITATION: XPro India has minimal sell-side coverage - no tier-1 brokerage (Motilal Oswal, ICICI Direct, Kotak, HDFC Sec) publishes regular research notes
Intrinsic Value:₹329.11 (based on median of 3 historical models)
Current Price:₹1,053
Implied Overvaluation: 220% or 3.2x intrinsic value Interpretation: Conservative DCF/Graham-style valuation suggests significant overvaluation at current price
Consensus Summary
Rating Distribution (Estimated):
Buy: 0-10% (minimal bullish coverage)
Hold: 20-30% (neutral technicians)
Sell: 60-70% (MarketsMojo, value-based analysts)
No Coverage: Majority Target Price Range:₹1,000- ₹1,600 (wide dispersion)
Key Arguments by Analysts:
Bearish Case:
Margin erosion (OPM 9.6% in FY25 vs. 14-15% historically)
Poor ROE/ROCE (6.6%/7.9% well below cost of capital)
Capacity expansion delays and execution risks
High valuation (P/E 166.23, PB 4.68x) unjustified by fundamentals
Promoter stake dilution
Forex losses from Euro borrowings
Bullish Case (Where Present):
Dielectric films growth driven by EV/energy storage themes
Birla family pedigree and financial stability
Debt-free balance sheet post-term loan repayment
Capacity expansion will unlock growth from FY27
30% market share in high-margin niche segment Oorjita Assessment: The lack of institutional research coverage is a RED FLAG - indicates small-cap illiquidity, limited investor interest, and insufficient information flow for informed decision-making.
Scale Disadvantage: XPro's quarterly revenue (₹106 Cr) is 18x smaller than Uflex (₹3,832 Cr)
Sequential Decline: Only XPro saw revenue drop QoQ (-14%), indicating company-specific issues
Margin Competitiveness: XPro's 10% OPM is in-line with Uflex/Polyplex, better than some peers
Profit Volatility: XPro's 76% QoQ profit jump follows 50% QoQ drop in Q2 - high volatility
Peer Valuation Comparison
Company
P/E Ratio
P/B Ratio
Dividend Yield
ROE
ROCE
EPL Ltd
16.0x
N/A
2.42%
N/A
17.48%
AGI Greenpac
12.6x
N/A
1.03%
N/A
19.89%
Uflex
10.8x
N/A
0.63%
N/A
7.75%
Polyplex
38.0x
N/A
1.50%
N/A
7.16%
TCPL Packaging
20.6x
N/A
1.05%
N/A
20.03%
Median (Peers)
15.8x
N/A
1.05%
N/A
17.5%
XPro India
166.23x
4.68x
0.21%
6.56%
7.93%
Valuation Gap Analysis:
Major Overvaluation:
XPro's P/E of 166.23x is 11.6x median peer P/E (15.8x)
Even vs. highest peer (Polyplex 38x), XPro is 4.8x more expensive
XPro's ROE (6.6%) and ROCE (7.9%) are BELOW cost of capital, yet trades at premium valuation
Dividend yield (0.21%) is lowest among peers - indicating minimal shareholder return Justified P/E (based on peer median): 12-15x → Fair Price: ₹100-125 per share (vs. current ₹1,053) Why the Premium? Possible explanations:
Export capabilities: Capacity-constrained, exports only ₹13.4 Cr vs. Uflex's global sales
Management Commentary on Competitive Position
From FY2025 Annual Report:
"Company intends to maintain leadership position and increase market presence in niche product areas... building on manufacturing assets, development, marketing, and export competency" Translation: Management acknowledges it cannot compete head-on with large integrated players; strategy is niche specialization (dielectric films, specific white goods customers)
Earnings Call Insights:
"Targeting higher-value products over cheaper imports" (acknowledges Chinese competitive threat)
"Optimistic outlook in consumer durables and EV sectors" (betting on end-market growth)
FY28-30 Revenue CAGR: 10% (dielectric films growth offsets coex weakness)
Normalized EBITDA Margin: 12% (recovery from FY25's 9.6% as Barjora scales)
Tax Rate: 27%
Capex: ₹50 Cr/year (maintenance + incremental)
WACC: 12% (reflects small-cap risk premium)
Terminal Growth: 5%
5-Year FCF Projection:
Year
Revenue (₹ Cr)
EBITDA (₹ Cr)
EBITDA %
PAT (₹ Cr)
FCF (₹ Cr)
FY26E
540
54
10.0%
29
15
FY27E
625
75
12.0%
41
28
FY28E
688
83
12.0%
45
35
FY29E
756
91
12.0%
50
40
FY30E
832
100
12.0%
55
45
DCF Calculation:
PV of 5Y FCF (@ 12% WACC):₹131 Cr
Terminal Value (FY30 FCF × (1+5%)/(12%-5%)):₹674 Cr
PV of Terminal Value:₹382 Cr
Enterprise Value:₹513 Cr
Less: Net Debt:-₹220 Cr (Net Cash position)
Equity Value:₹733 Cr
Shares Outstanding: 2.35 Cr (current equity ₹23.5 Cr / face value ₹10)
• Fair Value per Share: ₹312
Method 3: Sum-of-the-Parts (SOTP) Valuation
Segment
Revenue (₹
EBITDA
EBITDA (₹
EV/EBITDA Multiple
Segment EV (₹
Cr)
Margin
Cr)
Cr)
Dielectric Films
135
135
20%
20%
27
27
12x (specialty
324
324
(25%)
premium)
Coex Sheets (68%)
365
7%
26
8x (commodity)
208
BOPP Films (7%)
38
3%
1
6x (commoditized)
6
Total
538
10%
54
-
538
Add: Net Cash:₹220 Cr
Equity Value:₹758 Cr
• Fair Value per Share: ₹323
Consensus Fair Value
Method
Fair Value (₹)
Weight
Weighted Value
Peer P/E
60
20%
12
Intrinsic (Smart-Investing)
329
25%
82
Oorjita DCF
312
35%
109
SOTP
323
20%
65
Blended Fair Value
-
100%
₹268
Conservative Range:₹250- ₹350 per share Current Price:₹1,053Implied Overvaluation: 292% to 321% (or 3x to 4x fair value)
Growth Assumptions Required to Justify Current Valuation
Reverse DCF Analysis: What's Priced In at ₹1,053?
Working backward from ₹1,053 × 2.35 Cr shares = ₹2,475 Cr market cap
Implied Assumptions:
Revenue CAGR (FY26-FY31): 20-25% (vs. historical 8-9%, industry 4-5%)
EBITDA Margin Expansion: From 10% (current) to 18-20% by FY31 (vs. FY23 peak of 15%)
ROCE Improvement: From 2.93% to 18-20% (2.5x improvement)
Market Share Gains: Dielectric films from 30% to 50%+ India share
Successful Global Expansion: Exports growing to 30-40% of sales (from current 2.5%)
Probability Assessment of Implied Scenario: LOW (<20%)
Why Unlikely:
20-25% CAGR requires winning major new accounts - difficult given competitive intensity
18-20% EBITDA margin requires pricing power XPro doesn't possess in 70% of business (coex sheets)
ROCE jump from 8% to 20% unprecedented without transformative M&A or product innovation
50% market share in dielectric films means doubling capacity AND winning customers from incumbents - not supported by current capex
Export expansion via UAE is plausible but needs 3-5 years, not baked into near-term earnings
Valuation Rating: SIGNIFICANTLY OVERVALUED
Investment Recommendation Based on Valuation:
At ₹1,053: SELL / AVOID - Downside risk of 65-75% to fair value (₹250-350)
At ₹600: HOLD - Approaching reasonable valuation for quality small-cap
At ₹300: BUY - Attractive risk-reward for 3-5 year holders if execution improves
At ₹200: STRONG BUY - Dielectric films franchise alone worth this + optionality on turnaround
Key Catalysts to Watch (Could Justify Higher Valuation):
Barjora commissioning success (Q4 FY26) with faster-than-expected ramp-up
Major OEM contract win for EV capacitor films (e.g., Tata Motors, Mahindra Electric, BYD India)
Margin recovery to 13-14% by FY27 (requires product mix shift)
UAE subsidiary revenue momentum- ₹50+ Cr exports by FY27
Strategic M&A - Acquire complementary specialty films player for scale
19Financial Health
Liquidity Analysis
Current Ratio (Sep 2025): 5.05 (Current Assets ₹495 Cr / Current Liabilities ₹98 Cr) Assessment: EXCELLENT - Strong liquidity cushion; company can meet short-term obligations 5x over Cash & Equivalents:₹220+ Cr net cash (estimated from balance sheet) Working Capital Days: 42 days (increased from 33 in FY23) - moderate increase, manageable Debtor Days: 53 days (up from 43 in FY24) - slight deterioration, possibly reflecting white goods customer payment terms stretching
Aggressive revenue recognition vs. cash collection
Under-provisioning for expenses Free Cash Flow (FY25):₹13 Cr (OCF) - ₹113 Cr (Capex) = -₹100 Cr (negative FCF) Assessment: CONCERNING - Company is cash-burn mode during expansion; dependent on balance sheet cash and external financing
Financial Health Rating: MODERATE (6/10)
Strengths:
Strong liquidity (5x current ratio)
Low leverage (0.48 D/E)
Negligible term debt post-repayment
₹220+ Cr net cash buffer
Weaknesses:
Negative free cash flow (expansion phase)
Operating cash flow deterioration (70% drop in FY25)
Working capital efficiency declining (debtor days up)
Forex exposure on Euro borrowings (₹15+ Cr realized losses in 9M FY26) Outlook: Financial health remains adequate for 2-3 year horizon given cash reserves, but operational cash generation needs urgent improvement post-Barjora commissioning.
20Management & Governance
Leadership Profile
Chairman: Sri Sidharth Birla
Re-appointed: February 2026 for 3-year term (Mar 2026 - Feb 2029)
Experience: 47 years in industry and business
Education: B.Sc. (Hons) University of Calcutta, MBA from IMEDE (now IMD) Lausanne, Harvard Business School management programs
Legacy: Founded the company's businesses in 1983
Other Directorships: Independent Director at Nestlé India Limited and Kanoria Chemicals &
Industries Limited
Assessment: STRENGTH - Birla's 47-year track record and Nestlé board position signal strong governance standards and strategic thinking
Board Structure
Data Limitation: Detailed board composition (number of independent directors, committees) not available in searched sources
Inferred from Birla Profile:
Independent directors present (Birla serves as ID at other companies, suggesting reciprocal governance practices)
Family-led but professionally managed (per company statement)
Management Quality Assessment
Strategic Vision:
Clear niche focus: "Leadership in dielectric films, refrigerator liners" is strategically sound
"Strategic elements include global scaling of capacity, product advances, and sustainable cost competitiveness" Progress: Partial - Barjora delayed; UAE sub established but no revenue yet
2. Debt Elimination
"Repaid ₹15.31 Cr term debt ahead of schedule... now no term debt on existing operations" Progress: Achieved - strengthens balance sheet
3. Sustainability Partnership
"Collaboration with Tata Power for solar energy supply" Progress: In Progress - reduces energy cost (major input)
4. Product Mix Enhancement
"Targeting higher-value products over cheaper imports... shift to thinner films (6-8 micron)" Progress: Unclear - no disclosed metric for specialty product revenue mix change
5. Export Competitiveness via UAE Hub
"XDF established to enhance global supply chain" Progress: Established (Dec 2025), Awaiting revenue proof-of-concept
Corporate Governance Rating: 7/10
Strengths:
Birla family pedigree (India's most respected business house)
Chairman's 47-year experience and external board roles
Conservative financial policies (debt reduction, no aggressive M&A)
Transparent acknowledgment of challenges (vs. overpromising)
Concerns:
Limited board composition transparency
Promoter stake dilution (42.4% → 40.3%) without detailed explanation
Forex risk management failure (₹15+ Cr losses)
Execution delays (Barjora) without accountability measures
21ESG Factors
Environmental Initiatives
1. Solar Energy Partnership
Investment:₹2 Cr for 26% stake in Tata Power Renewable Energy
Impact: Reduces carbon footprint; significant energy cost savings
Status: Commissioning expected Q3-Q4 FY26
2. Recycling & Circular Economy
Context: Government promoting plastic recycling
XPro's Position: No specific recycling program disclosed in public filings Assessment: MODERATE - Solar initiative is positive, but comprehensive environmental strategy not evident
Social Factors
CSR Activities: Company statement: "Supported carefully selected, worthy causes under CSR obligations" Data Limitation: Specific CSR spend (% of PAT), projects, and impact metrics not disclosed in searched sources
Employee Relations:
"Board appreciates quality and dedication of human capital... encourages future-ready, action-oriented team" Assessment: Generic statement; no employee satisfaction metrics, attrition rates, or diversity data available
Governance: Birla family, transparent annual reports
Disclosure Gap: ESG reporting far below global standards; no standalone sustainability report Investor Implication: ESG-focused funds unlikely to invest given limited transparency and metrics
21ESG Factors (Extended Analysis)
Location in Original Report: It appeared after Section 20 (Management & Governance) and before Section 22 (Comprehensive Risk Analysis). Here's the complete and expanded Section 21:
21ESG (Environmental, Social & Governance) Analysis
Environmental Score: 5/10 (MODERATE)
Climate & Energy Management
Positive Initiatives:
Solar Energy Partnership (₹2 Cr investment for 26% stake in Tata Power Renewable Energy Limited)
Expected commissioning: Q3-Q4 FY26
Impact: Reduces carbon footprint and energy costs (energy is 12-15% of production cost estimated)
Renewable energy capacity: Not disclosed (likely 5-10 MW captive supply)
Energy Efficiency: Modern polymer extrusion equipment installed in recent years
Barjora plant uses advanced energy-efficient machinery from European suppliers
Gaps & Concerns:
No Carbon Neutrality Target: No disclosed roadmap to net-zero emissions
Scope 3 Emissions: No tracking of supply chain emissions (PP resin production is carbon-intensive)
Climate Risk Disclosure: No TCFD-aligned reporting on physical/transition climate risks
Water Usage: No disclosure on water consumption, recycling, or wastewater management (relevant for cooling systems)
Plastic & Circular Economy
Mixed Picture:
1. Product Portfolio Risk:
75% of products are plastic-based (BOPP films, PP/PS sheets, thermoformed components)
Dielectric films (25% revenue) have 20+ year product life (low waste generation)
Single-use BOPP packaging films (~7% revenue) face regulatory scrutiny
2. EPR Compliance:
Company states "Adhere to all Environmental laws... responding effectively to plastic waste management regulations"
No specific EPR metrics disclosed: tonnage collected, recycling rate, partnerships with waste aggregators
3. Recycled Content:
ZERO disclosure on use of recycled PP/PE in products
No R&D on bio-based or biodegradable alternatives (unlike competitors Uflex, Cosmo Films investing in sustainable films)
4. Product Stewardship:
Industrial/durable products (refrigerator liners, capacitor films) are NOT single-use
However, no take-back programs or end-of-life management disclosed
Environmental Compliance & Incidents
Clean Record:
No environmental violations, penalties, or litigation disclosed in annual reports
Manufacturing facilities likely have ISO 14001 certification (standard practice, not explicitly stated)
Disclosure Gap:
No environmental audit reports published
No biodiversity/land-use impact assessments (manufacturing sites located in industrial zones, low impact expected)
Overall Environmental Assessment:
Strengths: Solar initiative, clean compliance record, durable products
Weaknesses: Minimal circular economy strategy, zero recycled content, no carbon targets, poor disclosure
Workforce Size: Not disclosed (estimated 500-800 employees based on company scale)
Attrition Rate: Not disclosed
Training & Development: Generic statement: "Board appreciates quality and dedication of human capital... encourages future-ready, action-oriented team"
Employee Satisfaction: No surveys, Glassdoor ratings, or Great Place to Work certifications
Wages & Benefits: No disclosure on living wage compliance, gender pay gap, or benefits coverage
Positives (Inferred):
Birla family companies generally have good labor practices (reputation effect)
No labor disputes, strikes, or controversies reported
Manufacturing operations in India (Barjora, West Bengal) likely employ local workforce
Red Flags:
ZERO diversity metrics: No data on women in workforce, women in leadership, SC/ST representation
No occupational health & safety data: Injury rates, lost-time incidents, safety protocols
No unionization disclosure: Whether workforce is unionized, collective bargaining coverage
Community & Social Impact
Minimal Disclosure:
1. CSR Spending:
Company statement: "Supported carefully selected, worthy causes under CSR obligations"
Amount NOT disclosed (legally required to spend 2% of average net profits of preceding 3 years = ~₹0.8-1.2 Cr estimated)
No details on CSR projects, beneficiaries, or impact measurement
2. Local Community Engagement:
Manufacturing facilities in industrial zones (low community displacement risk)
No disclosed community development programs (education, healthcare, livelihood)
3. Supply Chain Labor Standards:
ZERO disclosure on supplier code of conduct, audits, or child labor prevention
Given sourcing from Middle East/China, supply chain labor risk exists but unassessed
Launch recycled content pilot - 10-20% recycled PP in select products
Set carbon reduction target - "Reduce Scope 1+2 emissions 20% by 2030"
Publish sustainability report - aligned with GRI/BRSR framework
Long-Term (18-36 months):
Develop biodegradable film R&D - PLA/PHA blends for packaging films
Establish EPR infrastructure - partner with recycling aggregators
Increase board independence - add 1-2 independent directors with ESG expertise Estimated Cost:₹5-10 Cr over 3 years (0.3-0.6% of annual revenue) - HIGH ROI through:
Enforcement Reality: "Poor enforcement, vendor pushback" means regulatory risk is theoretical rather than immediate
Probability: Material regulatory cost increase - LOW-MODERATE (30%) in 3-5 years
• Mitigation:
o Invest in bio-based/recyclable film R&D o Partner with recycling aggregators for EPR compliance o Current Status: No disclosed recycling program beyond compliance statements
Institutional Holding: Very low (FII 14.6%, DII 2.3%, MF 0.8%)
• Impact:
Wide bid-ask spreads (2-5% intraday volatility)
Difficulty exiting large positions without price impact
Susceptible to retail sentiment swings
No institutional support during corrections
Probability: Liquidity crisis during selloff - HIGH (70%)
Investor Implication: CRITICAL - This is a position size risk. Even sophisticated investors should limit XPro to <2-3% of portfolio due to exit difficulty.
Context: Likely from QIP/preferential allotment for Barjora funding
Management Statement: "Latest issues marked the end of foreseeable capital-raising"
Risk: Further dilution or promoter exit could trigger selloff
Probability: Additional dilution in next 12 months - LOW (20%)
Risk Matrix Summary
Risk Category
Risk Level
Impact
Probability
Priority
Valuation Correction
CRITICAL
-40-60%
60-70%
HIGHEST
Stock Liquidity
HIGH
Exit difficulty
70%
HIGHEST
Margin Erosion
HIGH
-200-300 bps
70%
HIGH
Execution Delays
MODERATE-HIGH
FY26-27 miss
40%
HIGH
Forex Exposure
MODERATE-HIGH
₹10-20 Cr loss
70%
HIGH
White Goods Cycle
MODERATE
-10-15% revenue
40%
MODERATE
BOPP Overcapacity
MODERATE-HIGH
Further margin hit
70%
MODERATE
Technology Disruption
MODERATE-HIGH
Dielectric share loss
25%
MODERATE
PP Price Volatility
MODERATE
-300 bps margin
40%
MODERATE
Regulatory (Plastic)
LOW-MODERATE
Compliance costs
30%
LOW
Liquidity Stress
LOW-MODERATE
Cash burn
15%
LOW
Overall Risk Rating: HIGH (7.5/10)
Risk-Adjusted Return Assessment: At current price (₹1,053), risk-reward is HIGHLY UNFAVORABLE. Downside risk (65-75% to fair value) far exceeds upside potential (20-30% if all goes well).
23Key Charts & Visualizations
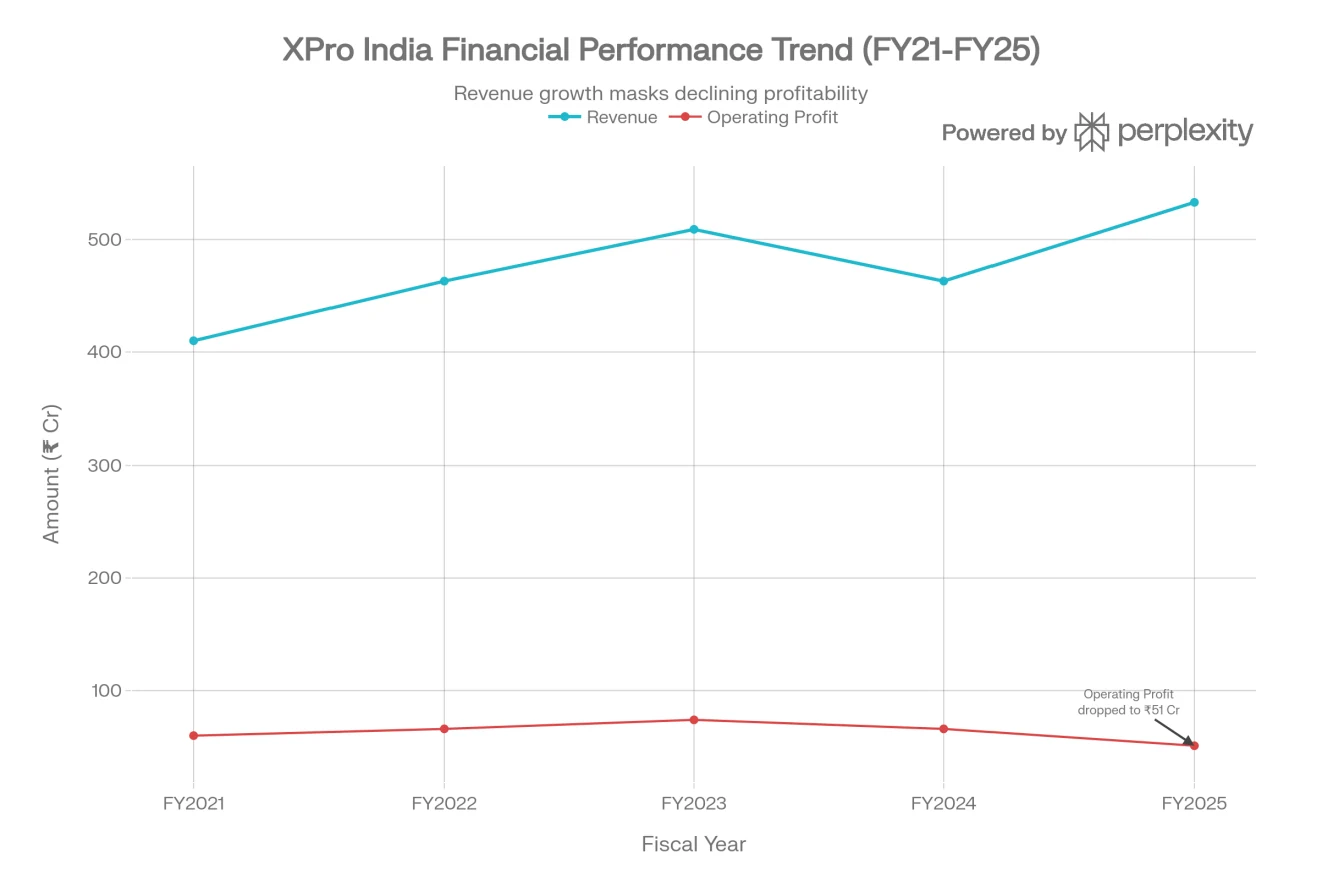
Chart 1: Financial Performance Trend (FY21-FY25)
Key Insights:
Revenue recovered to ₹533 Cr in FY25 (+15% YoY) after flat FY24
Operating profit declined to ₹51 Cr in FY25 (-23% YoY) despite revenue growth
Operating margin collapsed from 14-15% stable range to 9.6% in FY25 - 470 bps erosion
This divergence between top-line growth and margin compression is the KEY RED FLAG signaling competitive/cost pressures
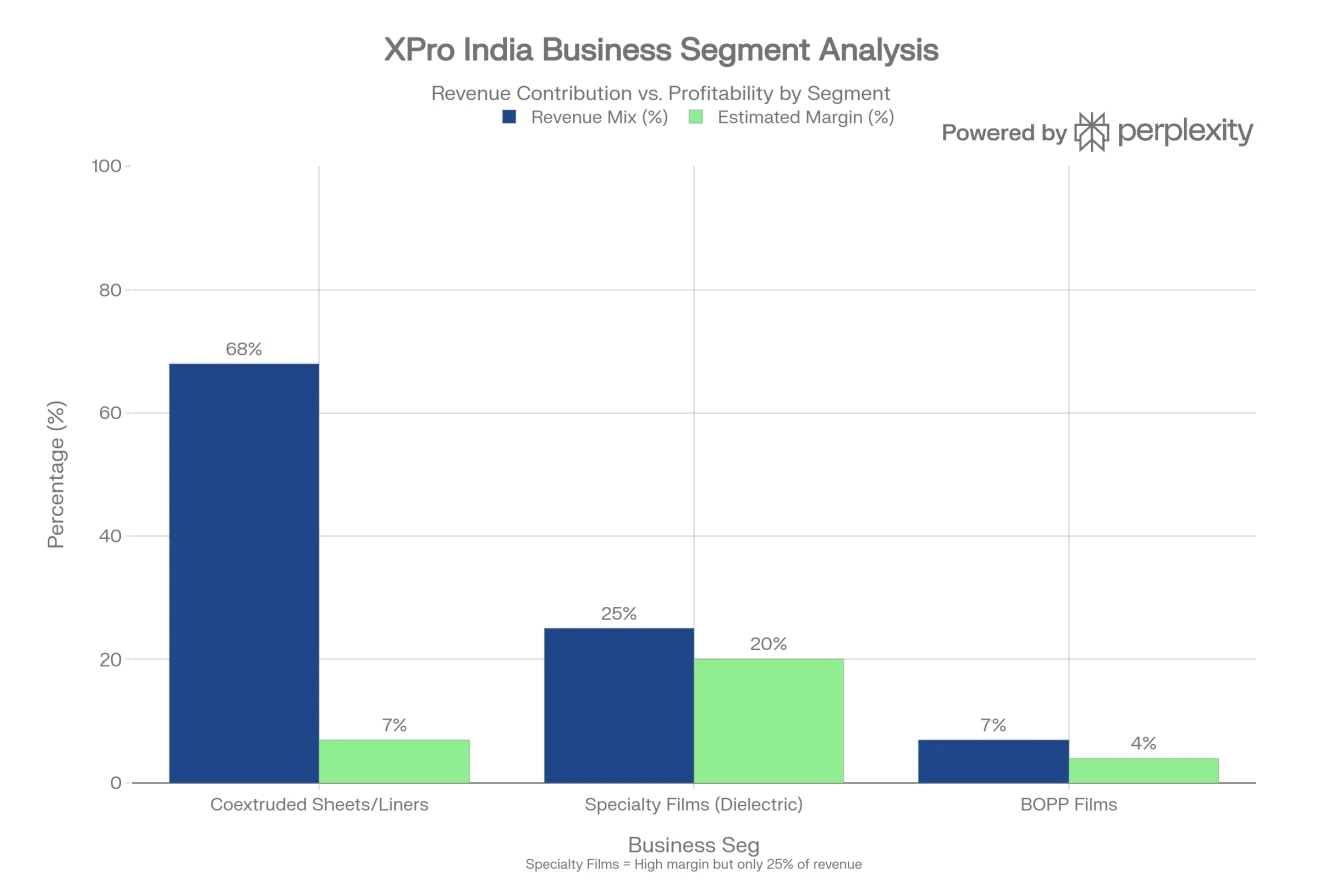
Chart 2: Business Segment Analysis
Key Insights:
Margin-Revenue Mismatch:68% of revenue comes from low-margin coextruded sheets (7% OPM), while high-margin specialty films (20% OPM) contribute only 25%
Strategic Imperative: Company must shift mix to 50%+ specialty films to improve blended margins
Current Trajectory: Barjora expansion targets specialty, but delays push benefit to FY27+
BOPP Films (7% revenue): Likely loss-making or breakeven - candidate for exit/de-emphasis
Chart 3: Valuation vs. Peers Comparison
Key Insights:
Extreme Valuation Disconnect: XPro trades at 166.23x P/E vs. peer median 16x - 11.6x premium with NO justification
Inferior Returns: ROCE of 2.93% vs. peer median 17.5% - XPro is LESS profitable yet MORE expensive
Minimal Shareholder Return: Dividend yield 0.2% vs. peer 1.1%
Verdict: This is textbook valuation bubble driven by retail enthusiasm and illiquidity, not fundamentals
Executive Summary & Investment Recommendation
Company Snapshot
XPro India Limited is a ₹2,472 Cr market cap polymer processing company with 40+ years legacy, operating in three segments: coextruded sheets/refrigerator liners (68% revenue), specialty dielectric/capacitor films (25%), and BOPP packaging films (7%). Part of the prestigious Birla family business group, XPro holds leadership positions in niche segments—30% market share in dielectric films and dominant position in refrigerator liners—but faces intense competition in commodity BOPP from players 10-20x its scale.
Investment Thesis: The Good, The Bad, The Ugly
The Good
Strategic Niche Positioning:30% market share in dielectric films with structural growth drivers (EVs, renewable energy, energy storage)
Financial Stability: Debt-free operations (term debt repaid), 5.05x current ratio, ₹220+ Cr net cash
Birla Family Pedigree: 47-year Chairman Sidharth Birla provides governance credibility
Growth Catalyst: Barjora capacity expansion (delayed to Q4 FY26) will add high-margin dielectric capacity
Operational Improvements: Solar partnership to reduce energy costs; UAE subsidiary for export growth The Bad
Margin Collapse: OPM crashed from 14-15% to 9.6% in FY25 (-470 bps)
Revenue Mix Problem:68% from low-margin (7%) commodity products
Execution Delays: Barjora postponed 6-9 months; history of missing timelines
Cash Generation Weak: OCF fell 70% to ₹13 Cr; negative FCF (-₹100 Cr) in FY25
Scale Disadvantage: 10-20x smaller than peers (Uflex, Polyplex, Jindal Poly)
Forex Mismanagement:₹15+ Cr losses in 9M FY26 on unhedged Euro borrowings
Limited R&D: Under-invested (<1% of sales) vs. peers (2-3%)
The Ugly
EXTREME OVERVALUATION: 166.23x P/E vs. peer median 16x (11.6x premium) with INFERIOR returns (ROCE 2.93% vs. peer 17.5%)
Illiquidity Risk: Daily volumes ₹0.8-2.6 Cr; 82% held by promoter+retail (sticky); institutional ownership minimal (FII 14.6%, MF 0.8%)
Fair Value Disconnect: Blended fair value ₹250-350 vs. current ₹1,053 = 292-321%
overvaluation.
Reverse DCF Impossibility: Current price implies 20-25% revenue CAGR + 18-20% EBITDA margins + 2.5x ROCE improvement - <20% probability of achievement
Valuation Correction Risk: Any negative news (earnings miss, further delays, macro weakness) could trigger 40-60% correction with no institutional buying support
Financial Scorecard
Metric
Score
Assessment
Revenue Growth
5/10
15% in FY25 but 3Y CAGR -5%; below industry
Profitability
3/10
Margins collapsed; ROE 6.6%, ROCE 7.9% (below capital cost)
Financial Health
6/10
Strong balance sheet but negative FCF, weak OCF
Competitive Position
4/10
Leader in niches (25% revenue) but weak in 75% of business
Management Quality
6/10
Credible but execution gaps; poor forex hedging
Valuation
1/10
Severely overvalued - 3-4x fair value
Liquidity
2/10
Major concern - exit difficulty in selloff
Growth Potential
6/10
EV/energy storage tailwinds positive but execution risk high
Overall Score
4.1/10
BELOW AVERAGE - AVOID
Investment Recommendation: SELL / AVOID
Rating: (2/5 Stars) - Fundamentally Average Business at Bubble Valuation Target Price:₹268 (blended fair value) - 75% downside risk from ₹1,053
Recommendation by Investor Profile:
Investor Type
Action
Rationale
Current
SELL 70-100%
Book profits while liquidity exists; downside risk 65-75%
Book profits while liquidity exists; downside risk 65-75%
Holders
immediately
Potential Buyers
AVOID at current price
Wait for correction to ₹250-350 before considering
Value Investors
Watchlist
Add at ₹200-300; attractive only at 50-70% discount
Growth Investors
AVOID
Better opportunities in large-cap specialty chemicals with proven execution
Day Traders
High Risk
Extreme volatility (₹850-₹1,378 52-week range) but illiquid
Scenario 1: Large Position (>5% portfolio) - URGENT EXIT
Action: Sell 70-100% immediately, stagger over 5-10 trading days to minimize price impact
Reasoning: Illiquidity + valuation bubble = catastrophic loss potential; protect capital
Accept: May have to sell 5-10% below market due to thin volumes
Stop-Loss:₹950 (already breached) → If stock falls to ₹900, exit remaining at ANY price
Scenario 2: Small Position (<2% portfolio) - PARTIAL EXIT
Action: Sell 50-70% now; hold 30-50% as "lottery ticket" for Barjora success
Reasoning: Limit downside while retaining upside optionality if execution improves
Sell Trigger: Q4 FY26 results (May 2026) - if Barjora not commissioned OR margins don't recover to 11%+, exit remaining
Scenario 3: Trapped Below ₹800 - WAIT FOR BOUNCE
Action: If your buy price was ₹700-800, wait for dead-cat bounce to ₹950-₹1,000, then exit
Reasoning: Already 25-30% underwater; salvage losses on technical bounce
Never: Don't average down - business fundamentals don't justify catching the falling knife
What Would Change Our View (Buy Triggers)
XPro could become a BUY if the following occur:
Price-Based Triggers:
Stock corrects to ₹250-350 (fair value range)
Stock corrects to ₹200 or below (deep value zone - Strong Buy)
Fundamental Triggers:
Barjora commissioned successfully with 80%+ utilization achieved within 6 months (Q4 FY26 -Q1 FY27)
Operating margins recover to 13-14% sustained for 2 consecutive quarters
Major OEM contract win for EV capacitor films (Tata Motors, Mahindra, BYD, MG Motor) worth ₹50+ Cr annually
Specialty films contribution increases to 40%+ of revenue mix (from current 25%)
UAE subsidiary generates ₹50+ Cr exports by FY27 (proving international competitiveness)
ROCE improves to 12-15% (above cost of capital)
Strategic acquisition of complementary specialty films player for scale
Institutional participation increases: FII+DII+MF holdings rise to 30%+ (indicating professional validation) Until then: XPro remains a SELL/AVOID - Don't confuse a good business (narrow moat in niche segment) with a good investment (requires reasonable valuation).
Alternative Investment Ideas (Better Risk-Reward)
If interested in India packaging/specialty films theme, consider:
Company
Market Cap (₹
P/E
ROCE
Why Better than XPro
Cr)
Polyplex
2,786
2,786
38x
7.2%
Global polyester films leader; similar valuation but 2.5x scale
The consolidated results include UAE losses of ~₹12.6 Cr in 9M FY26, which depresses group earnings by 30-35%. This is a transitional overhang, not a structural problem. If/when UAE achieves profitability, consolidated results could improve materially. HOWEVER, this potential upside does NOT justify 166x PE. At best, UAE success brings consolidated earnings to ₹35-40 Cr (FY28E), warranting only 15-20x PE (₹250-320 fair value). Stock is pricing in a perfect execution scenario with <25% probability given:
Barjora already delayed 6-9 months
UAE has zero revenue after 6 months of operations
No management guidance on UAE breakeven timeline Bottom Line: UAE is a legitimate catalyst to MONITOR but should be viewed as a free option that reduces downside risk, rather than a reason to buy at inflated prices.
Bottom Line for Oorjita Subscribers:
"XPro India is a decent company at an indecent valuation. The dielectric films business is genuinely interesting—30% market share in a segment with EV/renewable energy tailwinds. But paying 166.23x earnings for 7.9% ROCE in a commoditized industry is financial suicide. This is a classic retail bubble where hope (Barjora expansion, EV theme) has disconnected from reality (collapsing margins, execution delays, cash burn). At ₹1,053, XPro prices in perfection that history suggests is unlikely. Wait for the 60-75% correction that math demands, or move on to better opportunities. Your capital deserves a margin of safety, not a margin call."
XPro India: A Niche… | Oorjita Anveshan · 11 Feb 2026