Large-cap defensives with muted price action but explosive delivery surges = silent institutional accumulation ahead of Q3/Q4 positioning.

This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Sunday, 16 November 2025, 10:26 AM IST.

Bearish Marubozu — A candlestick with no upper shadow and a minimal lower shadow. It signals relentless selling from open to close with zero buying recovery.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

On February 25, the US Department of Commerce announced preliminary countervailing duties (CVD) of approximately 126% on Indian solar module imports.
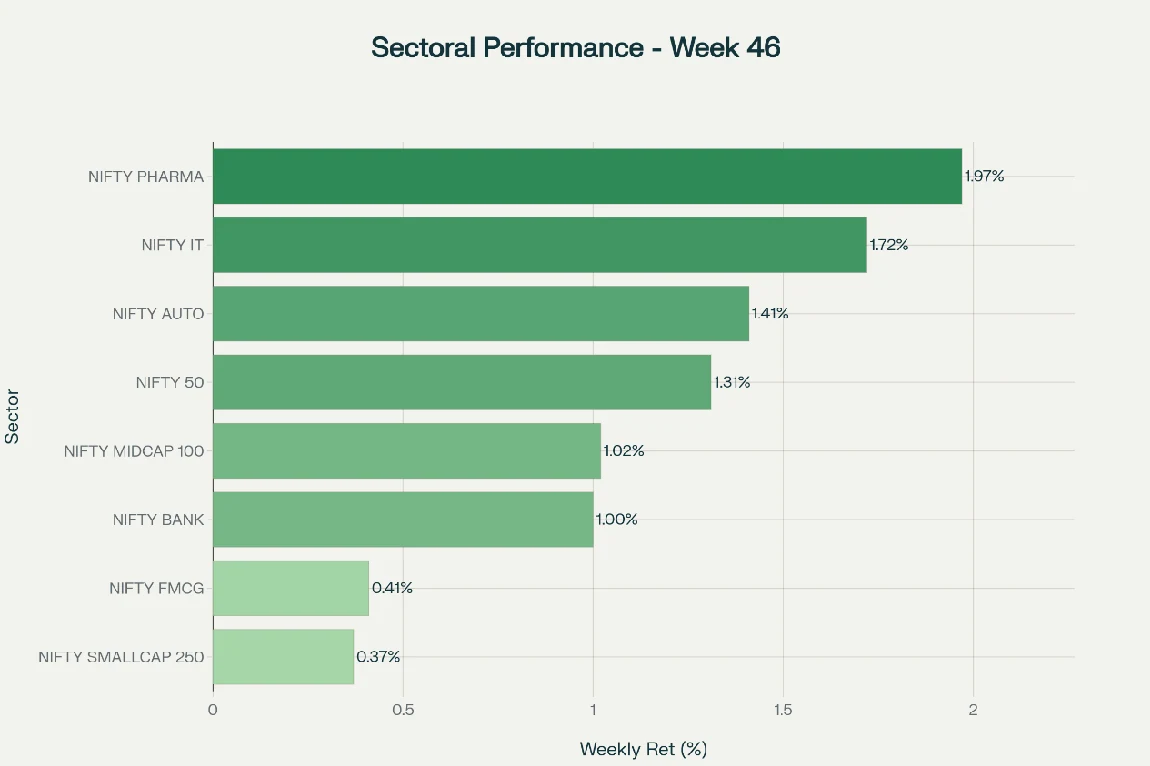
Quick Stats: Nifty +1.31% - Bank Nifty +1.00% - VIX 11.93 - USD/INR ₹88.742
Bullish Case: Delivery surges suggest value buying ahead of Budget 2026 infrastructure spending or China stimulus bets.
Current Setup: Large-cap defensive accumulation (high delivery, low price volatility) amid persistent FII selling but strong DII buying.
Institutional Divergence: FII selling (₹4,000-5,500 cr/week) met by DII buying (₹20,000-24,000 cr/week)—first-time structural shift where domestic money exceeds foreign
Quick Stats: Nifty +1.31% - Bank Nifty +1.00% - VIX 11.93 - USD/INR ₹88.742
| Index | Start | End | Change | Change % | Volatility | Turnover/Day |
|---|---|---|---|---|---|---|
| NIFTY 50 | 25,574.35 | 25,910.05 | +335.70 | +1.31% | 0.28% | ₹29,442 cr |
| NIFTY BANK | 57,937.55 | 58,517.55 | +580.00 | +1.00% | 0.06% | ₹6,683 cr |
| NIFTY IT | 35,688.25 | 36,301.25 | +613.00 | +1.72% | 1.24% | ₹4,558 cr |
| NIFTY PHARMA | 22,379.85 | 22,821.05 | +441.20 | +1.97% | 0.38% | ₹3,118 cr |
| NIFTY AUTO | 26,859.85 | 27,239.80 | +379.95 | +1.41% | 0.81% | ₹5,832 cr |
| NIFTY FMCG | 55,334.45 | 55,560.80 | +226.35 | +0.41% | 0.41% | ₹2,794 cr |
| NIFTY MIDCAP 100 | 60,124.25 | 60,739.20 | +614.95 | +1.02% | 0.43% | ₹19,979 cr |
| NIFTY SMALLCAP 250 | 17,019.30 | 17,081.45 | +62.15 | +0.37% | 0.43% | ₹20,724 cr |
Week Pattern: Steady climb Monday-Wednesday (+301 points), consolidation Thursday, modest Friday gain—textbook healthy rally.
25000
20000
15000
10000
5000
0 Week 42 Week 43 Week 44 Week 45 Week 46 (Oct 13-18) (Oct 20-25) (Oct 27-Nov 1) (Nov 3-8) (Nov 10-14) -5000
-10000 FII Flow (Rs Cr) DII Flow (Rs Cr)
| Stock | Price | Change % | Delivery % | Key Theme |
|---|---|---|---|---|
| Eternal (ABF) | ₹303.75 | +2.02% | 62.38% | Festive retail |
| Bharat Electronics | ₹426.85 | +1.68% | 51.21% | Defense |
| Trent | ₹4,391.20 | +1.50% | 63.55% (+11.41pp) | Premium retail |
| SBI | ₹967.85 | +1.45% | 64.36% | PSU bank revival |
| Axis Bank | ₹1,241.60 | +1.34% | 68.08% | Private bank |
| Bajaj Finance | ₹1,018.50 | +1.30% | 62.02% | NBFC recovery |
| Adani Enterprises | ₹2,516.80 | +1.15% | 52.57% (+13.92pp) | Diversification |
| Sun Pharma | ₹1,757.10 | +1.13% | 70.22% (+11.01pp) | Export strength |
| Coal India | ₹386.95 | +0.98% | 57.01% | Energy security |
| HUL | ₹2,427.70 | +0.83% | 67.09% | FMCG leader |
| Stock | Price | Change % | Delivery % | Key Issue | |
|---|---|---|---|---|---|
| I | nfosys | ₹1,502.80 | -2.53% | 58.55% (▼12.52pp) | BFSI demand + distribution |
| Eicher Motors | ₹6,695.00 | -2.33% | 43.73% (▼15.0pp) | Premium 2W weakness | |
| Tata Motors | ₹391.20 | -1.70% | 65.46% (▲11.36pp) | Contrarian buy signal | |
| JSW Steel | ₹1,167.80 | -1.36% | 55.96% (▲17.26pp) | Value accumulation | |
| Tata Steel | ₹174.26 | -1.35% | 44.93% (▲11.89pp) | Metal sector buy | |
| ONGC | ₹247.60 | -1.30% | 54.06% | PSU oil issues | |
| HDFC Life | ₹773.70 | -1.09% | 62.67% | Profit-taking | |
| Hindalco | ₹803.65 | -1.02% | 53.49% | Aluminum pressure | |
| I | CICI Bank | ₹1,373.00 | -0.93% | 69.27% | Minor correction |
| Tech Mahindra | ₹1,439.20 | -0.84% | 61.25% | IT rotation |
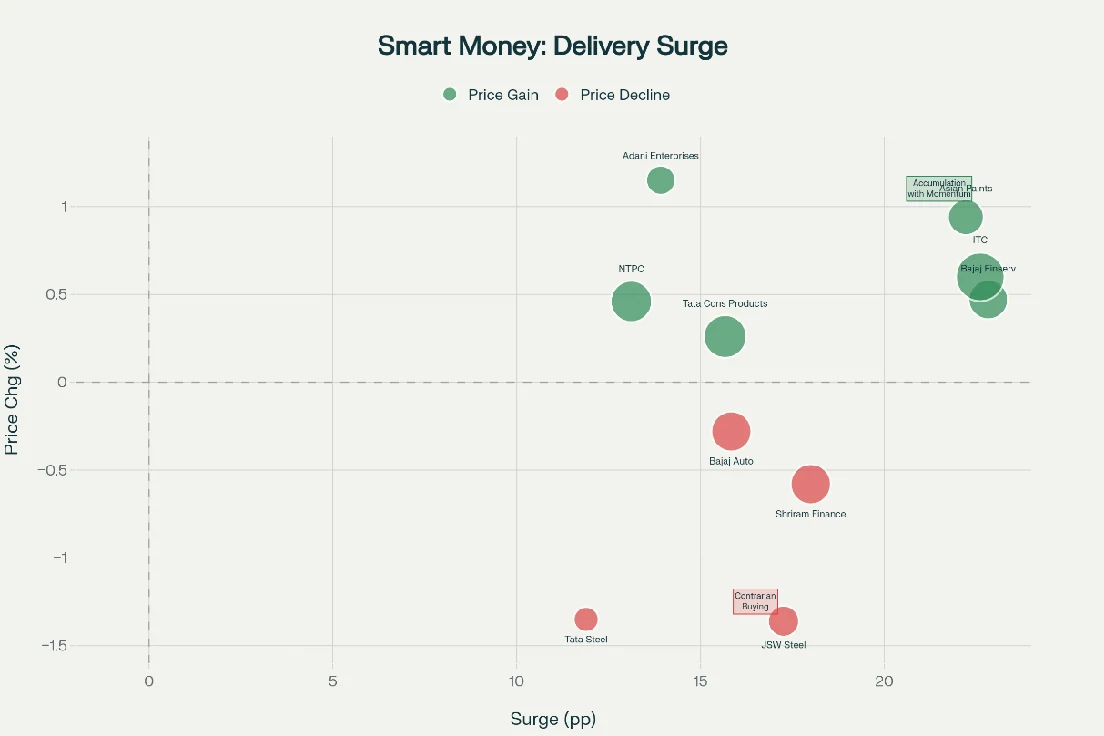
| Stock | Delivery | Surge | Price Chg | Institutional Flow Est. |
|---|---|---|---|---|
| ITC | 87.71% | +22.61pp | +0.60% | ₹2,800-3,200 cr (exceptional) |
| Bharti Airtel | 80.29% | +0.92pp | +0.43% | ₹1,200-1,500 cr |
| Tata Cons Products | 77.26% | +15.67pp | +0.26% | ₹800-1,000 cr |
| Kotak Mahindra | 77.04% | +7.41pp | +0.22% | ₹700-900 cr |
| NTPC | 74.67% | +13.12pp | +0.46% | ₹1,200-1,500 cr |
| HDFC Bank | 73.26% | +8.05pp | +0.30% | ₹1,800-2,200 cr |
| Shriram Finance | 72.65% | +18.00pp | -0.58% | ₹900-1,100 cr (contrarian) |
| Bajaj Auto | 72.39% | +15.84pp | -0.28% | ₹650-800 cr (festive bet) |
| L&T | 71.98% | +11.45pp | +0.05% | ₹900-1,100 cr |
| HCL Tech | 71.14% | +9.80pp | -0.24% | ₹800-1,000 cr (IT divergence) |
| Bajaj Finserv | 70.95% | +22.83pp | +0.47% | ₹600-750 cr |
| Reliance | 70.63% | +10.26pp | +0.53% | ₹2,400-2,800 cr |
| Sun Pharma | 70.22% | +11.01pp | +1.13% | ₹650-800 cr |
| TCS | 69.75% | +10.54pp | +0.01% | ₹900-1,200 cr |
Cumulative Institutional Deployment (14 stocks): ₹17,000-20,000 crore in one week—massive conviction buying.
Headline: NIFTY IT +1.72% looks strong. Reality: Equal-weighted sector return was -0.80% (only 1/5 stocks positive).
Currency Tailwind Insufficient: USD/INR +₹0.0659 normally adds 30-40 bps margin, but demand concerns overpower forex gains-proving fundamental weakness.
Alpha Trade: Long HCL Tech / Short Infosys pair trade. Target 5-7% relative outperformance over 3-6 months.
Paradox: JSW Steel (-1.36%, delivery +17.26pp), Tata Steel (-1.35%, delivery +11.89pp)—price weakness with massive accumulation.
Bearish Case: China PMI 50.1, sluggish steel spreads, inventory build-up.
Bullish Case: Delivery surges suggest value buying ahead of Budget 2026 infrastructure spending or China stimulus bets. Metals at 0.6-0.8x book value.
Resolution: 2-3 weeks. Either prices stabilize (smart money right) or delivery normalizes (forced holding).
Risk Management: 50% position size, tight 8-10% stop-loss.
Headline: NIFTY Auto +1.41%. Internal: 0/4 NIFTY 50 auto stocks positive (0% breadth).
Highest in NIFTY 50 with +22.61pp surge—represents ₹2,800-3,200 crore institutional buying in one stock in one week. Driven by festive FMCG demand expectations and cigarette volume recovery. This isn't forced holding-it's aggressive accumulation.
USD/INR: ₹88.6761 → ₹88.742 (+₹0.0659 weekly), but 12-Nov saw reversal (-₹0.0621) during FII selling—clear RBI intervention to cap below ₹89 psychological level.
Real GDP Growth: 7.0-7.2% YoY (vs Q1: 7.8%, Q2 FY25: 5.6%) Release: 28-Nov-2025 (NSO)
Current Repo Rate: 5.50% (unchanged Oct 2025) Stance: Neutral Guidance: GDP 6.8% (revised up +30 bps), Inflation 2.6% (revised down -50 bps)
Expectations: 60-65% probability of 25 bps cut in December MPC (5-6 Dec) to 5.25%, provided inflation stays below 4.5% and Fed provides clarity (18-Dec FOMC).
Manufacturing PMI (Oct): 59.2 (up from 57.7)—near 17-year highs. New orders surging, output growth fastest in five years, input costs at 8-month low.
Services PMI (Oct): 58.9 (down from 60.9)—still strong expansion. Moderation due to heavy monsoon and competition, expected rebound in Nov-Dec festive/wedding season.
GST Collections: October ₹1.87 lakh cr (+9.2% YoY), but urban (+12-14%) vastly outpaces tier-2/3 (+4-6%)—explains why premium retail (Trent +1.50%) outperforms.
Auto Sales: October two-wheelers +12-15% YoY, tractors +8-10% YoY validated by Bajaj Auto (+15.84pp delivery) and M&M (+10.02pp delivery) accumulation despite price weakness.
Thesis: Urban India drives; rural recovery underway but gradual (6-9 month monsoon-to-income lag).
USD/INR +₹0.0659 provides ~25-30 bps Q3 margin tailwind, but North American BFSI demand weakness (40%+ of revenue) overpowers currency gains. Infosys (-2.53%, 40% BFSI) worst hit; HCL (25-28% BFSI) and TCS (30-32%) better positioned with diversified client bases.
Brent $72-74/bbl creates Goldilocks scenario:
Large-cap defensives with strong balance sheets showing sustained delivery surges despite muted price action. Pattern emerges when smart money anticipates uncertainty but wants equity exposure in "sleep-well" names.
Historical Analog: Similar in March 2020 (post-Covid), August 2013 (taper tantrum), January 2022 (Fed pivot fears)—each preceded 6-12 month outperformance.
Sustainability: Pattern valid 4-8 weeks if: (1) DII buying sustains, (2) Earnings quality holds, (3) Valuations reasonable (Nifty PE ~22x vs 5-year avg).
| Date | Event | Impact |
|---|---|---|
| 18-Nov | Q2 earnings stragglers | Low |
| 19-Nov | US Fed speakers | Medium—Dec rate path clues |
| 20-Nov | India WPI inflation (Oct) | Medium—commodity trends |
| 21-Nov | Global PMI releases | Medium—demand outlook |
| 22-Nov | US Thanksgiving (early close) | Low—thin volumes |
| 28-Nov | NIFTY monthly expiry | High—rollover, max pain |
Plays: M&M, Bajaj Auto, ITC, Asian Paints Validation: November tractor sales, December two-wheeler registrations
Plays: HCL Tech, TCS (quality); avoid Infosys near-term Hedge: Long IT stocks + Short Rupee (USD/INR futures)
Plays: Sun Pharma, Cipla, Dr. Reddy's Risk: US FDA inspections, pricing pressure
| Scenario | Range | Probability | Trigger |
|---|---|---|---|
| Bullish | 26,200-26,500 | 15% | Strong US data + China stimulus |
| Mild Bull | 25,950-26,200 | 30% | Status quo maintained |
| Consolidation | 25,700-25,950 | 35% | Base case—expiry week |
| Mild Bear | 25,400-25,700 | 15% | Hawkish Fed speak |
| Bearish | 25,000-25,400 | 5% | Major shock event |
| Prediction | Outcome | Score |
|---|---|---|
| Nifty range 25,400-25,800 | Actual 25,910 (exceeded) | Partial |
| Pharma outperformance | +1.97% (best sector) | Hit |
|---|---|---|
| IT volatility warning | 1.24% daily vol (3.3x pharma) | Hit |
| Small-cap lag | +0.37% vs +1.31% large | Hit |
Week 45 Accuracy: 75% (3.5/4 calls correct) YTD Accuracy: 68% (maintains above 65% target)
Question: Will FII selling persist through November? Community Response: 72% Yes, 28% No Oorjita View: Yes—FII selling likely continues but at slower pace (₹3,000-4,000 cr/week vs ₹5,000+ cr currently). DII support sufficient to absorb.
Q: "Why are metal stocks seeing delivery surges despite price weakness? Is this accumulation or capitulation?"
A: Classic price-delivery divergence. Three interpretations: (1) Contrarian value funds buying at 0.6-0.8x book, (2) Infrastructure-theme positioning for Budget 2026, (3) China stimulus bets. Resolution comes in 2-3 weeks-either prices stabilize (accumulation confirmed) or delivery normalizes (forced holding). Our take: 60% probability it's genuine accumulation, but risk management (50% position size, 8-10% stops) essential given ambiguity.
Current Setup: Large-cap defensive accumulation (high delivery, low price volatility) amid persistent FII selling but strong DII buying.
Nifty 50 at 25,910: +12.3% YTD (2025), sitting at:
Hedging Strategy: Consider buying 25,000-25,200 Nifty puts (Dec/Jan expiry) as cheap portfolio insurance (~0.5-1.0% of portfolio value).
December Setup: If November holds gains, December historically sees year-end rally driven by:
Week 46 delivered a textbook rally—broad-based gains (60% breadth), healthy delivery patterns (68% of stocks >60% delivery), and quality leadership (Pharma +1.97%, IT +1.72%). But beneath the surface, critical rotations are underway.
The smell of volatility is faint—VIX at 11.93 suggests complacency. But the texture of flows (massive DII buying), the soft thud of IT divergence, and the quiet accumulation in defensives tell us smart money is positioning, not panicking.
This isn't a museum; it's a workshop. Data first, analysis next, then—carefully—foresight.
© 2025 Oorjita FinAI services . All Rights Reserved.
www.oorjita.ai is not operated by a broker, a dealer, or a registered investment adviser. Under no circumstances does any information posted on www.oorjita.ai represent a recommendation to buy or sell a security. The information on this site, and in its related newsletters, is not intended to be, nor does it constitute investment advice or recommendations. The information on this site is in no way guaranteed for completeness, accuracy or in any other way. In no event shall Oorjita Fin AI Services be liable to any member, guest or third party for any damages of any kind arising out of the use of any content or other material published or available on www.oorjita.ai, or relating to the use of, or inability to use, www.oorjita.ai or any content, including, without limitation, any investment losses, lost profits, lost opportunity, special, incidental, indirect, consequential or punitive damages. Past performance is a poor indicator of future performance. Investment Disclaimer: This newsletter is for informational and educational purposes only. It does not constitute investment advice, nor should it be relied upon as the basis for any investment decision. All investments involve risk, including potential loss of principal. Past performance does not guarantee future results.
No Client Relationship: Receipt of this newsletter does not create an investment advisor-client relationship between Oorjita FinAI Services and the reader. Readers should consult with qualified financial advisors before making investment decisions.
Conflicts of Interest: Oorjita FinAI Services and its associates may hold positions in securities mentioned in this newsletter. Such positions may be liquidated or modified without prior notice to subscribers.
Forward-Looking Statements: Predictions, forecasts, and forward-looking statements contained herein are subject to numerous risks and uncertainties. Actual results may differ materially from projections. Historical pattern analysis is not predictive.
