
India’s Tech Startup Ecosystem: A Reality Check
Nasdaq closed at a record high; Broadcom led gains as traders priced Fed cuts this month. Stoxx 600 green; Nikkei firm this morning
Nasdaq closed at a record high; Broadcom led gains as traders priced Fed cuts this month. Stoxx 600 green; Nikkei firm this morning

Key watch factors: Apple's iPhone 17 event today, Fed rate cut expectations building momentum, and China's inflation data Wednesday.
Sector sentiment: Mixed with rotation from traditional tech to AI infrastructure plays.
Sectoral ripple effects: Logistics and home services platforms gaining pre-IPO investor attention, validating asset-light business models.
Morgan Stanley calls 'rolling recession' end: Chief strategist Mike Wilson argues 3-year disguised downturn transitioning to recovery phase, supporting early-cycle bull market thesis.
Good morning, investors! Indian markets closed marginally higher yesterday with Sensex gaining 76 points to 80,787 and Nifty adding 32 points to 24,773. The overnight action shows GIFT Nifty futures at 24,960, indicating a flat-to-positive start.
Overnight: Nasdaq closed at a record high; Broadcom led gains as traders priced Fed cuts this month. Stoxx 600 green; Nikkei firm this morning
Safe-havens/energy: Gold printed new records near $3,640–3,650/oz; Brent steadied around the mid-$60s
Metals sentiment brightened after Morgan Stanley’s steel upgrade basket (JSW/Tata Steel/SAIL); auto names watch for GST-led price roll-downs later this month.
Cognition AI raises $400M at $10.2B valuation – The autonomous coding agent "Devin" secured massive funding led by Founders Fund, highlighting investor confidence in AI coding solutions despite broader market cooldown.
Apple's "Awe Dropping" event today – iPhone 17 series launch expected with ultra-thin iPhone 17 Air (5.5mm thickness) potentially replacing the Plus model. Pro models may get redesigned camera bumps and upgraded cameras.
IFA Berlin 2025 highlights – AI-powered smart glasses and next-gen wearables dominating the consumer tech landscape, signaling accelerated adoption of ambient computing.
Sector sentiment: Mixed with rotation from traditional tech to AI infrastructure plays. Actionable trigger: Apple event at 10:30 PM IST could impact global tech sentiment and supplier stocks.
Porter nears $110M pre-IPO round – India's logistics unicorn targeting one of 2025's biggest venture deals ahead of 12-15 month IPO timeline. Total round could reach $300-310M with significant secondary sales.
Urban Company's ₹1,900 crore IPO opens tomorrow – Home services marketplace priced at ₹98-103 per share, comprising ₹472 crore fresh issue and ₹1,428 crore OFS.
Dev Accelerator IPO this week – IT services company opens September 10-12 at ₹56-61 price band, targeting ₹143 crore fundraise.
Sectoral ripple effects: Logistics and home services platforms gaining pre-IPO investor attention, validating asset-light business models.
B2B e-commerce firm Jumbotail has raised $120 million in a funding round led by SC Ventures, the investment arm of Standard Chartered. The company announced it will use the funds to build AI-native solutions. This funding round coincides with Jumbotail's acquisition of Solv India, a B2B financial services platform, which has been approved by the Competition Commission of India (CCI). This consolidation is expected to create significant ripple effects in the B2B marketplace and food and grocery sectors by creating a more integrated platform for small retailer.
Auto pack leads – Tata Motors, M&M, Hyundai Motor India announcing price cuts post-GST reforms. Watch levels: Tata Motors above ₹720 for momentum continuation.
Metals (OW) — MS upgrades + stronger domestic demand narrative; watch JSW Steel (levels: ₹1,080/1,130) and Tata Steel (₹195/200) into follow-through.
Banking mixed – Bank Nifty at 54,115 showing consolidation. HDFC Bank, ICICI Bank range-bound ahead of policy announcements.
Pharma regulatory updates – Zydus Lifesciences cleared USFDA inspection with 4 observations, Aurobindo Pharma received 8 procedural observations.
Corporate: Infosys board buyback discussion on Sep 11; track IT flows vs USD strength.
ConocoPhillips layoffs signal energy sector discipline – Up to 25% staff cuts highlight capital allocation pressures as oil prices moderate.
Morgan Stanley calls 'rolling recession' end – Chief strategist Mike Wilson argues 3-year disguised downturn transitioning to recovery phase, supporting early-cycle bull market thesis.
European bond yields surge – UK 30-year yields hit 5.72% (highest since 1998), reflecting fiscal deficit concerns across developed markets.
A rare "Blood Moon" total lunar eclipse was visible across India on September 7-8, coinciding with the sacred Pitru Paksha period. Numerologists and astro-finance analysts note its convergence with today's 9-9-9 date, which is linked to Mars. This combination is believed to represent a "cosmic completion code," potentially signaling the end of old market cycles and the beginning of new wealth patterns, albeit with heightened volatility.
For a moment, India was hailed as the next great frontier for tech startups. However, the tide has turned. The struggles of marquee names like Byju's (valuation down over 90%) and Paytm (stock collapsed ~80% post-IPO) highlight a deeper malaise. These two firms alone have shed a combined value of over $45 billion from their peaks.
This downturn has triggered a venture capital retreat, with funding for the next generation of founders drying up. While more than three dozen tech startups with a combined valuation of $100 billion are still projected to go public by 2027, the path to a successful IPO is now fraught with greater scrutiny.
"Central to our view is the notion that the economy has been much weaker for many companies and consumers over the past 3 years than what the headline economic statistics suggest. We're entering an early cycle environment."
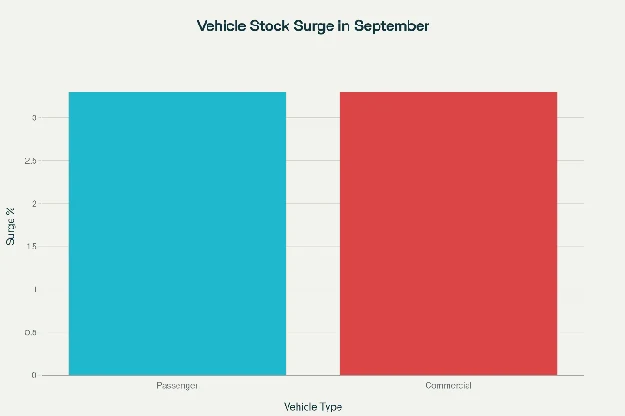
Nifty Auto Index Performance – 3.3% surge led by GST reform beneficiaries, marking strongest single-day gain in September with broad-based participation across passenger and commercial vehicle segments.
This newsletter is for informational purposes only and does not constitute investment advice. All data has been validated through multiple reliable sources. Past performance does not guarantee future results. Please consult with a qualified financial advisor before making investment decisions. Oorjita FinAI Services is not responsible for any financial losses incurred based on this information.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Tuesday, 9 September 2025, 8:43 AM IST.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.

Institutional flows showed a divergence, with Foreign Institutional Investors (FII) registering net outflows of ₹972.13 crore (provisional), while Domestic Institutional Investors (DII) pumped in ₹1,666.98 crore (provisional), resulting in a net combined inflow of ₹694.85 crore.