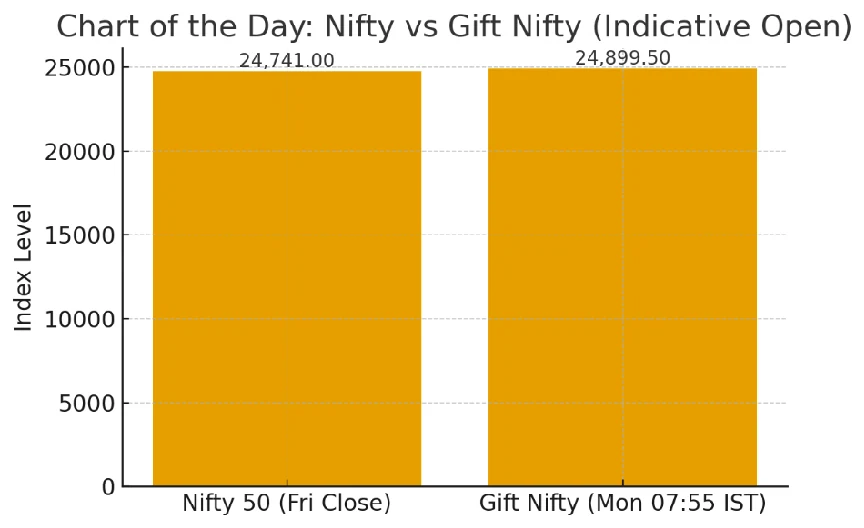
Markets enter Monday with cautious optimism after Friday's mixed close. GIFT Nifty's +86 point gap-up suggests positive opening, driven by Japan's stronger-than-expected Q2 GDP
MK
Dr. Murali Kalyanaraman
Global CFO · 30+ years in corporate finance · Chartered Accountant (ICAI) · 5 min read
(0.5% vs 0.3% flash estimate) and fifth consecutive quarter of expansion.
Key Watch Factors:
Auto sector momentum continuing from Friday's 2.8% surge on strong sales data.
IT sector pressure persists with heavyweight stocks facing headwinds.
Global inflation concerns amid mixed Fed signals and tariff uncertainties
Tech Pulse
Indian Tech Highlights:
Apple India Records $9B Revenue: Cupertino sees record sales as iPhone 17 launch nears, highlighting India's growing premium market appetite.
IT Services Evolution: Indian tech firms shifting from traditional RFP-led sales to proactive pitches now driving 33% of renewals, adapting to AI-led transformation.
PhysicsWallah IPO Update: EdTech unicorn files updated DRHP for ₹3,820 crore public offering, with founders paring stake.
Global Tech Developments:
Tesla's $1 Trillion Musk Package: Board proposes unprecedented compensation plan tied to AI/robotics transformation targets.
Google Hit with $3.45B EU Fine: Antitrust penalty for adtech practices could escalate US-EU trade tensions.
TikTok Europe Milestone: Platform crosses 200M monthly users (1 in 3 Europeans), showcasing rapid continental penetration.
OpenAI weighs making its own AI chips and diversifying suppliers — a medium-term tailwind for data-center capex & semi supply chains (cooling, power, memory). Trigger: watch any 2026 silicon roadmap reveal Sector Trigger: Watch for Apple September 9 'Awe Dropping' event impact on Indian smartphone ecosystem and supply chain stocks.
Funding Radar
Mega Deals Validated:
CityMall:$47M Series D (Accel-led) - Meesho competitor in social commerce.
Seekho:$28M for short video platform expansion.
FirstClub:$23M Series A in quick commerce space.
Blue Tokai Coffee:$25M growth funding.
Colive:$20M for co-living expansion. Sectoral Ripple: E-commerce dominance with 8 startups raising $78.8M, signaling festive season preparation and quick commerce consolidation.
Market Movers & Watchlist
Friday's Standouts (Validated NSE Data):
Auto Gainers: M&M (+2.34%), Eicher Motors (+2.41%), Maruti (+1.64%)
IT Laggards: Tech Mahindra (-1.49%), TCS (-1.54%), HCL Tech (-1.61%)
Banking Mixed: Canara Bank (+0.99%), ICICI Bank (-0.19%), HDFC Bank (+0.22%)
Nepal Social Media Ban: Instagram, X, YouTube blocked - potential template for regional regulatory shifts.
Xiaomi India Strategy: COO reveals expansion beyond smartphones into ecosystem play.
ASML-Mistral AI Deal: €1.3B investment makes chipmaker largest shareholder in French AI startup, boosting European tech independence.
In a significant cybersecurity event, Cloudflare successfully thwarted a record-breaking 11.5 Tbps Distributed Denial of Service (DDoS) attack, the largest ever recorded. This highlights the increasing scale of cyber threats and the critical importance of robust defense mechanisms for internet infrastructure
Deep Dive – India's Startup Funding Renaissance
September Surge Analysis: The 90% week-over-week funding jump to $186.1M signals pre-festive
season capital deployment and venture confidence recovery.
Key Insights:
E-commerce Dominance:40% of total funding ($78.8M across 8 startups) reflects quick
commerce war intensification
Growth vs Early Stage:$285M in growth deals vs $63M early-stage indicates maturity preference
Sector Rotation: From fintech to commerce, logistics, and consumer tech
Investor Takeaway: Accel, Elevation Capital most active with portfolio companies showing strong execution in competitive segments.
Deep Dive — Rupee at record lows: who benefits, who hurts?
State of play: The rupee printed fresh lows last week (intraday ~88.36; ref rate ~88.3242). Drivers: tariff uncertainty, FPI equity outflows, and broad USD strength.
Near-term dynamics: With forex markets shut today (holiday), any catch-up move shifts to Tuesday; equities trade normally but settlement lags may dampen risk appetite intraday.
Sector lens (next 1–3 months):
Positive bias: IT services, specialty chem exporters, pharma with USD billing → translation gains.
Monitor/hedge: OMCs, airlines, paint & consumer staples (import content) — vulnerable if Brent (~$65–66) rebounds while INR stays weak.
Investor takeaway: Prefer export-heavy cash-rich leaders with pricing power; for importers, look for explicit hedging disclosures and pass-through mechanisms during Q2 calls.
What to Watch Today
Macro Calendar:
No major economic data releases scheduled
Corporate earnings watch for Q1 FY26 laggards
Global cues from European opening and US futures
Regulatory Focus:
GST Council follow-up on potential rate rationalization
RBI policy stance signals ahead of October review
Quote of the Day
"Market sentiment remains cautiously optimistic; however, persistent volatility and mixed global cues continue to weigh on investor confidence." — Amruta Shinde, Technical & Derivative Analyst, Choice Broking (September 4, 2025)[19]
Chart of the Day
GIFT Nifty Pre-Market Momentum: +86.5 points surge to 24,912 indicates strong opening bias, with key resistance at 24,980 (50-DMA confluence).
Disclosures and notes
Compliance & Disclaimer
This newsletter is for informational purposes only and should not be considered as investment advice. All data has been validated through multiple sources as per our verification protocol. Market investments are subject to risks, and past performance does not guarantee future results. Readers are advised to consult qualified financial advisors before making investment decisions.
Oorjita FinAI Services | Delivering Validated Market Intelligence Since 2025
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 8 September 2025, 8:33 AM IST.