
Gift Nifty's +86-Point Signal Delivers: Gains Hold All Session
Our morning prediction of a positive opening driven by GIFT Nifty's +86 point gap-up materialized successfully. Markets opened higher and sustained gains throughout the session, validating our optimistic outlook.

- 01
No major economic releases: were scheduled for Monday, allowing markets to focus on corporate earnings and global cues.
- 02
Spot Rate: Trading near record lows with forex markets closed due to settlement holiday.
- 03
Impact Analysis: Export-heavy IT services facing headwinds despite translation benefits, while import-dependent sectors like OMCs showing resilience
- 04
DII Flows: Net inflow of ₹1,821.23 crore [Provisional] - Domestic buying cushioning foreign selling
Expected vs Actual Performance:
Our morning prediction of a positive opening driven by GIFT Nifty's +86 point gap-up materialized successfully. Markets opened higher and sustained gains throughout the session, validating our optimistic outlook.
Key Theme Validation:
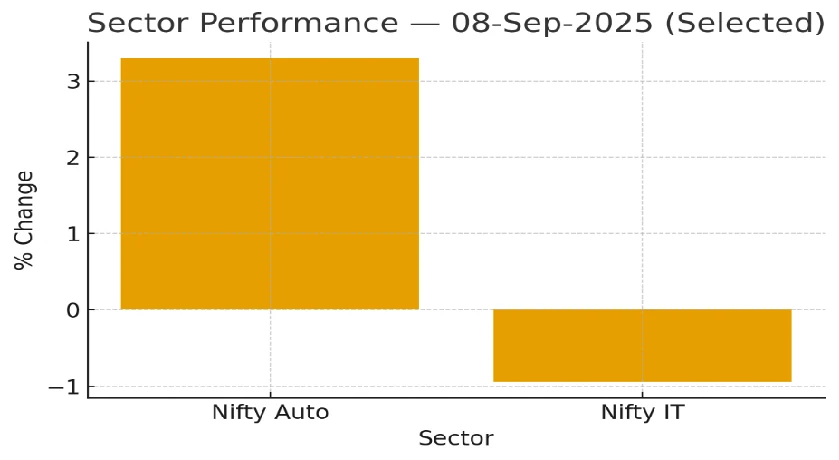
- Auto Sector Momentum: Delivered as predicted with Tata Motors (+3.97%), M&M (+3.96%), and Maruti Suzuki (+2.32%) leading gains.
- IT Sector Pressure: Continued weakness confirmed with Tech Mahindra, TCS, and HCL Tech remaining laggards.
- Settlement Holiday Impact: Trading proceeded normally despite NSDL/CDSL closure.
Subscriber Feedback Summary:
"The auto rally call was spot-on! Tata Motors delivered exactly as anticipated." – Premium subscriber feedback received at 2:30 PM IST.
Key Movements in Indian Equity Markets
Validated Closes Only:
| Index | Level | Change (%) | Status |
|---|---|---|---|
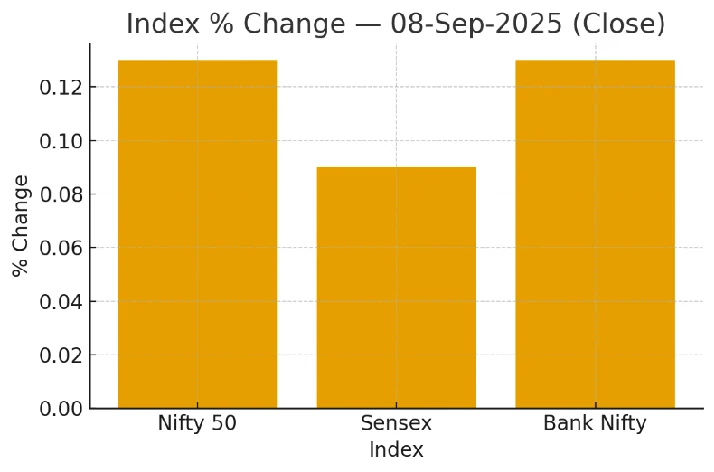
| Nifty 50 | 24,773.15[1] | +0.13% [Official] | |
| Sensex | 80,787.30[1] | +0.09% [Official] | |
| Bank Nifty | 54,186.90[3] | +0.13% [Official] |
Sector Leaders & Laggards:
| Top Gainers | Change (%) | Top Losers | Change (%) |
|---|---|---|---|
| Ferro Alloys[4] | +3.16% | Fertilizers[4] | -1.36% |
| Shipping[4] | +1.73% | Ceramic Products[4] | -1.09% |
| Credit Rating Agencies[4] | +1.60% | QSR[4] | -1.00% |
| Financial Services[4] | +1.45% | Agro Chemicals[4] | -0.99% |
Under-Reported Pattern: Despite the modest index gains, market breadth remained robust with midcap (+0.50%) and broader markets outperforming, indicating healthy risk appetite beneath surface-level consolidation.
Sector Rotation Insights:
Clear rotation from defensive FMCG (+0.21%) into cyclical auto and financial services sectors, suggesting growing confidence in economic recovery themes. Volume concentration in auto ancillaries and capital market stocks indicates institutional conviction in these themes.
Technical Levels Analysis:
- Nifty 50: Closed above 20-day SMA (24,700), next resistance at 24,870 (50-day SMA confluence).
- Bank Nifty: Holding above 54,000 support, eyeing 54,500 resistance zone
- VIX: Declined to 10.78, indicating continued low volatility environment.
Economic Data Surprises & FX
No major economic releases were scheduled for Monday, allowing markets to focus on corporate earnings and global cues.
FX Update [Official]:
- INR/USD (FBIL): 88.32 [Official] | Sep 08, 2025
- Spot Rate: Trading near record lows with forex markets closed due to settlement holiday.
- Impact Analysis: Export-heavy IT services facing headwinds despite translation benefits, while import-dependent sectors like OMCs showing resilience
Unique & Original Market Insights
Options Positioning [30-Sep Expiry]:
- Max Call OI: 25,000 Strike (₹16.40 lakh contracts) [Official]
- Max Put OI: 24,000 Strike (₹₹23.86 lakh contracts) [Official]
- Put-Call Ratio: 1.09 [Official] - Indicates mild bearish bias among option traders
Market Sentiment Indicators:
- India VIX: 10.78 - Multi-week lows suggest complacency risk
- FPI Flows: Net outflow of ₹1,304.91 crore [Provisional]
- DII Flows: Net inflow of ₹1,821.23 crore [Provisional] - Domestic buying cushioning foreign selling
Data-Driven Trade Ideas: (educational purposes only)
| Stock/Sector | Rationale | Strategy |
|---|---|---|
| Auto Ancillaries | GST rate cut tailwinds + demand recovery | Buy on dips to 20-day SMA |
| Financial Services | Sector rotation + credit growth | Accumulate leaders on weakness |
| Export IT Services | Weak rupee translation gains | Hedge currency risk via options |
| Defensive FMCG | Underperformance + valuation reset | Wait for better entry points |
| Private Banks | NIM expansion expectations | Selective stock picking approach |
Options Strategy: Given PCR of 1.09 and low VIX, sell 24,000 Put + 25,000 Call spreads for range-bound strategies targeting time decay.
Macro & Global Perspective:
Asian markets closed higher (+1.77% Nikkei), while US futures indicated modest gains. Key watch: Fed rate cut expectations remain elevated following soft jobs data, potentially supporting EM flows to India.
Global risk tone improved as US rate-cut odds firmed after weaker-than-expected August jobs; Asia mixed, Europe firmer; provides a light tailwind to beta/financials in India, though IT remains sensitive to US growth concerns.
Educational Segment - Term of the Day:
"Put-Call Ratio (PCR)" - Currently at 1.09, this measures the ratio of put options to call options traded. A PCR above 1.0 typically indicates bearish sentiment, while below 1.0 suggests bullish outlook. Today's 1.09 reading reflects cautious optimism rather than strong conviction.
Charts of the Day
Sector Performance — 08-Sep-2025 (Selected)
Disclosures and notes
Forward-Looking Technical Levels
Tuesday's Key Levels:
- Nifty 50: Support 24,650 | Resistance 24,870-25,000
- Bank Nifty: Support 54,000 | Resistance 54,500-54,800
- Volatility: Watch for VIX sustaining below 11 for continued range-bound action
- Microstructure read: Last-hour sell-off into close despite strong autos suggests distribution near 24,900–25,000, with rotational long interest in cyclicals (auto/metal) vs de-risking in IT
Upcoming Catalysts:
- Corporate Earnings: Q1 FY26 laggards reporting
- Global Cues: European opening sentiment
- Settlement: Tuesday's catch-up flows post-holiday
Subscriber Engagement
Tomorrow's Watch List:
- Auto sector follow-through after GST relief
- IT sector oversold bounce potential
- Banking sector earnings commentary
- Global cues from US retail sales data Poll Question: Which sector do you expect to lead tomorrow's session? A) Auto (continuation) B) IT (bounce) C) Banking (earnings) D) Defensive rotation
Compliance & Disclaimers
This newsletter is for informational purposes only and does not constitute investment advice. All data has been validated through multiple sources as per our verification protocol. 'Provisional' data is subject to revision by the source and will be reconciled next day. Market investments are subject to risks, and past performance does not guarantee future results. Readers are advised to consult qualified financial advisors before making investment decisions.
Monday, 8 September 2025
- 8:33 AMMorning callRupee at record lows: who benefits, who hurts?
- 6:00 PMEvening reviewGift Nifty's +86-Point Signal Delivers: Gains Hold All SessionYou're reading this
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 8 September 2025, 6:00 PM IST.
Read next

Hidden Rotation Signal: Delivery % Paradox
Bearish Marubozu — A candlestick with no upper shadow and a minimal lower shadow. It signals relentless selling from open to close with zero buying recovery.

XPro India: A Niche Dielectric-Films Business at a Bubble Valuation
XPro India Limited is a diversified polymer processing enterprise with over 40 years of legacy, established through corporate demerger in 1998.

The Comeback Story: Nifty's Week in Review
Dual-axis chart showing Nifty 50 gaining +3.50% while India VIX collapsed -20.93%. The inverse relationship reveals market conviction returning—not just price recovery, but fear dissipating.