After yesterday's broad-based rally, the market faces a critical test at the 26,150-26,200 resistance zone. The Federal Reserve's 25bp rate cut decision overnight and upcoming US tech earnings (Alphabet, Meta, Microsoft) will be key sentiment drivers.

This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Thursday, 30 October 2025, 9:03 AM IST.

Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.
What's Different Today: After yesterday's broad-based rally, the market faces a critical test at the 26,150-26,200 resistance zone.
Key Drivers: Markets traded near all-time highs ahead of Federal Reserve meeting outcome.
Banking Majors (HDFC Bank, ICICI Bank, Axis Bank): Key to Nifty crossing 26,150; monitor for institutional accumulation.
GIFT Nifty Premium: +80-113 points gap-up indication suggests opening momentum (Weight: 15%).
Indian markets are poised for a gap-up opening this Thursday morning, tracking strong overnight global cues and building on yesterday's robust performance. GIFT Nifty futures indicate an opening around 26,134-26,155 levels, suggesting a premium of approximately 80-100 points above Tuesday's close of 26,053.90.
Nifty 50: 26,053.90 | +117.70 points (+0.45%) Sensex: 84,997.13 | +368.97 points (+0.44%) Bank Nifty: 58,384.65 | +170.55 (+0.29%) Nifty Midcap 100: +0.53% | Smallcap 100: +0.44%
Quality of Move: Strong bullish session with broad-based participation. Markets opened firm and maintained gains throughout the day, closing near session highs. The session witnessed healthy institutional buying with above-average volumes indicating conviction in the rally.
Market Breadth: Exceptionally strong at 2,634 advances against 866 declines, delivering an advance/decline ratio of 2.33. This indicates healthy participation across the market spectrum with sectoral rotation favoring cyclicals.
Outperformers: Engineering Services (+7.35%), Diamond/Gems/Jewellery (+2.39%), Cables (+2.05%), Media (+2%), Metal (+1-2%), Oil & Gas (+1-2%), Energy stocks.
Underperformers: Energy (-12.32%), Commercial Services (-11.45%), Retail (-8.20%), Financial Services (-8.01%), Auto sector (-0.69%).
Top Gainers (Nifty 50): Adani Enterprises, Power Grid, NTPC, Adani Ports, JSW Steel. Top Losers: Dr Reddy's Labs, Maruti Suzuki, Eicher Motors, M&M, Coal India.
FII/FPI Net: -₹2,540.16 Crores (NET SELLING - Sharp reversal from previous day)
After the massive ₹10,340 Crores buying spree on October 28, FIIs turned net sellers on October 29 with outflows of ₹2,540 Crores - representing a stunning ₹12,880 Crores swing in sentiment
Level: 11.98 (Oct 29 close) | Previous: 11.95 Intraday Range: 11.22 - 12.10 52-Week Range: 9.39 - 23.18
S&P 500: 6,890.59 | +0.23% (Near record highs) Dow Jones: Closed marginally lower after Fed comments Nasdaq Composite: 23,958.47 | +0.55%
Key Drivers: Markets traded near all-time highs ahead of Federal Reserve meeting outcome. Tech stocks led gains with anticipation building around Magnificent Seven earnings (Alphabet, Meta, Microsoft reporting tonight). Fed Chair Powell's comments signaled "no rush" on rate cuts, causing USD to strengthen.
Nikkei 225: 51,270 | +2.09% (Historic milestone above 50,000) Hang Seng: 26,433.70 | -0.14% Shanghai Composite: 3,995.09 | +0.17% Sentiment: Broadly positive on US-China trade progress
Crude Oil (Brent): $64.22/barrel | -0.27% Impact: Low crude oil prices positive for India's import bill and OMC margins. Current levels below $65/barrel reduce inflationary pressures.
Gold (India): ₹120,672/10gm on Oct 30 | Down from festival peak of ₹131,953
USD/INR: 88.35 (Oct 29 close) Status: Rupee continues to trade under pressure near 88.30 psychological level. Fed's hawkish tone causing dollar strength.
The Nasdaq Composite surged 0.8% to close at fresh highs on October 29, with the S&P 500 briefly crossing 6,900 intraday for the first time. The "Magnificent Seven" tech stocks are driving this rally, with Meta Platforms closing at $751.67 (+0.03%) ahead of its earnings report tonight. Investors are watching whether these giants can justify their elevated valuations through continued AI infrastructure spending and revenue growth. The positive momentum could spill over to Indian IT majors like TCS, Infosys, and Wipro, which have US revenue exposure exceeding 50%.
Indian startups raised $312 million this week, with AI-enabled platforms and SaaS companies attracting significant capital despite a 30% year-over-year decline in Q3 2025 overall funding. Notable deals include AI-powered upskilling platforms and enterprise automation tools, signaling investor confidence in India's position as a global AI talent hub. This trend could benefit listed tech services companies through increased demand for digital transformation services.
India's semiconductor mission continues to attract global attention, with ongoing discussions about fabrication units and design centers. The Engineering Services sector surged 7.35% yesterday, partly driven by optimism around electronics manufacturing and chip design opportunities. This sector remains a key watchlist item for long-term investors betting on India's manufacturing renaissance.
Indian startups collectively raised $312 million during the week ending October 26, though this marks a 50% decline from previous weeks amid festive season slowdown:
Q3 2025 Funding Snapshot: Overall startup funding slipped 30% year-over-year in Q3, reflecting global venture capital conservatism and focus on profitability over growth-at-any-cost. However, late-stage rounds (Series C+) are holding up better, indicating mature startups with proven business models continue attracting capital.
MTR Foods parent Orkla India IPO opened for subscription on October 29 with a price band of ₹695-730, aiming to raise ₹1,667.52 Crores through a complete offer-for-sale by promoters. Day 1 subscription status showed 44% overall subscription by 1:00 PM, with retail investors subscribing 58% and employee quota oversubscribed 2.3x. The GMP (grey market premium) has corrected, suggesting cautious investor sentiment toward pure OFS deals without fresh capital infusion for growth.
Sectoral Ripple Effects: The consumer-tech funding momentum could benefit listed players in digital content (Nazara Technologies) and wealth management (Angel One, 5paisa) through increased competitive validation and ecosystem expansion.
Japan's benchmark Nikkei 225 surged past 50,000 for the first time ever, gaining 2.09% to 51,270 on October 30 morning trades, driven by corporate governance reforms and yen weakness. This historic rally reflects multi-decade restructuring bearing fruit.
The Federal Reserve cut rates by 25 basis points as expected on October 29, but Chair Jerome Powell's commentary emphasized "no rush" for additional cuts, causing the dollar to strengthen and emerging market currencies to weaken.
Brent crude oil traded at $64.22/barrel (-0.27%), hovering near multi-month lows. This is India's "sweet spot" for reducing import bills while supporting OMC margins.
Gold prices in India corrected to ₹120,672/10gm on October 30, down from October's peak of ₹131,953/10gm. The correction from record highs suggests profit-booking after the festival season.
"Markets can remain irrational longer than you can remain solvent, but they eventually return to fundamentals. India's structural story remains intact despite short-term volatility."
— Market Commentary Theme reflecting current sentiment where fundamentals (GDP growth, corporate earnings, demographics) support higher valuations despite near-term FII flow uncertainties.
GIFT Nifty Pre-Market Signal: 26,134-26,167 | Gap-Up Expected: +80-113 points
Indian markets are set for a positive opening on Thursday, with GIFT Nifty futures indicating a gap-up opening of approximately 80-110 points above Tuesday's close of 26,053.90.
Confidence Level: MEDIUM-HIGH Primary Strategy: BUY DIPS with aggressive profit booking near resistance
Revision Note: Original bias downgraded from 7.5/10 to 6.5/10 due to FII selling reversal on Oct 29 (-₹2,540 Cr). The massive Oct 28 buying (+₹10,340 Cr) was short-lived, indicating tactical positioning rather than trend change.
FII Selling Resumes: Sharp reversal to -₹2,540 Cr selling on Oct 29 after Oct 28 buying spike (Weight: 20%)
Resistance Zone: Nifty approaching 26,100-26,200 resistance after rally (Weight: 10%)
VIX Complacency: India VIX at 11.98 (extremely low) signals volatility risk (Weight: 10%)
Rupee Weakness: USD/INR at 88.35, testing psychological levels (Weight: 3%)
Fed Uncertainty: Powell's hawkish "no rush" tone on rate cuts (Weight: 2%)
Expectation: Gap-up opening followed by consolidation and profit booking near resistance zones; market digests recent gains while awaiting FII flow confirmation
Description: FII reversed from +₹10,340 Cr buying on Oct 28 to -₹2,540 Cr selling on Oct 29 within 24 hours. This ₹12,880 Cr sentiment swing suggests the buying was tactical/derivative-driven, not conviction-based.
Consequence: Market could correct 2-3% toward 25,400-25,600 levels over next 3-5 sessions. Gap-up opening may trap bulls.
Description: Nifty approaching 26,150-26,200 resistance zone after strong rally from 25,800 levels. Multiple tests of resistance often lead to profit booking.
Consequence: Sharp profit-booking toward 25,980-25,920 (130-230 point downside). Leveraged long stop-losses could accelerate decline.
Description: India VIX at 11.98, extremely low levels suggesting market complacency. Low VIX historically precedes sharp volatility spikes within 3-5 trading days.
Consequence: Sudden volatility spike could lead to 1-2% intraday swings. Options premiums would surge, catching unhedged positions.
Description: Fed Chair Powell signaled "no rush to cut rates" causing USD strength. This could pressure emerging market flows further.
Consequence: Dollar strength, emerging market selloff, FII flows worsen. Rupee pressure intensifies.
R3 (Major): 26,280 - "Recent swing high, strong barrier" R2 (Intermediate): 26,200 - "Psychological round number resistance" R1 (Immediate): 26,150 - "Intraday resistance, needs volume to break"
S1 (Immediate): 25,980 - "Gap-up opening base, critical short-term support" S2 (Intermediate): 25,900 - "Previous consolidation zone" S3 (Major): 25,800 - "Strong support, 20-day EMA zone"
Breakout Trigger (Bullish): Close above 26,180 with volume >300M shares Target: 26,300 → 26,400
Breakdown Trigger (Bearish): Close below 25,950 with high volume Target: 25,820 → 25,750
OVERALL RISK LEVEL TODAY: MODERATE-HIGH (Elevated from MODERATE)
Indian markets are set for a positive opening backed by GIFT Nifty indicating an 80-110 point gap-up. However, caution is warranted as FIIs reversed to net selling of ₹2,540 Crores on Oct 29, just 24 hours after massive ₹10,340 Cr buying. This dramatic swing suggests the previous day's buying was tactical rather than conviction-based.
The Saving Grace: DII buying of ₹5,693 Crores (second-highest in October) prevented market decline and demonstrates strong domestic institutional support. October MTD, DIIs have pumped ₹37,563 Crores into Indian equities, averaging ₹2,087 Cr daily.
Today's Strategy: Use gap-up opening to book 40-50% profits on existing longs held from lower levels (25,800-25,900). Then wait for dips to 25,980-26,000 zone for fresh accumulation in quality DII-supported names (HDFC Bank, ICICI Bank, Reliance, TCS). Avoid chasing momentum near resistance (26,150) without volume confirmation. Maintain disciplined stop-losses at 25,980 and lighter position sizes (50-60% of normal) given the FII uncertainty and low VIX complacency setup.
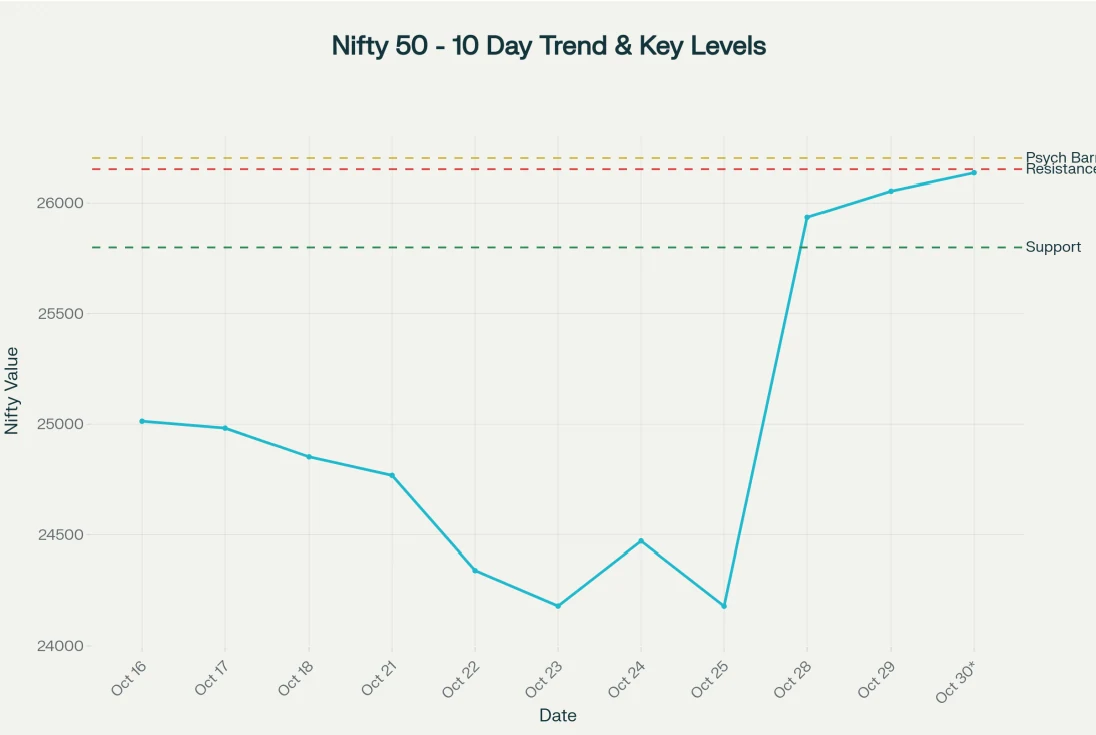
Oorjita FinAI Market Dashboard - October 30, 2025: Nifty approaches critical 26,150 resistance after FII reversal; Engineering Services leads broad-based sectoral rally
Oorjita FinAI Breadth & Volatility Analysis - October 30, 2025: Strong market breadth (2.33 A/D ratio) contrasts with complacency-level VIX at 11.98, signaling potential volatility ahead
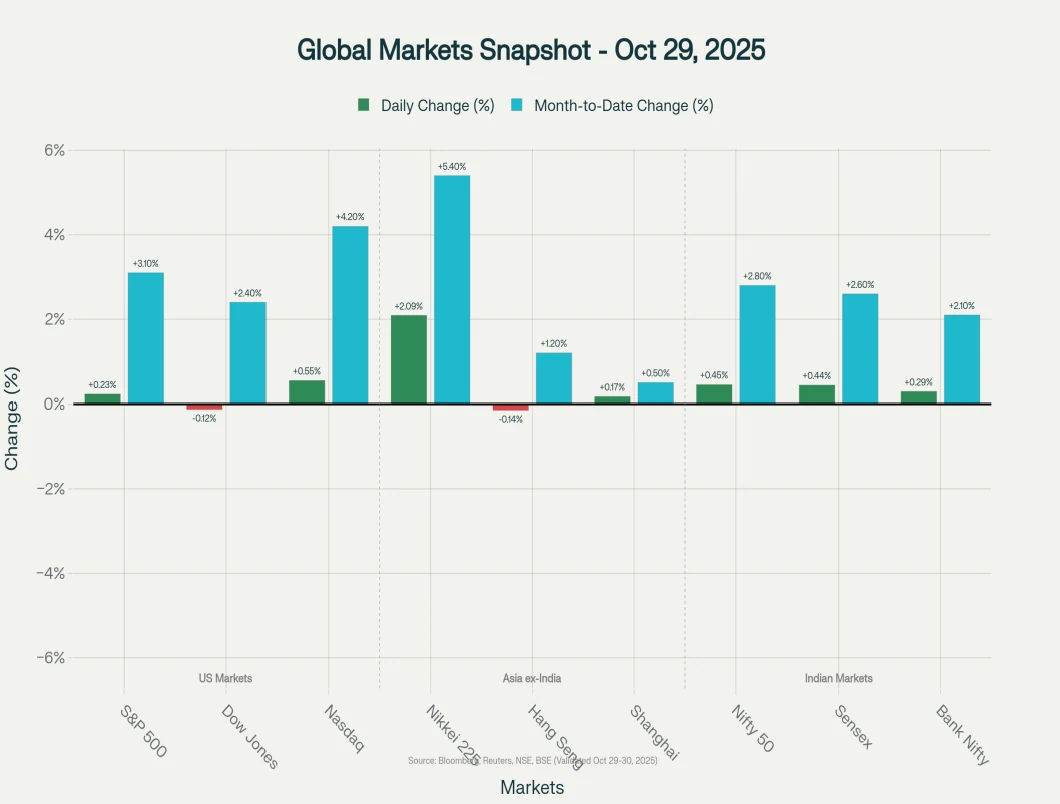
Oorjita FinAI Global Markets Dashboard - October 29-30, 2025: Nikkei leads with historic +5.4% monthly gains; Indian markets show resilient +2.8% MTD performance amid global volatility
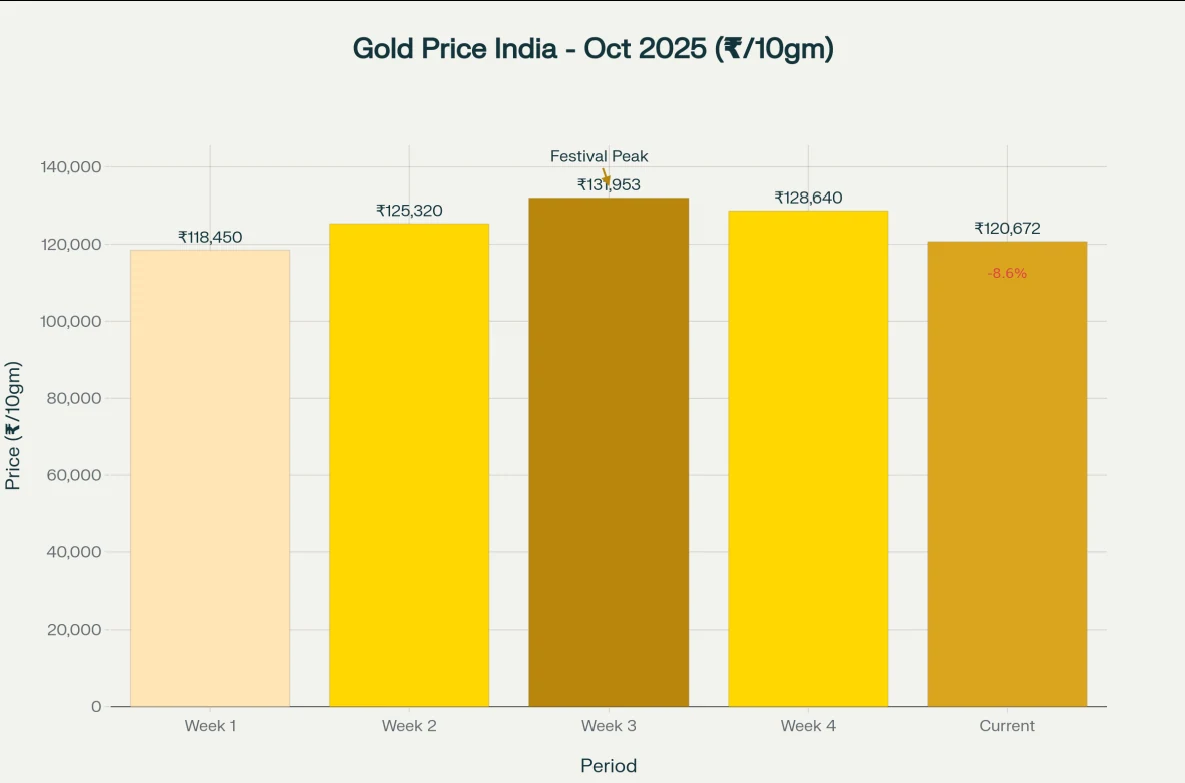
Oorjita FinAI Commodities & Currency Tracker - October 30, 2025: Crude at $64.22 favors India margins; Rupee tests 88.35; Gold corrects 8.6% from festival peak
DISCLAIMER: This newsletter is for informational and educational purposes only and should not be construed as investment advice. Market conditions can change rapidly and past performance is not indicative of future results.
All data has been validated through multiple official sources (NSE, BSE, Reuters, Bloomberg) as per Oorjita FinAI's strict verification protocols. However, Oorjita FinAI Services does not guarantee 100% accuracy of third-party data and is not liable for any losses incurred based on this analysis.
