Indian markets brace for the most volatile trading day of October as monthly F&O expiry coincides with fragile market sentiment and persistent foreign institutional selling.

This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Friday, 31 October 2025, 8:38 AM IST.

Despite flat index performance, more stocks declined (1672) than advanced (1494), indicating weak internal market strength. This suggests the market move was concentrated in a few heavyweight stocks.

*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.

Gift Nifty opened 22.50 points weak this morning (25,641), yet cash market closed at 25,725—an 84-point premium recovery. This wasn't organic buying; it was short-covering catalyzed by absence of fresh FII selling.
What's Different Today: October 31 marks monthly F&O expiry, historically the most volatile trading session where derivative positions must be squared off by 3:30 PM.
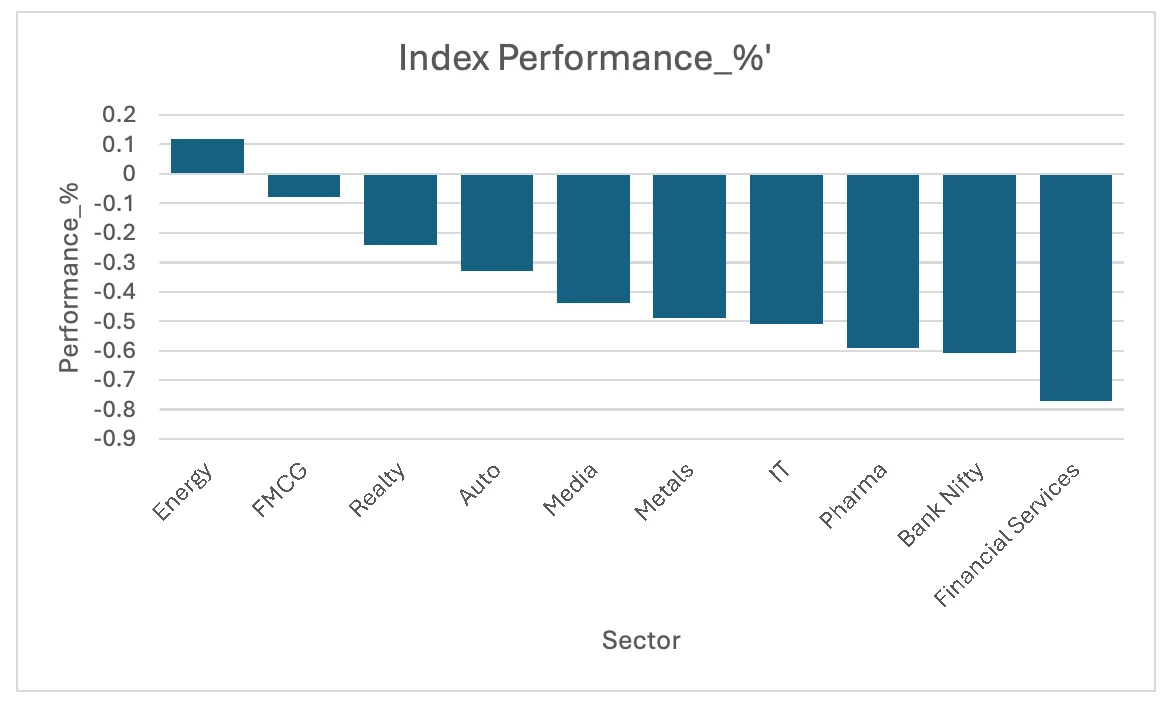
Yesterday's Sectoral Carnage Analysis: Nifty Energy (+0.12%) stood alone in positive territory, with PSU energy stocks ONGC, BPCL displaying defensive resilience as crude oil's decline to $64.49/barrel improved refining margins.
Why FIIs Are Fleeing India Now: Multiple structural forces converge—Fed Chair Powell's October 29 hawkish pivot strengthens the US dollar globally through interest rate differentials, making dollar-denominated US Treasuries yielding 4%+ more…
Stock Selection: Short Bank Nifty and financial stocks; avoid shorting IT stocks (rupee benefit provides cushion)
Indian markets brace for the most volatile trading day of October as monthly F&O expiry coincides with fragile market sentiment and persistent foreign institutional selling. After yesterday's brutal 176-point decline that saw Nifty close at 25,877.85 near the day's low—a classic bearish distribution pattern—GIFT Nifty futures trading around 26,022-26,042 suggest a modest gap-up opening of 50-80 points, offering temporary relief but no conviction.
Big Tech Carnage Reverberates: Wall Street's three major indices retreated Thursday with Nasdaq Composite leading losses as Meta and Microsoft shares tumbled on escalating concerns over surging AI spending consuming profits faster than revenue growth. The S&P 500 closed virtually flat at 6,890.59 (-0.30 pts), while Dow Jones slipped 74 points (-0.16%) to 47,632. Federal Reserve Chair Jerome Powell's hawkish commentary that December rate cuts are "far from a done conclusion" rattled investor confidence in the high-valuation tech sector.
India IT's Rupee Paradox Deepens: Despite the rupee weakening to 88.6048—which mechanically boosts IT export margins by 40-50 basis points—Nifty IT declined 0.51% yesterday as relentless FII selling pressure overrode fundamental currency tailwinds. With Q3 results season commencing mid-November, IT majors like Infosys, TCS, and Wipro trading at reasonable 25-28x PE could become accumulation candidates.
IPO Activity Frozen by Volatility: No significant funding announcements, venture capital deals, or IPO developments materialized in the past 24 hours as startups and investment banks adopt a defensive posture amid October's market turbulence. The normally vibrant late-October pre-Diwali IPO window has slammed shut, with grey market premiums (GMPs) for upcoming listings remaining subdued.
Institutional Flow Reversal Chills Primary Markets: The watershed moment came yesterday when combined institutional flows turned negative (₹608 Cr net outflow)—the first time in October that DII buying (₹2,469 Cr) failed to fully offset FII selling (₹3,078 Cr). This breakdown signals a fundamental shift in market dynamics.
Yesterday's Sectoral Carnage Analysis: Nifty Energy (+0.12%) stood alone in positive territory, with PSU energy stocks ONGC, BPCL displaying defensive resilience as crude oil's decline to $64.49/barrel improved refining margins. However, nine out of ten major sectors bled red—Nifty Financial Services leading the rout with -0.77% decline, catastrophic given its 30%+ Nifty weight.
Today's F&O Expiry Wildcards: Bank Nifty at 58,031 faces make-or-break support at 58,000—a decisive break could trigger panic selling to 57,500 as banks remain under FII distribution pressure (HDFC Bank, ICICI Bank heavy selling noted).
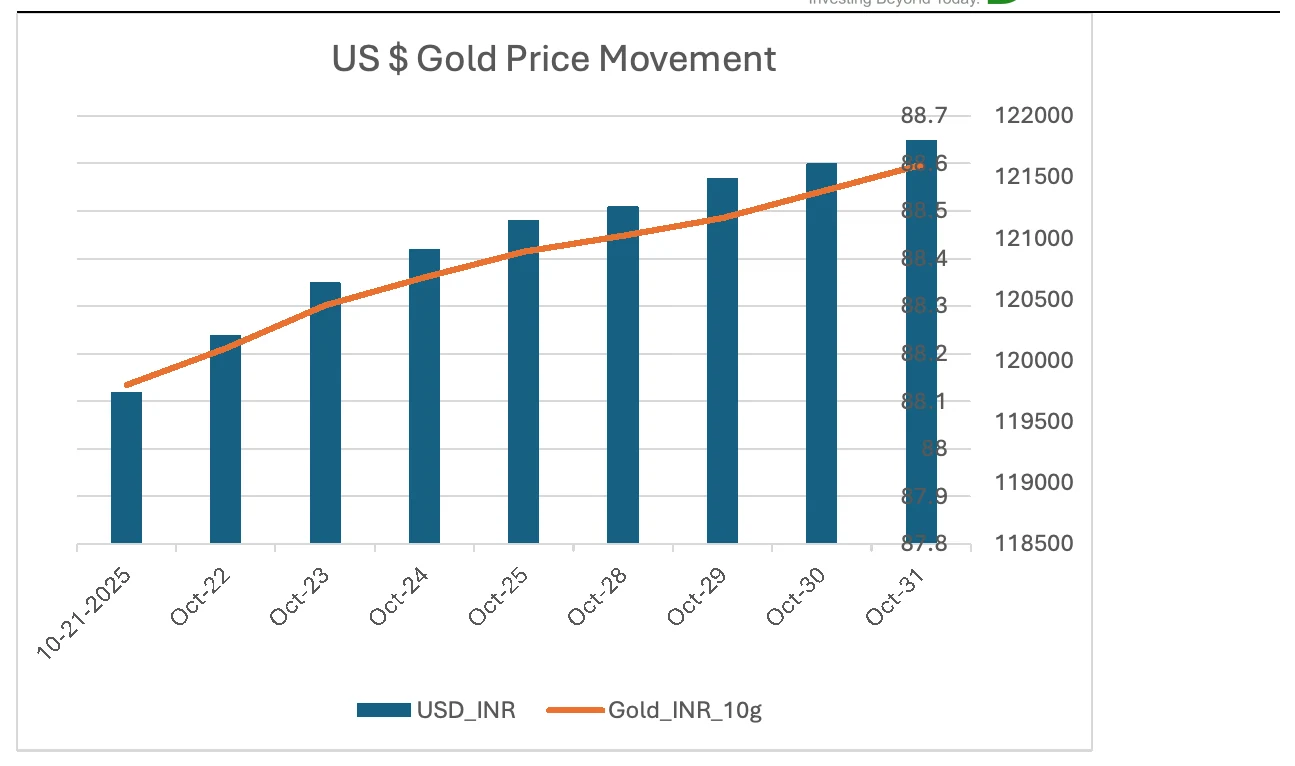
Rupee's Capitulation Beyond 88.60: The Indian rupee breached the critical 88.50 psychological level to close at 88.6048 (FBIL official 1:00 PM rate), marking fresh multi-week lows driven by accelerating FII equity outflows (₹3,078 Cr), Fed Chair Powell's hawkish "no December cut guarantee" stance strengthening the dollar globally, and broad emerging market currency weakness.
Gold's Safe-Haven Surge Continues: Domestic gold prices climbed to ₹121,382 per 10 grams (up ₹218, +0.18%) on October 31, extending the 1.48% surge from October 29 as investors flee equity volatility into traditional stores of value.
Asian Markets Send Mixed Signals: Japan's Nikkei edged marginally higher (+0.04% to 51,146) benefiting from yen weakness, while China's markets faced pressure—Hong Kong's Hang Seng fell 0.2% and CSI 300 dropped 0.8% despite the Trump-Xi meeting producing a one-year agreement on rare earth minerals.
The Tactical Trap Confirmed: On October 28, FIIs injected a staggering ₹10,340 Crores into Indian equities, creating euphoria across market commentary—many analysts declared "the bottom is in." We cautiously labeled this "tactical/derivative-driven rather than conviction-based accumulation," advising subscribers to wait for multi-day confirmation.
The Reversal Speed Shocks: Within just 48 hours, that entire ₹10,340 Cr inflow evaporated—October 29 saw ₹2,540 Cr selling, followed by October 30's ₹3,078 Cr outflow, completely erasing the Monday spike. This violent reversal pattern teaches a fundamental lesson: single-day massive flows should be treated as noise requiring 3-5 day validation before altering strategic positioning.
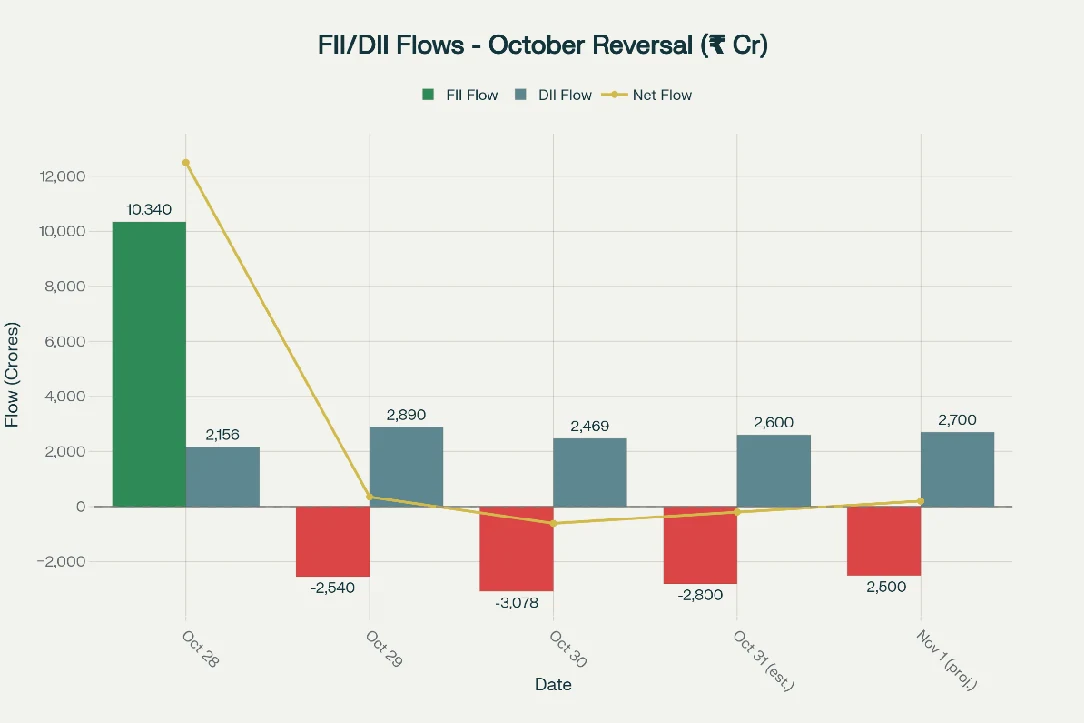
October's Institutional Divergence Math: Through October 30 (20 trading days), DIIs have injected ₹40,033 Crores at a consistent daily average of ₹2,002 Cr, positive on 18 out of 20 sessions. Conversely, FIIs have pulled out substantial amounts, creating a structural imbalance that produces distinctive market character: limited upside (capped at resistance zones like 26,150-26,200), good downside support (DIIs prevent crashes), but ultimately range-bound consolidation until foreign flows reverse.
Why FIIs Are Fleeing India Now: Multiple structural forces converge—Fed Chair Powell's October 29 hawkish pivot strengthens the US dollar globally through interest rate differentials, making dollar-denominated US Treasuries yielding 4%+ more attractive than emerging market equities. India's premium valuations (Nifty P/E at 22.77x vs historical average ~20x) offer minimal margin of safety during global risk-off phases.
Technical Setup Screaming Danger: Yesterday's price action formed a textbook bear flag pattern with ominous implications for today's expiry session:
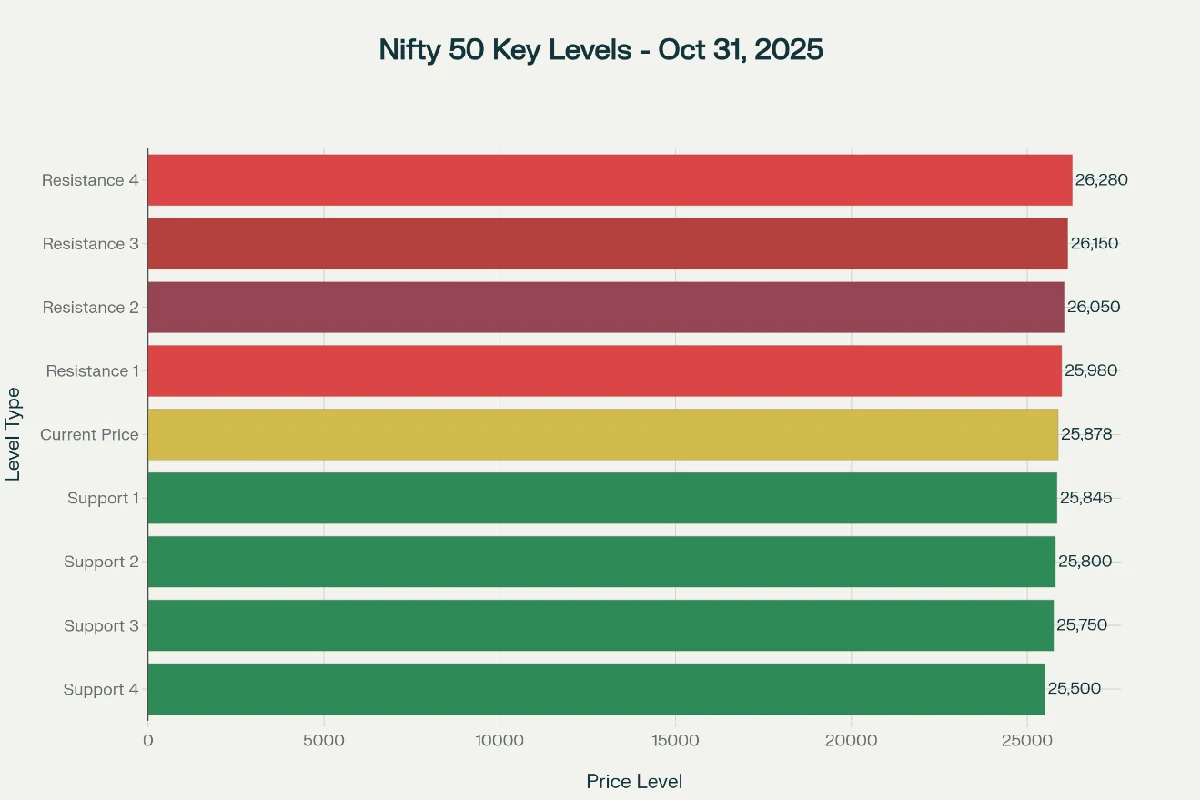
Critical Level for Today: The 25,800-25,850 zone has become the Rubicon—if it holds during today's expiry volatility, expect relief bounce toward 26,000-26,050 as shorts cover and dip buyers emerge. However, if it breaks decisively (15-minute close below 25,800), technical acceleration toward 25,500-25,650 becomes highly probable.
Triggers: Opens flat-to-gap-down below 25,900 despite GIFT Nifty positivity, FII selling continues above ₹2,500 Cr, 25,845 critical support breaks in first hour, F&O expiry selling pressure dominates.
Expectation: Volatile, whipsaw-prone range-bound session between 25,780-25,950 as monthly expiry creates bidirectional violent swings. Classic F&O expiry pattern where market makers defend max pain levels (likely 25,800-25,900 zone) and retail traders get chopped up in both directions.
Triggers: Opens strong gap-up above 25,950, FII data shows surprise positive flow, rupee strengthens sharply back below 88.50, massive short covering rally ahead of weekend.
Investment Thesis for the Week: With F&O expiry creating short-term noise, focus shifts to positioning for November's potential catalysts—RBI MPC (Nov 3), Q2 earnings acceleration, and possible FII flow reversal. This watchlist emphasizes quality defensives that benefit from structural tailwinds (weak rupee, festive demand) while avoiding momentum traps in FII-heavy selling zones.
accumulate (+1.87% in Infosys). Q3 guidance upgrades likely as clients accelerate AI/cloud modernization projects.
Entry Zone: 58,300-58,500 (on any bounce from current 58,031) Target 1: 57,500 (quick 800-point move) Target 2: 56,800 (extended downside) Stop-Loss: 58,950 (daily close basis) Position Size: 30% of normal (F&O expiry volatility adjustment) Hold Duration: 3-5 trading days maximum
13.5 13 12.5 X IV 12 A ID 11.5 N I 11 10.5 10 Oct-23 Oct-24 Oct-25 Oct-28 Oct-29 Oct-30 Oct 31 (est.) Date
4500 30 4000 25 3500 20 3000 e c irP 2500 15 _ t n er 2000 10 r u C 1500 5 1000 0 500 0 -5 TCS Infosys HCL Tech Wipro Tech Mahindra Stock
Current_Price Upside_% PE_Ratio FII_Stake_Change_%
DISCLAIMER: This newsletter is for informational and educational purposes only and should not be construed as investment advice. Market conditions can change rapidly and past performance is not indicative of future results.
All data has been validated through multiple official sources (NSE, BSE, Reuters, Bloomberg) as per Oorjita FinAI's strict verification protocols. However, Oorjita FinAI Services does not guarantee 100% accuracy of third-party data and is not liable for any losses incurred based on this analysis.
