Our morning bulletin anticipated a range-bound session with a positive bias, driven by favorable GDP data and GST reform hopes. While the market did open higher, it failed to sustain momentum, succumbing to selling pressure in the final hours.
MK
Dr. Murali KalyanaramanGlobal CFO · 30+ years in corporate finance · Chartered Accountant (ICAI) · 6 min read
Signal panelThe research, before the reading · 6 min full note
01
Bank Nifty: The index remains weaker, having broken key moving averages.
02
India VIX: The volatility index remained relatively stable, suggesting that while there was expiry-related churn, widespread panic was absent.
03
DII Net Activity: +₹4,344.93 Crore [Provisional] The market breadth was positive, with more stocks advancing than declining, indicating resilience in the broader market beyond the top 50 names.
04
Open Interest (OI): Open Interest is the total number of outstanding derivative contracts (like futures or options) that have not been settled.
1Feedback on Morning Newsletter & EoD Reconciliation
Our morning bulletin anticipated a range-bound session with a positive bias, driven by favorable GDP data and GST reform hopes. While the market did open higher, it failed to sustain momentum, succumbing to selling pressure in the final hours. This was primarily driven by the inaugural Tuesday expiry for Nifty F&O contracts, which induced significant volatility in heavyweight financial stocks. The initial optimism surrounding GST rate cuts did, however, provide a strong tailwind for the FMCG sector, which outperformed significantly, aligning with our morning view.
Subscriber Comments:
"The heads-up on expiry-day volatility was spot on. Helped me manage my positions better."
"Great call on the FMCG sector. Wish I had acted on it more decisively."
2Key Movements in Indian Equity Markets
Indian benchmark indices surrendered early gains to close in the red on the first-ever Tuesday F&O expiry for Nifty 50 contracts. After a positive start, late-session unwinding in banking and financial stocks dragged the headline indices lower. Broader markets, however, showed resilience, with mid-cap and small-cap indices ending in positive territory.
Validated Closing Levels (September 2, 2025):
Nifty 50:24,579.60 (-0.18%) [Official]
Sensex:80,157.88 (-0.26%) [Official]
Bank Nifty:53,661.00 (-0.63%) [Official]
Sectoral Snapshot:
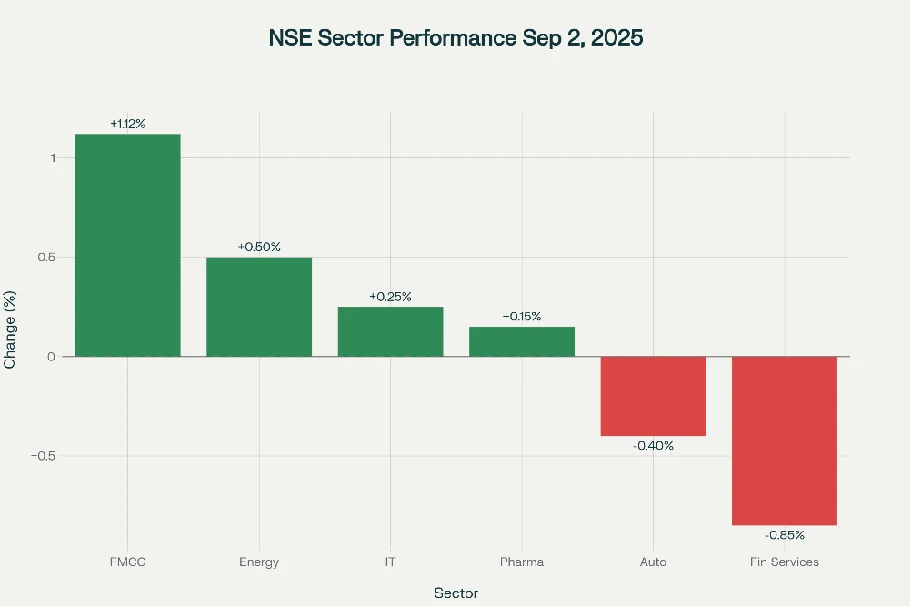
Leaders: The Nifty FMCG index was the top performer, closing with a gain of 1.12%. This rally was fueled by expectations of potential GST rate cuts on various consumer goods in the upcoming council meeting. Stocks like Nestle India and Tata Consumer Products saw significant buying interest.
Laggards: The Nifty Financial Services index was the primary drag, falling in the latter half of the session due to expiry-related pressures.
A clear divergence was visible today. While financial stocks, which have a high weightage in the Nifty 50, saw significant selling pressure due to the unwinding of derivative positions, cyclical sectors like FMCG and Realty showed strength. This highlights a market being driven more by technical, structural factors (like the new expiry day) rather than a monolithic fundamental trend.
Sector Rotation Insights
Today's session showcased a classic rotation out of high-beta financials and into defensive and consumption-themed sectors. The FMCG sector's outperformance, supported by robust volumes, suggests that investors are positioning themselves for potential consumption-boosting government policies. The advance-decline ratio remained positive, indicating underlying strength in the broader market despite the headline index decline.
Technical Levels Analysis
Nifty 50: The index faced resistance near the 24,750 level before correcting. Immediate support is now seen around the 24,500 mark, which aligns with the maximum Put OI for the current expiry. A break below this could see a test of the 24,400 support zone.
Bank Nifty: The index remains weaker, having broken key moving averages. It faces immediate resistance at the 54,000–54,500 zone, while the 53,500 level acts as a crucial support.
3Economic Data & FX
There were no major domestic economic data releases today. Market focus remains on the upcoming GST Council meeting scheduled for September 3-4.
Foreign Exchange (FX) Update:
INR/USD Reference Rate (FBIL): 88.16 The Indian Rupee has been trading near its all-time lows, with the dollar hovering around the 88 mark, influenced by a combination of a stronger dollar globally and capital outflows.
4Unique & Original Market Insights
Market Sentiment & Options Positioning
Put-Call Ratio (PCR): The Nifty Put-Call Ratio (based on Open Interest) stood at 0.90, suggesting that call writers were more active than put writers, indicating a cautiously bearish to neutral sentiment heading into the close.
• Options OI Data (Sep 2 Expiry):
Max Call OI: Concentrated at the 25,000 strike, acting as a significant ceiling for the market.
Max Put OI: Built up at the 24,500 strike, forming a strong support base for the session.
India VIX: The volatility index remained relatively stable, suggesting that while there was expiry-related churn, widespread panic was absent.
Liquidity & Breadth
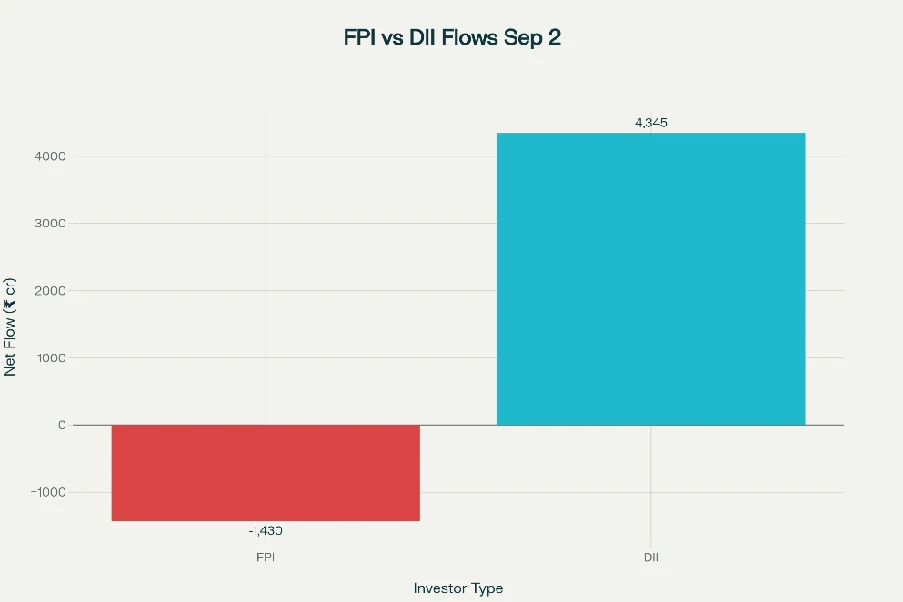
Foreign Portfolio Investors (FPIs) were net sellers, while Domestic Institutional Investors (DIIs) continued their buying spree, providing a cushion to the market.
FPI Net Activity:-₹1,429.71 Crore [Provisional]
DII Net Activity:+₹4,344.93 Crore [Provisional] The market breadth was positive, with more stocks advancing than declining, indicating resilience in the broader market beyond the top 50 names.
Data-Driven Trade Ideas
• Stocks to Watch:
a. Nestle India: Showed strong upward momentum (closed up 2.22%) on high volume, breaking out on hopes of GST cuts. Could see continued interest. b. Power Grid: A top Nifty gainer (closed up 2.20%) with consistent buying interest. It is trading near its 52-week high, showing strong relative strength. c. Mahindra & Mahindra: Declined on reports of a potential GST hike on luxury EVs. Remains a stock to watch for further developments on this news. d. Reliance Industries: Gained about 1% after a target price upgrade, lifting the energy sector. Its performance will be key for the index's direction.
e. Amanta Healthcare: With its IPO subscription seeing strong demand and a GMP of ~9.5%, it will be on the radar for its listing day performance.
Options Strategy: Given the current setup and the resistance at 25,000, a Bear Call Spread for the next weekly expiry could be considered by experienced traders if Nifty fails to cross its recent highs. This involves selling a Call option at a resistance level (e.g., 24,800) and buying a higher strike Call (e.g., 25,000) to hedge the risk.
Macro & Global Perspective
Global market sentiment remains mixed, with investors cautious about potential US tariffs on Indian goods. Domestically, the market is keenly awaiting the outcome of the GST Council meeting, which is expected to be the next major trigger.
Educational Segment: Term of the Day
Open Interest (OI): Open Interest is the total number of outstanding derivative contracts (like futures or options) that have not been settled. For options traders, high OI at a particular strike price (like the 25,000 Call for Nifty) often indicates a point of strong resistance or support, as many market participants have a vested interest at that level. A change in OI can signal shifts in market sentiment.[22]
5Closing Remarks & Subscriber Engagement
Today’s session was a testament to the new market dynamics brought about by the shift in the Nifty expiry day. While the headline numbers show a modest decline, the underlying sectoral churn tells a more nuanced story of rotation into defensives.
Forward-Looking Levels:
Nifty Support:24,500 / 24,400
Nifty Resistance:24,750 / 25,000
Engage with Us:
What are your thoughts on the new Tuesday expiry? Do you think it will lead to more volatility or better hedging opportunities? Let us know your views! All provisional data points will be reconciled in our morning update.
Charts & Visual Elements
Here are two key charts from today's session:
Disclaimer: This newsletter is for informational and educational purposes only and does not constitute investment advice. Data marked as [Provisional] is subject to revision.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Tuesday, 2 September 2025, 8:57 PM IST.