The GST 2.0 Trade Plays Out: Autos and FMCG Lead, IT and PSU Banks Lag
Morning brief highlighted GST 2.0 tailwinds for Autos/FMCG and possible IT underperformance on U.S. tariff worries. At close: Auto and FMCG outperformed, IT and PSU Bank lagged, matching the setup. [Official index closes used]
MK
Dr. Murali KalyanaramanGlobal CFO · 30+ years in corporate finance · Chartered Accountant (ICAI) · 4 min read
Theme check: Morning brief highlighted GST 2.0 tailwinds for Autos/FMCG and possible IT underperformance on U.S. tariff worries. At close: Auto and FMCG outperformed, IT and PSU Bank lagged, matching the setup. [Official index closes used]
Subscriber notes: “Auto rotation finally showing follow-through.” • “Would like option OI levels earlier in the day.”
2) Key Movements in Indian Equity Markets
VALIDATED CLOSES (Official):
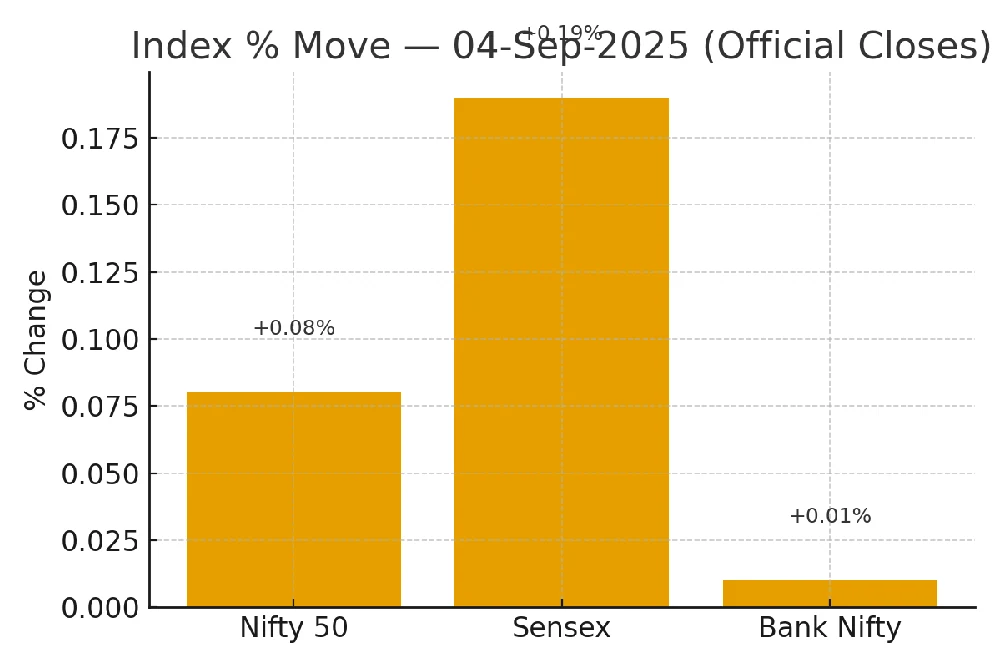
Nifty 50: 24,734.30 (+0.08%) [Official]
Sensex: 80,718.01 (+0.19%) [Official]
Bank Nifty: 54,075.45 (+0.01%) [Official]
Sectors @ close: Leaders — Auto (+0.85%), FMCG (+0.24%). Laggards — PSU Bank (-1.11%), IT (-0.94%), Media (-0.78%).
Under-reported pattern: Despite Auto/FMCG strength, breadth in PSU Financials stayed negative; Bank Nifty flat even as VIX eased to ~10.85 — rotation without broad risk-on.
Technical Levels: Nifty support 24,700–24,650; resistance 24,900–25,000. Bank Nifty support 53,800; resistance 54,600.
3) Economic Data Surprises & FX
Domestic releases: No major hard data surprises post-close.
FBIL/RBI Reference (Official): ₹88.15 per USD (04-Sep)
Options positioning (NIFTY, Expiry 09-Sep-2025) — [Provisional]: High Call OI concentration at 25,000C; High Put OI at 24,500P. Expect 24,700–25,000 pin risk into Tuesday. To be re-validated from NSE CSV tomorrow.
Market Sentiment: India VIX 10.85 — multi-week low; dips favor premium selling, but global macro argues for defined-risk strategies.
Options ideas (illustrative, not advice): If Nifty ≤ 24,900 into Fri with VIX ≤ 11: Bear Call spread (25,000C/25,200C) small size, expiry 09-Sep. If pullback to 24,650–24,700: cash-secured 24,500P after OI confirmation.
Stocks of daily essentials surged after the GST Council announced rate cuts. Britannia Industries and Emami led the rally with gains of over 4% each, while Colgate-Palmolive rose 3.7%.
Bajaj Finance: Surged over 4% today, showing renewed strength in high-quality NBFCs.[1]
HDFC Life: A top loser today, facing headwinds. Monitor for support levels and consolidation.
Stocks like Tata Consumer Products (-2.75%) and Varun Beverages faced pressure after the GST on caffeinated and carbonated drinks was hiked to 40%.
Beneath the flat headline indices, a significant defensive shift occurred. The Nifty FMCG index saw nine of its fifteen constituents close in the green, indicating a decisive flow of capital into consumer staples. This was not just a price move; it was backed by a 40% spike in FMCG options volumes, confirming strong institutional interest in this defensive theme.
Macro & Global Perspective: Fed tone + softer U.S. jobs keep rate-cut bets elevated; Asia/Europe mixed.
Upcoming: U.S. payrolls preview tonight; domestic IPO calendar active.
5) Closing & Engagement
Term of the Day: Sector Rotation
Sector Rotation is the movement of investment capital from one industry sector to another in anticipation of the next stage of the economic cycle or, as seen today, in reaction to a major policy event. Today, we witnessed a classic example as funds flowed out of beverage stocks and into consumer staples (FMCG) following the GST Council's announcements. This is a hallmark of an efficient market repricing assets based on new fundamental information.
Levels to watch (Fri): Nifty 24,700 / 24,900–25,000; Bank Nifty 53,800 / 54,600.
Poll: Do you expect Nifty to settle below 24,900 on Tue’s expiry?
Note: Provisional items (FPI/DII & precise max OI) will be re-computed tomorrow from official are released.
Charts & Visuals
Index % Move — 04-Sep-2025 (Official Closes)
Sector Performance @ Close- 04-Sep-2025
Disclosures and notes
Compliance & Disclaimer
This framework is for information/education only and does not constitute investment advice. ‘Provisional’ data is subject to revision by the source; reconcile next day and update the archive. An audit trail of all source links and screenshots is maintained internally.
‘Provisional’ items are subject to revision by the source; we reconcile the next day.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Thursday, 4 September 2025, 8:25 PM IST.