
FII vs DII weekly (Sep 21–27)
Last week was defined by a significant market correction, driven by relentless FII selling and global policy concerns. However, early indicators this morning suggest a potential shift in sentiment.

- 01
Overnight Highlights: On Friday, Indian indices closed deep in the red, with the Nifty 50 at
- 02
Key Watch Factors: Today is the deadline for 17 multinational drugmakers to comply with the US drug price policy, which could lead to high volatility in the pharma sector.
- 03
Actionable Trigger: The expansion of Apple's supply chain puts ancillary component manufacturers on the watchlist.
- 04
Economic Data: Auto sales numbers for September will be released starting October 1, providing insights into festive season demand.
Good morning. Last week was defined by a significant market correction, driven by relentless FII selling and global policy concerns. However, early indicators this morning suggest a potential shift in sentiment. Here’s your validated briefing on what’s moving the markets today.
After a brutal week that saw the Nifty 50 fall 4.1% and close below the critical 24,700 mark for the sixth straight session, today offers a glimmer of hope.
- Overnight Highlights: On Friday, Indian indices closed deep in the red, with the Nifty 50 at 24,654.70 (-0.95%) and the Sensex at 80,426.46 (-0.90%). The Bank Nifty was hit particularly hard, closing at 54,389.35 (-1.07%). The selling was broad-based, triggered by concerns over US tariff policies targeting the Indian pharmaceutical sector.
- What’s Different Today? In a notable deviation from last week's bearish trend, GIFT Nifty futures are trading in the green at 24,809.00 (as of 7:07 AM IST), suggesting a positive opening for Indian markets. This is supported by positive cues from US futures, with Dow and Nasdaq futures trading higher. Oil slipped below $70 — small tailwind; Gold near record highs — risk-hedge bid; INR focus into RBI week — bias still fragile.
- Key Watch Factors: Today is the deadline for 17 multinational drugmakers to comply with the US drug price policy, which could lead to high volatility in the pharma sector. FII activity will be closely monitored after they sold over ₹30,000 crore worth of equities in September. Tariff overhang: US 100% tariff on branded drugs becomes the swing factor for Nifty Pharma sentiment.
The technology sector remains a hub of strategic activity despite market volatility.
- Apple Deepens India Roots: Apple has significantly expanded its Indian supply chain to include nearly 45 companies, incorporating local component makers and creating around 350,000 jobs. This move, driven by geopolitical shifts, signals a long-term strategic commitment to manufacturing in India.
- India's Semiconductor Push: The government's focus on building a domestic semiconductor ecosystem is gaining traction. This long-term initiative aims to reduce import dependency and establish India as a global electronics manufacturing hub.
- Actionable Trigger: The expansion of Apple's supply chain puts ancillary component manufacturers on the watchlist. Regulatory announcements related to the PLI scheme for electronics and semiconductors will be key triggers for this space.
3Funding Radar
The primary market is buzzing with activity, providing a counter-narrative to the secondary market's recent weakness.
- Mega IPO Week: The market is set for 21 new IPOs this week. The highlight is the WeWork India IPO, which aims to raise ₹3,000 crore and will open for subscription with a price band of ₹615-₹648 per share.
- New Listings & Openings: Today, Atlanta Electricals and Ganesh Consumer Products will make their stock market debut. Additionally, six SME IPOs, including Chiraharit and Suba Hotels, will open for subscription.
- Sectoral Impact: The strong pipeline of IPOs, especially in the real estate (WeWork) and consumer sectors, indicates healthy investor appetite for new growth stories and could channel liquidity into the market.
4Market Movers & Watchlist
- Pharmaceuticals: The pharma sector is on high alert. The Indian Pharmaceutical Alliance (IPA) has officially responded to US tariff threats, stating that such a move would jeopardize America's drug security. Stocks like Zydus Life, Sun Pharma, and Lupin will be in focus as the US policy deadline hits today. Pharma: tariff overhang; underperformance likely on spikes until clarity on implementation timeline
- Banking: HDFC Bank remains on the watchlist from our weekly summary due to oversold conditions. The entire banking sector's performance will be crucial, given the Bank Nifty broke its 100-day EMA last week.
- Reliance Industries: The stock showed resilience last week. With crude oil prices firm, watch for movement around its key technical support level of ₹2,850.
- IT: oversold bounces possible; follow-through depends on orders/pricing signals.
- Banks: Bank Nifty near 54k support cluster; watch 54,000–54,100 hold; breakdown risks 53,700–53,800.
5Deep Dive – Pharma's Moment of Truth
The hot topic remains the US tariff threat on Indian pharmaceuticals. Last week's market decline was a direct reaction to the announcement of steep tariffs. However, the narrative has evolved. The Indian Pharmaceutical Alliance has taken a firm stand, arguing that India's generic drug supply is critical to the US healthcare system and that tariffs would be "unwise".
This sets up a high-stakes geopolitical and economic standoff. With today being the deadline for compliance set by the US, the market is bracing for impact. The outcome will not only determine the fate of India's $25 billion pharma export industry but also test the resilience of a sector that has been a defensive pillar for investors. The key investor takeaway is to watch for official statements and differentiate between companies with high US market exposure versus those with a more diversified or domestic focus.
Investor takeaways: (i) Underweight names with >35% US branded/patented mix; prefer diversified API/CRAMS; (ii) Weaker INR offers partial cushion but FDA/channel risks can overwhelm; (iii) Actionable: accumulate diversified CRAMS on 10–15% drawdowns; avoid binary U.S. price-controlled exposures until rule text/waivers clarified.
6What to Watch Today
- Economic Data: Auto sales numbers for September will be released starting October 1, providing insights into festive season demand.
- IPO Listings: Debut of Atlanta Electricals and Ganesh Consumer Products.
- Global Cues: Reaction to the US market's positive futures and Asian market trends.
- Pharma Sector: Any news or official communication regarding the US tariff situation.
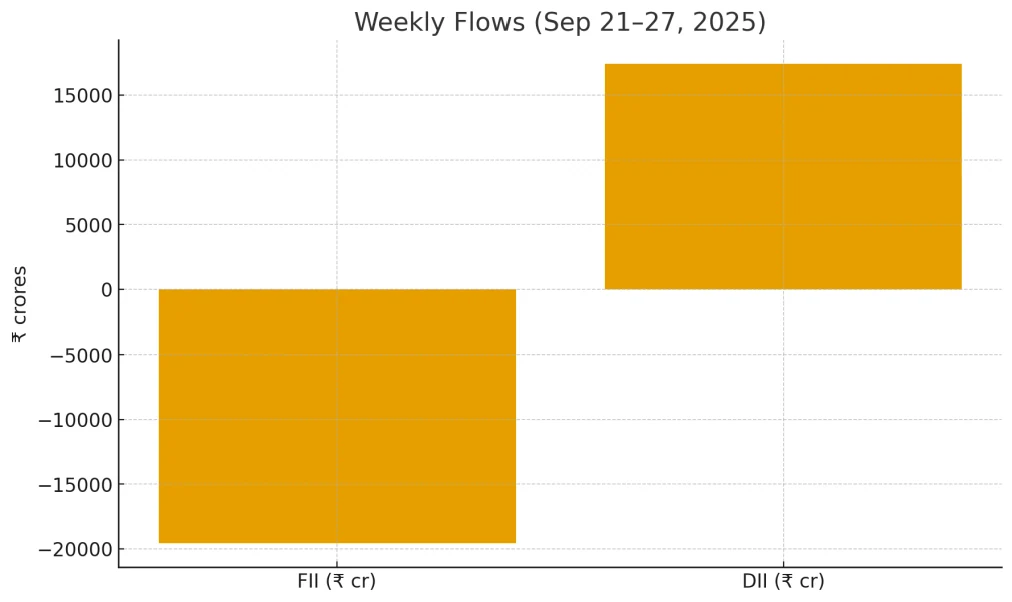
7Chart of the Day — FII vs DII weekly (Sep 21–27)
FII: –₹19,570 cr vs DII: +₹17,411 cr
8Quote of the Day
"India is expected to continue to dominate the global technology services market driven by the availability of massive tech, engineering talent as well as high-quality business and digital transformation impact on global clients." — Raja Lahiri, Partner and Technology Industry Leader, Grant Thornton Bharat.
9Quick Bytes (Global/Off-Radar)
- Shutdown risk may delay key U.S. data — event volatility elevated.
- Gold’s ‘crowded safety’: any real-rate back-up could trigger unwind; manage trailing stops.
Compliance Disclaimer
This newsletter is for informational purposes only and does not constitute investment advice. Market data is sourced from multiple verified platforms and cross-validated as per our editorial standards. Investors should conduct independent research and consult financial advisors before making investment decisions. Oorjita FinAI Services is not liable for any investment decisions based on this content. Markets are subject to volatility and past performance does not guarantee future results.
Whatever trends you're following today: hope you're early enough to profit and wise enough to exit.
Monday, 29 September 2025
- 8:32 AMMorning callFII vs DII weekly (Sep 21–27)You're reading this
- 9:57 PMEvening reviewPositive Open Called Right; Bank Nifty Holds Support Ahead of Pharma Tariffs
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 29 September 2025, 8:32 AM IST.
Read next

Week 11: Nifty's Worst Week of 2026 as FIIs Sell ₹35,052 Crore
All four layers aligned bearish. A/D = capitulation breadth.

Bear Call Validated: Nifty Finds Its Panic Floor, Then Bounces
Morning's Bear call was directionally validated, but the intraday recovery depth was underestimated. The market found its panic floor exactly where the morning brief mapped it — and then bounced.

FMCG: The Stealth Rally Nobody Talks About
*Note: 19-Feb (Chhatrapati Shivaji Maharaj Jayanti) — FBIL did not publish a fresh forex rate (carried 18-Feb forward); NSE equity market was operational; FII/DII data present.