Positive Open Called Right; Bank Nifty Holds Support Ahead of Pharma Tariffs
Themorningbriefcorrectlyanticipatedapositiveopening,drivenbyGIFTNiftyfutureswhichpointed to a start around 24,813. The Nifty 50 indeed opened higher and touched a high of 24,791.
MK
Dr. Murali KalyanaramanGlobal CFO · 30+ years in corporate finance · Chartered Accountant (ICAI) · 4 min read
Signal panelThe research, before the reading · 4 min full note
01
Pharma Sector Watch: The morning brief highlighted the US tariff deadline for the pharma sector.
02
Bank Nifty Resilience: As watched in the morning, Bank Nifty respected its support zone and outperformed, closing up
03
Top Laggards: Nifty Media (-0.85%), Nifty Private Bank (-0.29%), Nifty Consumer Durables (-0.19%).
04
Pharma Tariff Update: Indian Pharmaceutical Alliance's pushback against US tariff threats gained traction, with analysts noting that generic drugs remain largely unaffected by Trump's 100% tariff announcement on branded pharmaceuticals.
Levels we are watching
Nifty support24,606
Nifty resistance24,791
Themorningbriefcorrectlyanticipatedapositiveopening,drivenbyGIFTNiftyfutureswhichpointed to a start around 24,813. The Nifty 50 indeed opened higher and touched a high of 24,791. However, the bullish momentum was short-lived.
Expected vs. Actual:
Expectation: A potential trend reversal after a six-day losing streak.
Actuality: The market failed to hold its morning gains, succumbing to selling pressure at higher levels. The Nifty 50 ultimately closed down 0.08%, marking the seventh consecutive day of losses and closing 178 points below the morning's futures indication. The anticipated bounce did not materialize into a definitive reversal .
Pharma Sector Watch: The morning brief highlighted the US tariff deadline for the pharma sector. Nifty Pharma ended the day with a minor loss of 0.15%, showing relative resilience, though key stocks like Dr. Reddy's Labs fell over 1%.
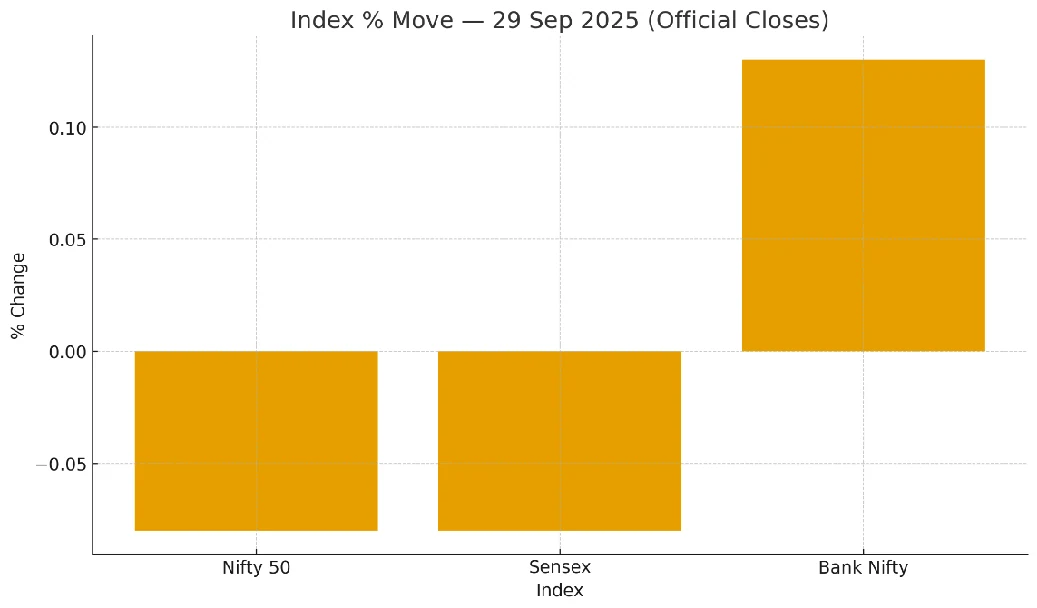
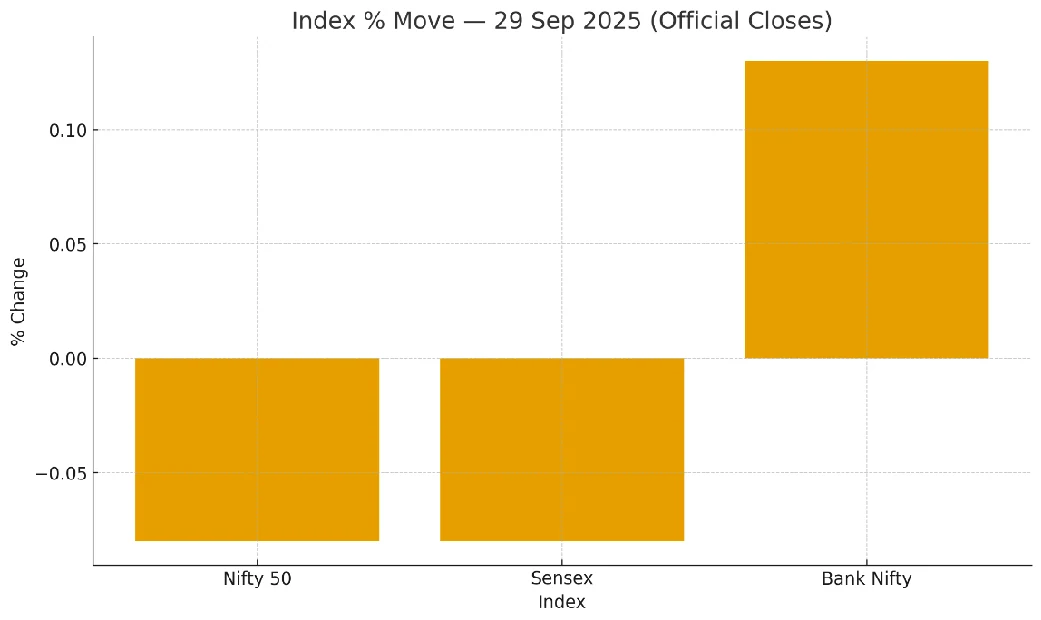
Bank Nifty Resilience: As watched in the morning, Bank Nifty respected its support zone and outperformed, closing up 0.13% . This divergence from the headline indices was a key theme of the day.
2Key Movements in Indian Equity Markets
Despite a volatile session, the headline indices closed marginally lower as a sell-off in auto and IT stocks offset gains in the banking sector.
Nifty 50:24,634.90 (-0.08%) [Official]
Sensex:80,364.94 (-0.08%) [Official]
Bank Nifty:54,461.00 (+0.13%) [Official]
Sector Rotation & Under-Reported Patterns:
Today's session was defined by a clear divergence. While the Nifty 50 and Sensex extended their losing streak to a seventh day, the Bank Nifty snapped its losing streak and closed in the green. This was largely led by strength in PSU Banks. Another key pattern was the split in broader markets:
the Nifty Midcap 100 rose 0.27%, while the Nifty Smallcap 100 fell 0.07%, indicating selective buying in mid-tier stocks even as small-caps faced pressure. This suggests a flight to quality within the broader market, not just in large caps.
Sectoral Leaders & Laggards:
Top Gainers: Nifty PSU Bank (+0.95%), Nifty FMCG (+0.18%), Nifty Financial Services (+0.13%).
Top Laggards: Nifty Media (-0.85%), Nifty Private Bank (-0.29%), Nifty Consumer Durables (-0.19%).
3Economic Data & FX
No major economic data was released today. Market participants are cautiously awaiting the outcome of the RBI's Monetary Policy Committee (MPC) meeting, which commenced today.
Currency Market:
FBIL Reference Rate: The latest available official rate is from September 19, at ₹88.3055 / USD. Today's rate is marked as [Pending].
Futures Market: USD/INR futures for the October 3 expiry were trading around 89.8075 , indicating expectations of further depreciation.
4Unique & Original Market Insights
Market Sentiment & Volatility:
The India VIX, a measure of expected volatility, cooled off by 1.68% to 11.23. A falling VIX alongside a flat-to-negative market close is an anomaly. It suggests that despite the headline drop, traders are reducing their hedges, possibly anticipating that the worst of the recent sell-off is over and that the market may stabilize around current levels.
Institutional Flows:
The tug-of-war between Foreign and Domestic institutions continues. FPIs/FIIs were net sellers, pulling out -₹2,805 crore (provisional). DIIs countered this by remaining net buyers to the tune of +₹3,690 crore (provisional), absorbing the foreign outflow.
Educational Segment
5Closing Remarks & Way Forward
The market's failure to hold its opening gains underscores a "sell on rise" sentiment. However, Bank Nifty's outperformance and the cooling VIX provide early signs of a potential base formation.
• Nifty Technical Levels:
Support: The day's low of 24,606 is the immediate support to watch. A break below this could retest the 24,500 zone.
Resistance: The day's high of 24,791 acts as a stiff resistance. A convincing close above 24,800 is needed for any bullish revival.
Pharma Tariff Update: Indian Pharmaceutical Alliance's pushback against US tariff threats gained traction, with analysts noting that generic drugs remain largely unaffected by Trump's 100% tariff announcement on branded pharmaceuticals. This provides relief to the sector's outlook.
Subscriber Engagement: Was today's divergence between Bank Nifty and the Nifty 50 a sign of an impending rally, or just a temporary pause in the downtrend? Share your thoughts with us.
Compliance & Disclaimers:
This newsletter is for informational and educational purposes only and does not constitute investment advice. 'Provisional' data is subject to revision by sources and will be reconciled next trading day. Market investments carry inherent risks, and past performance does not guarantee future results. Readers should conduct independent research and consult qualified financial advisors before making investment decisions.
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Monday, 29 September 2025, 9:57 PM IST.