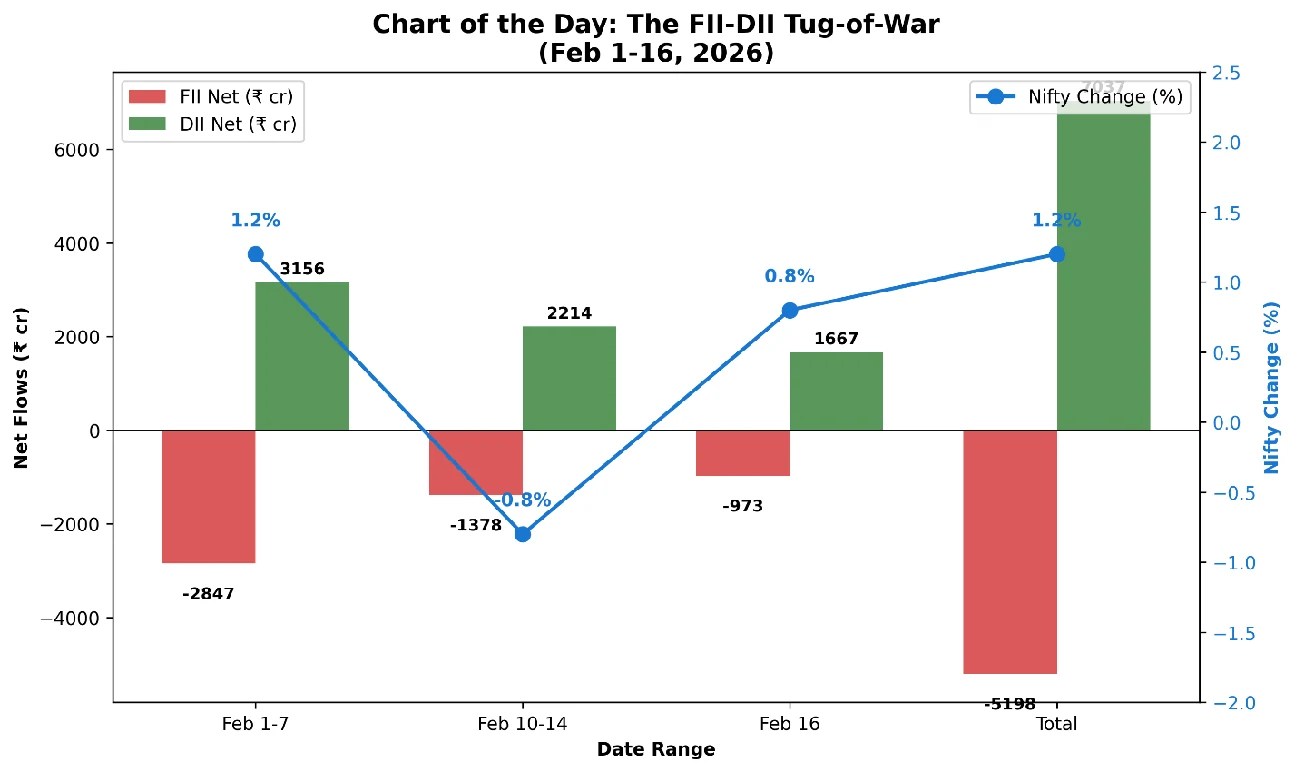
While headlines celebrate Monday's rebound, institutional flows paint a conflicting picture. FIIs sold ₹972.13 crore net across exchanges despite the rally, marking the fifth consecutive session of selling totaling over ₹4,200 crore in a week.
MK
Dr. Murali KalyanaramanGlobal CFO · 30+ years in corporate finance · Chartered Accountant (ICAI) · 12 min read
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Tuesday, 17 February 2026, 8:28 AM IST.
Indian markets enter Tuesday with measured optimism after snapping a two-day losing streak. The Nifty 50 closed at 25,682.75 (+0.83%) and Sensex at 83,277.15 (+0.79%) on February 16, while Bank Nifty outperformed with a robust 1.2% gain to 60,949.10. Yet the real story lies beneath: GIFT Nifty futures opened at 25,641 (as of 06:52 AM), trading 22.50 points below Monday's close—a subtle warning that yesterday's momentum may face early pressure.
What Others Missed: The Divergence Signal
While headlines celebrate Monday's rebound, institutional flows paint a conflicting picture. FIIs sold ₹972.13 crore net across exchanges despite the rally, marking the fifth consecutive session of selling totaling over ₹4,200 crore in a week. DIIs absorbed the pressure with ₹1,666.98 crore buying, but here's the critical insight: derivatives data shows FIIs are building aggressive short positions in Bank Nifty, with put writing concentrated at 59,500-60,000 strikes suggesting they're betting on a breakdown, not a breakout.
The contrarian read: Monday's price action was a classic short-covering rally driven by domestic flows, not conviction buying. With PCR (Put-Call Ratio) at 0.97—indicating balanced but cautious sentiment—and GIFT Nifty's weak opening, the 25,750-resistance zone could turn into a rejection point.
Key Watch Today: Three Catalysts
Rupee fragility – INR closed at 90.78 yesterday, hovering dangerously close to the psychological 91 level. Any breach triggers RBI intervention memories and FII redemption concerns.
China reopens February 24 – Mainland markets remain closed (Lunar New Year through Feb 23), creating a liquidity vacuum in Asian trading. Hong Kong's half-sessions have widened spreads, amplifying volatility.
IPO allotment activity – Retail focus shifts to allotment outcomes, potentially pulling liquidity from secondary markets mid-session.
Global Setup: The Presidents Day Distortion
US markets were closed Monday for Presidents Day, leaving Asian traders without their primary directional cue. The last live session (Feb 13) saw Nasdaq down 2.0% and S&P 500 off 1.6% on persistent inflation worries. With US futures resuming Tuesday and Fed commentary expected this week, expect catch-up volatility.
Commodities tell a different story:
Brent Crude:$68.69/bbl (+1.39% on Feb 16) – rebounding from weekly lows on Middle East supply concerns, but still trapped in a $65-$72 consolidation range.
Gold:$4,994.97/oz (–0.97%) – paring recent gains after US CPI data reduced immediate Fed cut expectations, though geopolitical premiums persist. Asian cues muted: With China closed and Japan's Nikkei showing mixed signals, India trades in isolation today. Australia's ASX 200 opened +0.37%, the only reliable regional indicator.
IPO Pipeline Intelligence: The SME Surge
Marushika Technology – Allotment Today, Listing Feb 19
The ₹26.97 crore SME offering closed with 16.64x subscription at ₹117 issue price, with allotment finalizing today. While the headline multiple looks strong, here's what brokers aren't telling you:
Oorjita Deep Dive:
The technology services firm operates in a crowded IT services segment with razor-thin margins (DRHP shows 8.2% EBITDA margin vs. industry 15-18%). The ₹27 crore size makes it a liquidity trap post-listing—expect 20-30% grey market premiums to evaporate within 3-5 sessions as anchor lock-ins prevent genuine price discovery.
Green Flag: Zero debt on books and 18% revenue CAGR over FY23-25, though from a low base.
Fractal Industries – Subscription Closes Feb 18
The ₹49 crore industrial automation IPO opened Feb 16, targeting BSE SME listing on Feb 23. Early subscription data shows 3.2x on Day 1 (retail category), but here's the nuance:
What the market is overlooking: This is the third industrial automation SME IPO in 60 days,
following two listings that corrected 25-40% post-debut as valuations stretched (₹49 crore at 38x P/E vs. listed peer Electrotherm at 22x).
Sectoral tailwind: Manufacturing PMI at 58.3 and ISM 2.0 semiconductor push (₹1,000 crore FY27 allocation) create genuine demand for automation solutions.
Watch Point: If subscription crosses 15x by Day 3 close, grey market premiums could sustain. Below 10x signals caution.
Funding Radar: The AI Infrastructure Play
Week's Mega Raises: $347 Million (Feb 2-7)
Fractal Analytics led with $137.7 million in anchor funding ahead of a rumored Q3 2026 mainboard listing. Here's the strategic angle others missed:
The AI Infrastructure Thesis: Fractal's timing coincides with the India AI Impact Summit (Feb 16-20) where PM Modi announced expansion of IndiaAI's compute capacity and data center incentives. With 600+ startups showcasing at Bharat Mandapam and 13 country pavilions (including France, Germany, UK), institutional capital is repricing Indian AI plays.
Sector Deep Dive:
Electric Mobility: Drivn ($80M) and Varaha ClimateAg ($20M) reflect ESG capital rotation—EV charging infrastructure and carbon credit platforms are absorbing growth-stage capital that previously went to SaaS
Consumer Tech: The Whole Truth ($51M) and Zilo ($15.3M) signal quick-commerce evolution—clean-label foods and fashion rentals targeting tier-1 premiumization.
Energy Infrastructure: Radiance Renewables ($100M PE) – largest energy deal in weeks, driven by ISM 2.0's power requirements (chip fabs need 24/7 stable grids).
Oorjita Insight: The convergence of AI summit buzz, semiconductor policy push, and anchor funding creates a 2-3 month window where AI/chip-adjacent stocks (KPIT Tech, Persistent Systems, L&T Tech) could outperform on sentiment alone, regardless of Q4 numbers.
Market Movers & Technical Intelligence
The Banking Paradox
Bank Nifty's 1.2% Monday surge was led by PSU banks, yet options data reveals skepticism. Here's what professional traders see:
Options Chain Analysis (Feb 16 expiry):
60,000 Put Strike: Massive writing (+42,000 contracts), indicating institutional support
IT Services (–0.3%) – US budget uncertainty, rupee headwinds
Metals (–0.6%) – China demand concerns (markets closed amplifies uncertainty)
Tech Pulse: The AI Summit Multiplier Effect
India AI Impact Summit 2026 (Feb 16-20) – What Markets Are
Underpricing
Day 2 (today) features launch of AI Knowledge Compendiums covering health, energy, education, and agriculture applications, plus the AI by HER Challenge spotlighting women-led AI innovation. But here's the market implication:
Policy Catalyst Chain:
IndiaAI Compute Expansion – Government signaled scaling from current 10,000 GPU cluster to 50,000+ by FY28
ISM 2.0 Execution – ₹1,000 crore FY27 allocation targets 50 fabless semiconductor firms (up from 12 currently), creating ancillary demand for chip design software, testing equipment, and specialized talent.
French President Macron's participation (Feb 18-19) likely yields bilateral tech MoUs—France's AI ecosystem (Mistral, Hugging Face) seeking India deployment partnerships.
Stocks in Play (Not Buy Recommendations):
L&T – executing 3 of 5 approved fab projects under ISM 1.0, positioned for ISM 2.0 contracts
Tata Elxsi – embedded systems for semiconductor equipment Contrarian Take: Summit-driven sentiment peaks by Feb 20-22, then corrects 5-8% as traders book profits. Real beneficiaries emerge in Q1 FY28 when capex flows materialize.
Macro Crosscurrents: RBI's Tightrope
February 2026 Policy Decoded
RBI's February 6 policy held repo rate at 5.25% (unanimous MPC vote) and maintained neutral stance, but Governor Sanjay Malhotra's commentary revealed three crucial signals markets are ignoring:
1. Rupee Intervention Threshold Hinted
Malhotra referenced "orderly market conditions" four times—RBI code for active FX management. With INR at 90.78 and M2 money supply growing 11.2%, expect dollar sales if 91 breaches.
2. Growth Revised to 7.4% (from 7.2%)
Upgrade driven by manufacturing PMI and capex momentum, but inflation nudged to 2.1% (from 1.9%)—the divergence suggests RBI sees input cost pressures building despite benign headline CPI.
3. Gold Loan LTV Stability Confirmed
RBI clarified banks maintain existing loan-to-value ratios—signal that no immediate regulatory tightening on gold-backed lending, supportive for Muthoot Finance, Manappuram.
Trading Implication: Rate cut expectations pushed to August 2026 (was June prior). Bond markets repriced 10-year yields to 6.82% (+12 bps). Financials face NIM compression longer than anticipated.
What to Watch Today: The Action Grid
Pre-Market (Until 9:00 AM)
GIFT Nifty trajectory – currently –22.50 pts; if weakness extends to –50, expect gap-down opening
Rupee opening – 90.78 close; watch for 91 psychological test
Asian FX – Korean won, Taiwan dollar movements (with China closed, these become India proxies)
Market Hours (9:15 AM – 3:30 PM)
9:15-10:00 AM: Initial volatility as Monday's short-coverers exit; 25,650 defense critical for bulls
11:00 AM-12:00 PM: FII/DII provisional flow data leaks via broker channels—watch for continuation of selling
2:00-3:00 PM: Derivative rollovers begin for Feb 27 expiry; option writers' behavior reveals next week bias
Post-Market
Marushika allotment status updates on registrar sites (KFin, Link Intime)
Fractal subscription numbers (Day 2 close)
FII/DII official data (NSE publishes ~6:00 PM)
Global Cues (Evening/Night)
US markets reopen – Fed speakers (Barkin, Waller) commentary on inflation
China credit data (if released during holiday) – loan growth, TSF numbers
Stocks on Radar: The Selective Five
1. HDFC Bank (₹1,847) – Institutional Darling
Block deal rumors (₹2,400 crore) surfaced late Monday; if confirmed, expect 2-3% dip providing entry for long-term holders. Weight in Nifty (9.8%) makes it index-defense play.
$137.7M anchor raise at rumored $1.8B valuation; if mainboard filing happens by March, retail pre-IPO platforms could see 15-25% premiums.
4. Marushika Technology (SME) – Listing Feb 19
Post-allotment grey market quotes expected ₹145-155 (25-32% premium). Avoid FOMO—wait for listing day correction to ₹115-120.
5. Persistent Systems (₹5,842) – AI Play
Exposure to IBM, Microsoft, Google cloud partnerships positions it for AI infrastructure spending. RSI at 58 (neutral), support ₹5,750; buy dips with ₹6,200 target.
The Contrarian Corner: What Everyone's Getting Wrong
Narrative: "Bank Nifty Breakout Imminent"
Reality Check: While PSU banks drove Monday's rally, credit growth deceleration (YoY slowing to 11.2% from 15.8% in Q1) and rising slippages in unsecured portfolios (flagged in Q3 results) argue against sustained momentum. The 61,000-61,800 zone has rejected prices three times since December—technical resistance converges with fundamental caution.
Better Bet: Wait for quarterly deposit growth data (Feb 28). If CASA ratios stabilize above 41%, then reassess.
Narrative: "Rupee Headed to 92"
Counter-Thesis: While INR at 90.78 looks fragile, RBI's $620 billion forex reserves (fourth-largest globally) and recent dollar sale pattern (₹45,000 crore intervention in January) suggest a 90-91 trading band is the managed float target, not free depreciation to 92.
Trade Accordingly: Short-dated (1-month) call options on USD/INR are mispriced—implied volatility overstates directional risk. Sell 91.50 calls, pocket premium.
Hedges:10% (put options at 25,400, 25,200 strikes)
Disclaimer: This analysis is for educational purposes only. Markets are subject to risks and uncertainties. Please consult your financial advisor before making investment decisions. Past performance is not indicative of future results.
Oorjita FinAI Services
Investing Beyond Today
Disclosures and notes
Website: oorjita.ai
Newsletter Editions:
Morning Brief (Pre-Market Analysis) - Daily 8:00-8:30 AM IST
Evening Update ("What We Missed") - Daily 7:00-7:30 PM IST
Weekly Market Manthan - Every Sunday
Quarterly Company Deep-Dives (Samiksa Oorjita Series)
Hidden Gems Deep dive
Compliance & Disclaimer
www.oorjita.ai is not operated by a broker, a dealer, or a registered investment adviser. Under no circumstances does any information posted on www.oorjita.ai represent a recommendation to buy or sell a security. The information on this site, and in its related newsletters, is not intended to be, nor does it constitute investment advice or recommendations. The information on this site is in no way guaranteed for completeness, accuracy or in any other way. In no event shall Oorjita Fin AI Services be liable to any member, guest or third party for any damages of any kind arising out of the use of any content or other material published or available on www.oorjita.ai, or relating to the use of, or inability to use, www.oorjita.ai or any content, including, without limitation, any investment losses, lost profits, lost opportunity, special, incidental, indirect, consequential or punitive damages. Past performance is a poor indicator of future performance.