
Dramatic Reversal in Foreign Flows
The morning brief anticipated a "flat to marginally positive opening" with GIFT Nifty at 26,055.50 (+0.15%), projecting continuation of Monday's bullish momentum.
The morning brief anticipated a "flat to marginally positive opening" with GIFT Nifty at 26,055.50 (+0.15%), projecting continuation of Monday's bullish momentum.
Intraday Dynamics: Nifty tested the 26,000-26,042 resistance zone twice before retreating, indicating supply overhang.
Supreme Industries: Net profit declined 20.26% YoY to ₹164.74 Crore - stock fell 4.66%
Asian Markets: Mixed performance—Japan's Nikkei and South Korea's Kospi saw profit-booking after recent rallies, mirroring India's pattern.
Nifty's 26,000 Test: Third attempt to break this psychological barrier—success would open 26,200+ targets
This research is for information and education only and is not investment advice. Figures may be provisional. Oorjita.AI and its authors may hold positions in securities mentioned. Please consult a SEBI-registered investment adviser before making investment decisions. Published Tuesday, 28 October 2025, 9:16 PM IST.

Bearish Marubozu — A candlestick with no upper shadow and a minimal lower shadow. It signals relentless selling from open to close with zero buying recovery.

While headlines celebrate Monday's rebound, institutional flows paint a conflicting picture. FIIs sold ₹972.13 crore net across exchanges despite the rally, marking the fifth consecutive session of selling totaling over ₹4,200 crore in a week.

India's power transmission network requires massive expansion to support the target of 500 GW renewable energy capacity by 2030. The government's focus on grid modernization and interstate transmission corridors creates a multi-billion dollar opportunity.
The morning brief anticipated a "flat to marginally positive opening" with GIFT Nifty at 26,055.50 (+0.15%), projecting continuation of Monday's bullish momentum. However, Tuesday's session told a different story—markets opened higher but succumbed to persistent profit-booking, closing marginally negative despite massive institutional buying.
Opening Direction Correct: Nifty opened at 25,939.95 vs Monday close of 25,966.05, broadly in line with GIFT Nifty indication
Currency Pressure Validated: USD/INR reached 88.2960 (RBI reference rate at 1:00 PM), confirming the morning's 88.24 spot estimate
Q2 Earnings Focus: TVS Motor, IOC, Mazagon Dock results were indeed market drivers as predicted
Sectoral Themes: PSU Banks, Metals continued strength as anticipated in morning analysis
Volatility & Direction Underestimated: Morning brief suggested "flat to marginally positive" but failed to adequately flag profit-booking risk after Monday's strong +0.66% rally
FII Reversal Not Anticipated: The dramatic shift from Monday's -₹241.75 Cr FII selling to Tuesday's massive +₹10,339.80 Cr buying was not forecasted
The thematic deep-dive on India's startup ecosystem, Reliance-Meta AI JV context, and semiconductor revolution provided valuable strategic insights that remained relevant. The emphasis on US-China trade deal optimism driving global sentiment materialized, with Wall Street hitting fresh records.
The morning brief's bullish bias overlooked key warning signs: Monday's 0.66% gain created overbought conditions near 26,000 resistance, FII selling trend on Oct 27, and elevated valuations in Realty/PSU Bank sectors that rallied 1.5-2.2% on Monday. A more balanced "consolidation likely" call would have been more accurate.
| Index | Open | High | Low | Close | Change | % | Significance | |
|---|---|---|---|---|---|---|---|---|
| Change | ||||||||
| Nifty | 25,939.95 | 26,041.70 | 25,810.00 | 25,936.20 | -29.85 | -0.11% | -0.11% | Failed to hold 26,000 |
| 50 | psychological mark | |||||||
| Sensex | 84,625.71 | 84,986.00 | 84,267.00 | 84,628.16 | -150.68 | -0.18% | Modest decline despite institutional support | |
| Bank Nifty | - | 58,313.80 | 57,770.35 | 58,214.10 | +207.55 | +0.36% | Outperformed | |
| benchmarks, PSU | ||||||||
| banks resilient | ||||||||
| India VIX | 11.86 | - | - | 11.95 | +0.09 | +0.76% | Marginal uptick, still at comfortable levels |
Intraday Dynamics: Nifty tested the 26,000-26,042 resistance zone twice before retreating, indicating supply overhang. The 232-point intraday swing (high to low) reflected heightened volatility as profit-booking intensified post-noon.
Market Breadth: Negative - 2,482 declining stocks vs 2,067 advancing out of 4,549 traded, indicating broad-based selling pressure.
The rupee weakened past the 88.30 mark intraday, reflecting sustained dollar strength amid Fed rate policy uncertainty and persistent trade deficit concerns.
The Paradox: Despite this massive ₹11,421 Crore institutional support, markets closed marginally negative (-0.11%), indicating retail and algorithmic profit-booking overpowered institutional demand. This suggests near-term supply overhang but strong institutional conviction for medium-term upside.
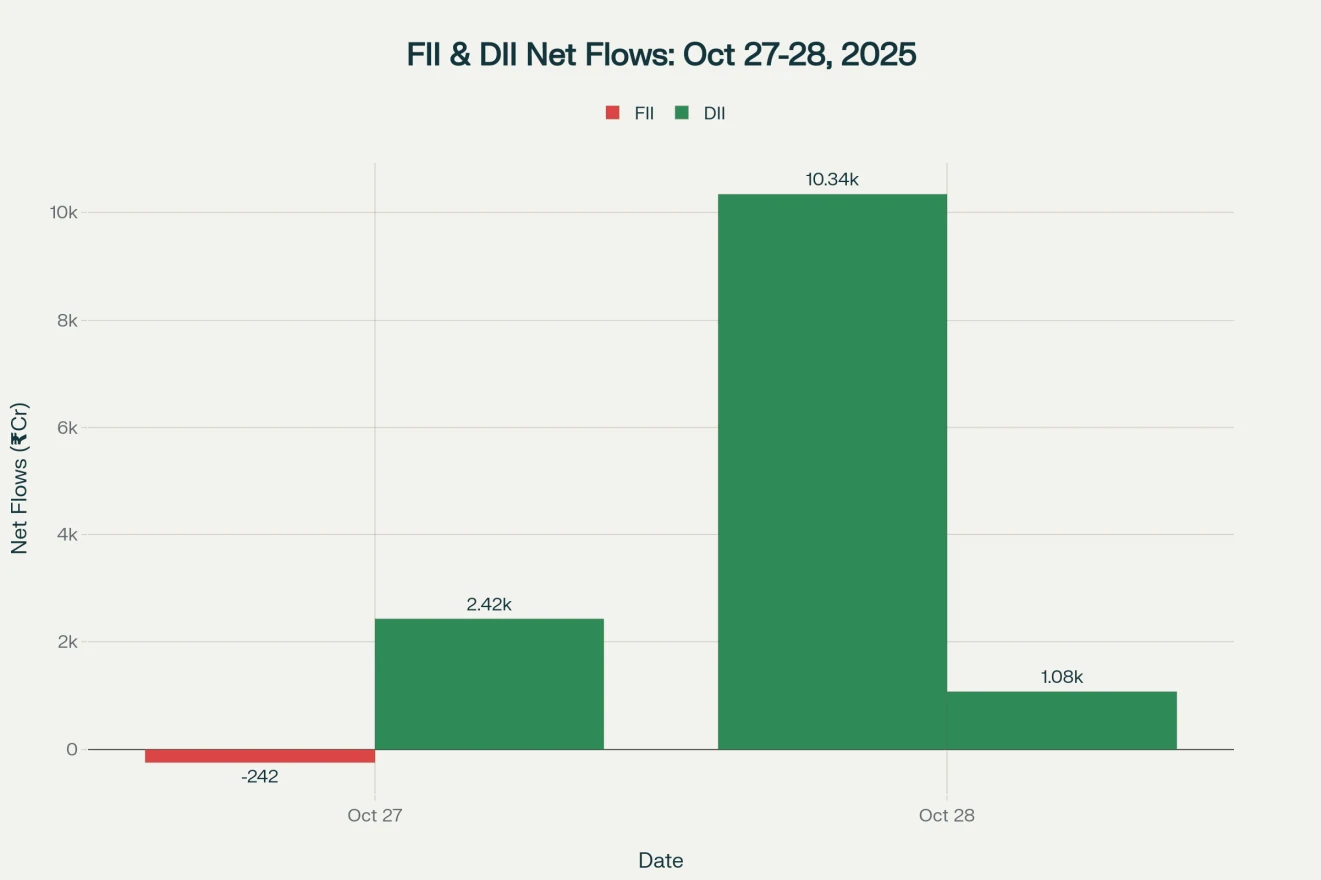
FII and DII net institutional flows for October 27-28, 2025, showing dramatic reversal in FII sentiment from net selling to massive buying of ₹10,339.80 crore on Tuesday.
Pattern Recognition: Nifty formed a narrow-range doji with a long upper shadow, indicating rejection at 26,000-26,042 resistance zone and potential distribution. The failure to sustain above Monday's close despite opening higher is a bearish sign for near-term.
Volume Analysis: While specific volume data for Tuesday isn't available in attached files (Monday showed 266.34 million shares on Nifty), market breadth at 2,482 declining vs 2,067 advancing indicates genuine distribution.
Risk-Reward Setup: Current juncture offers poor risk-reward for fresh longs. Traders should wait for either:
Wall Street (Tuesday Close - Post IST 8:00 PM): US markets extended gains for the third consecutive session, with major indices hovering near record highs as US-China trade deal optimism persisted and investors awaited Fed commentary.
Asian Markets: Mixed performance—Japan's Nikkei and South Korea's Kospi saw profit-booking after recent rallies, mirroring India's pattern.
Crude Oil: Brent remained stable near $65-66/barrel; US crude around $62/barrel.
Gold: Spot gold trading around $4,083/oz, posting its first weekly decline in 10 weeks as risk-on sentiment reduced safe-haven demand.
This newsletter is for informational and educational purposes only and does not constitute investment advice. 'Provisional' data is subject to revision by sources and will be reconciled next trading day. Market investments carry inherent risks, and past performance does not guarantee future results. Readers should conduct independent research and consult qualified financial advisors before making investment decisions.